

Join the mailing list!
Can you really trust financial advice when money is on the line?
Incentives in finance drive human behaviour and often they don’t work in your favour. From wealth managers to bloggers, affiliate marketers to community admins, the financial world is riddled with conflicts of interest. If you don’t have your eyes wide open, you’ll pay the price.
Katie says: “Never ask a barber if you need a haircut.” Why? Because the barber only makes money if they say yes.
The same principle applies to financial advice. Let’s dig into why incentives matter and how they warp behaviour.
Luckily Katie is my barber and her only incentive is having a handsome husband to look at!
The Incentive Problem in Finance
Incentives shape behaviour and in finance and they can warp advice.
In the US, many advisors still earn juicy commissions for selling high-fee products like mutual funds and insurance. That means the advice you get might be probably is influenced by what pays them most, not what’s best for you.
In the UK, things changed in 2012. Commissions on investment advice were banned, and advisers are now meant to charge transparent fees. That’s not always the case. High fees can still sneak in through platforms, funds, and “ongoing service” charges.
Here’s the math: a 1% annual fee sounds tiny, but over 30 years it can vaporise hundreds of thousands — even a million pounds. Want proof? Read our impact of fees article.
Action step: If you don’t know your total fees, stop reading and check now. Seriously.
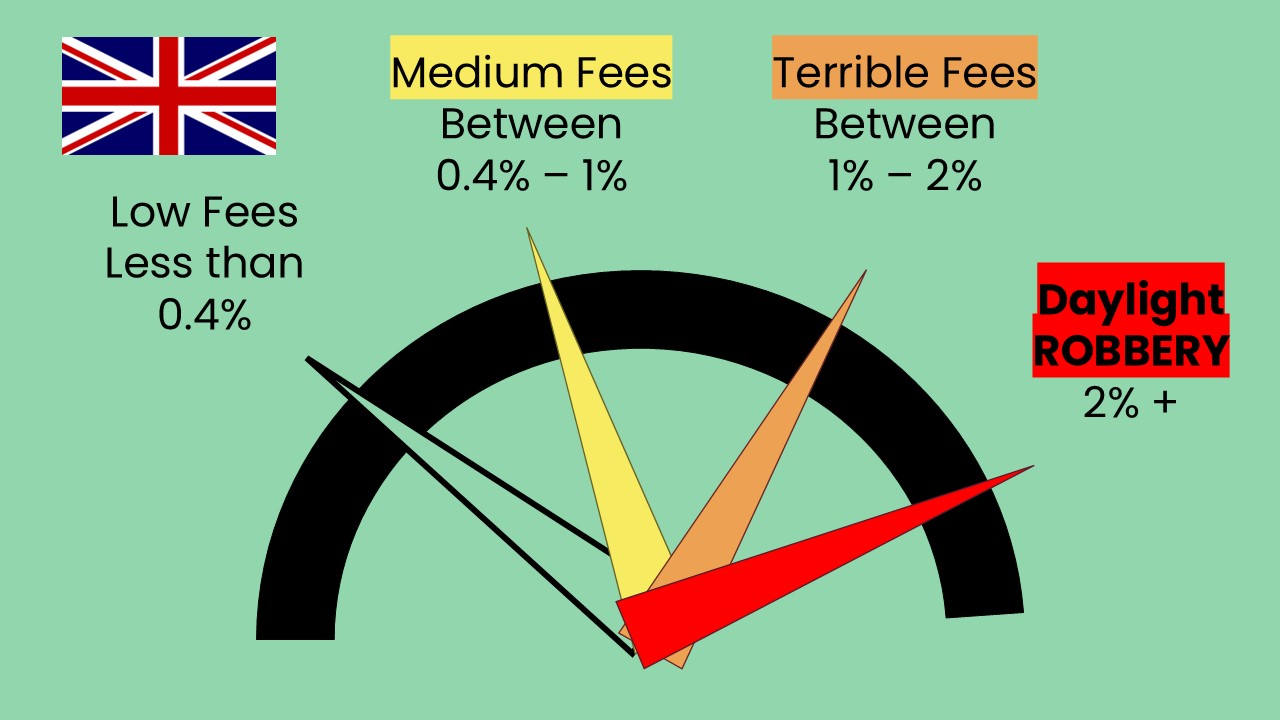
What’s fair?
- Under 0.4%: Good
- 0.4%–1%: Bad
- Over 1%: Terrible
Your money deserves better. Don’t let incentives or hidden fees steal your future.
Affiliate Fees and Skewed Recommendations
Take a look at this article on the Best SIPP Providers in the UK from Kelper Trust Intelligence.
Notice anything? Any notable absences from the list? Vanguard, one of the cheapest and best providers for portfolios between £30k and £120k, isn’t even mentioned. Why? Because Vanguard doesn’t pay referral or affiliate fees.
Who is their recommended provider? Interactive Investor (ii) who are currently paying a £400 referral fee to get your business. If I was writing this blog to make money I would have a HUGE ii banner at the top saying go with them!
They call themselves Trust Intelligence, but their recommendations are warped by affiliate income. This isn’t unique – it’s everywhere. Incentives in finance often mean the “best” lists aren’t really best for you.
When Communities Go Wrong
Recently, in our own Rebel Finance School Facebook group, we discovered something deeply disappointing: people joining as moderators or admins and deleting other members’ referral codes so they could insert their own and make thousands from referrals. This is not acceptable.
Originally, we allowed referral codes when someone directly asked for them, that felt fair. But then people started making recommendations just to earn referral fees and even deleting others’ codes to boost their own income. Their motives shifted from helping the community to chasing money. That’s not what our group is about.
Some were even recommending platforms like Hargreaves Lansdown (charging 0.25% fees) to people with small portfolios, despite better-priced options, even free ones, being available. If we allow this, we’re no better than the wealth managers we criticise, like St. James’s Place, who profit from high fees while pretending to act in your best interest.
To be clear: we’re not against people making money when they give genuine, helpful recommendations. That’s great. But when incentives corrupt behaviour and harm trust, we have to act. And we did, we removed those people from the Facebook group.
Standing Up Comes With Challenges
As Rebel Finance School grows, we’re taking a stand against high-fee wealth managers and conflicted advice. That means we’re taking away income streams from people who profit when you make poor financial decisions. If you invest without them, they lose customers and therefore money – and some won’t take that lightly.
We’ve already seen Independent Financial Advisors (IFAs) and others throw stones at our integrity to protect their livelihoods. And recently, we had to make some tough calls: removing people from our community who abused trust by deleting others’ referral codes and prioritising their own financial gain over helping the group.
This has not been an easy decision. We see the best in people and want to believe everyone is here for the right reasons. Discovering this behaviour was disappointing and difficult to deal with. But if we want to stand up for what’s right and protect the integrity of the community, we have to make tough calls.
This makes me nervous, but if I want to stand up and be counted, I have to expect attacks. What I want you to know is that, if you see people saying negative things about us in other Facebook groups or online, understand why. They’re worse off because we’re helping you invest without them. Their incentives are clear, and incentives drive behaviour.
The bigger the course and the group gets the more this is going to happen. At the moment we think standing up is worth the cost of dealing with these issues.
The UK Is Just as Money-Motivated
We like to think we’re less money-hungry in the UK than elsewhere. From what I’ve seen, that’s not true.
Incentives in finance warp behaviour everywhere – IFAs, bloggers, even community leaders. Always ask: “How do they gain from this?”
A note on UK financial advisers
After publishing, we got a comment from Paul and another IFA that shared helpful context.
In the UK, commissions on retail investment products were banned at the end of 2012 under the Retail Distribution Review (RDR). Adviser charging is now separate from products and must be disclosed, and firms must describe whether advice is independent or restricted.
Since 2023, the FCA’s Consumer Duty says it has raised the bar on fair value and outcomes.
What is the FCA and what’s its mission?
The Financial Conduct Authority (FCA) is the UK’s financial watchdog. Their job? Keep the financial system fair, honest, and working for consumers. They regulate thousands of firms, set rules to protect you from dodgy practices, and make sure companies put customers first. From banning hidden commissions to enforcing transparency and fair value, the FCA’s mission is simple: protect consumers, keep markets clean, and promote healthy competition so you can invest with confidence.
Sounds grand, it is up for debate whether they achieve it. They told St James’s Place (SJP) off for exit fees a year or two ago and we still get messages from people being charged them.
Financial Advisors in the UK
Paul tells us that many advisers do use low‑cost index funds (entirely or in part), and fund selection is only one part of their holistic advice. Maybe we just come across the people who have high fee, wealth managers, asset under management IFAs that do a terrible job.
Here is why we have a problem with financial advisors that recommend high fee, actively managed funds, which both Katie and I have fallen foul of in the past.
The long‑term data on active investments versus passive investments is consistent: across categories and time horizons, most active funds underperform low‑cost passive alternatives after fees. Recent Morningstar work places the 10‑year success rate for European active equity managers at roughly 14.2%. Read the full Morningstar report here.
SPIVA scorecards show the majority of UK (and global) active funds lag their benchmarks over longer periods. Fees matter, and they compound against you.
What about St. James’s Place (SJP)?
BOOOO. Yes, SJP now offers some low‑cost index‑tracking options and has tweaked its charges. That’s minor progress and lots of people are quick to point this out when we are down on them.
But here’s the kicker: layered costs still stack up, advice fees, platform fees, fund fees. What do we mean by layered costs? You pay X% for advice, X% for the platform X% for the funds x% entry and exit fee and more and they just keep layering on the costs.
Transparency matters because those layers eat into returns. SJP has also faced scrutiny under the FCA’s Consumer Duty for how ongoing advice is delivered which they say they are starting to face up to their responsibilities to their clients.
The real problem with advisors is it is that it is so difficult to tell the difference between a good one and a bad one. By the time you are able to tell the difference you have probably learnt enough not to need one at all.
So here’s our position, clearly:
✅ Global Low cost index funds tend to out perform actively managed funds over the long term. Here is an article from Morningstar about your chances of winning with actively managed.
✅ Fees: Make sure you dig into the total cost because layers of fees can quietly eat your returns. Make sure you understand all the different layers of fees that apply to your investments.
✅ Transparency is king. If you can’t easily see what you’re paying and why, that’s a red flag. Have you tried reading some of the bigger firms T&Cs and fees documents?
✅ Results matter. Fancy brochures, birthday cards and Christmas cards don’t grow your wealth, low costs and simplicity do. Why are so many advisors still recommending actively managed funds when they know they underperform?
✅ You’ve got options. With a little homework, you can DIY and keep thousands in your pocket instead of handing them over to expensive advisors.
Finally, this article was primarily about a different incentive problem we uncovered inside our own Facebook community: people posting recommendations to earn affiliate fees, even deleting others’ codes to insert their own. That’s the behaviour we acted on and worked to cut out of our grou
Our Own Incentives (Full Transparency)
How do Katie and I gain from Rebel Finance School? When we started, we paid for everything ourselves — Zoom subscriptions, website hosting, mailing lists. We lost money and did it because it was fun and it was our gift to the world.
When we outgrew a normal Zoom meeting, Zoom wanted £10k+ a month for the webinar version! So we switched to streaming to YouTube live so we could have a “meeting room” of unlimited space and so that people could watch on catchup (something you couldn’t do in the first couple of years that we ran the course).
After a year, our channel reached the criteria required to receive ad revenue from YouTube. I was excited as I thought it would reduce the amount it costs us to run the course each year!
Today, that income has grown but still doesn’t cover the costs of running the course. Maybe one day it will – but that’s not why we do it.
There’s nothing wrong with earning money. It’s how you earn it that matters. If I sell you a coffee and you love it, great. If I sell you a high-fee fund that damages your financial future while lying about the stats, that’s not okay.
How to Protect Yourself
Practical Tips
- Follow the money: Ask how the person gets paid.
- Look for transparent fee structures.
- Be wary of affiliate-driven “best of” lists.
- Learn enough to make your own decisions, don’t outsource blindly.
Conclusion
Incentives aren’t evil but they are powerful. Understand them, and you’ll protect your wealth and your trust.
What do you think? Do you ever stop to ask what’s in it for the other person? Have you spotted conflicts of interest?
From affiliate links to high-fee funds, incentives are everywhere. How do you protect yourself? Tell us in the comments below
Peace and Pineapples
Alan and Katie
60 Comments
Leave A Comment
Related Articles

Blog, Financial Independence, Save and Invest
Where do I put my money? Hello there! We wrote this article in 2025. Platform fees in the UK have changed a lot since then! Look out for an updated article coming soon.....With such a confusing array of platforms, funds and fee structures how do you ever decide where to put your money? In [...]

Blog, Donegan Update, Keeping Track
5th Jan 2026 At the end of the year, Katie and I always get excited because this means a chance to do our annual finance review! How often do you review your finances? Do you check daily, as some people do when they first find out about investing, or are you a set it [...]

Blog, RFS2025, RFS2026
After every single Rebel Finance School session in 2025, Katie and I sat down and wrote notes about what we could improve for next time. We had a lot of ideas. But here’s the thing we’ve learned the hard way over the years: our ideas are not as important as what actually works for real [...]

Thankyou for writing such an open and honest viewpoint and update on recent events. Money can clearly be a motivator for so much good but clearly comes with some pitfalls and greed can sometimes cloud peoples judgement. Peace and pineapples to you both 🍍💛
Thanks for the reply Lisa. It is really interesting to see how far people will go for financial incentives and how sometimes ethics and honesty are thrown out of the window so fast….
Alan and Katie, well said. I find the community very helpful and hope that it can continue as the caring community I believe the majority of members are. From helpful comments to area meet ups. Let’s keep this fantastic community transparent and honest. 👍😎
LOVE the focus Linden and YES YES YES. Let’s get it all focused on helping each other be successful…
A great article and thank you for your honesty around what was happening in the group with referral codes.
I experienced this once. Someone asked if anyone had a referral code and I actually went off and found one but it was deleted. I assumed I had broken a rule so I have not shared one again as that was my first experience.
You didn’t need to publicly highlight this but that’s your integrity showing. Thanks again Alan and Katie
Thank you for your time and commitment to helping others. Also for standing up for the values of RFS when the minority try to influence it in a disingenuous manner.
Your transparency and honesty is a credit to you both.
Thank you, for what you do, as for me it has been truly transformative to my financial outlook and ultimately to my future quality of life. For which I will always be grateful.
Thanks Alan and Kate for this article. When I didn’t know a thing about investing, I did the RFS course 5 years ago and now I am better off financially. Your magnanimous heart has inspired me too to continue to give back to the world in many ways. God bless you both!
Great article, very helpful and honest. I have seen a number of people sharing ii referrals on the FB page and I did think to myself, that’s not very Kantian! I have joined ii and do have referrals to share, but would never would, as to my mind people have to make their own decision as to the platform to use, and as you state, getting no fees for a year massively influences that decision! I love the community and the group and I’ll now be monitoring for anyone sharing referrals and letting you guys know.
I wondered whether the number of your followers would naturally create these types of barriers to you doing what you love doing. I’m sorry you’ve had to overcome some of these things recently, it’s not a nice result of success. Please always remember how you’re changing the lives of so many people and it’s only the minority ruining it for the rest or us. Seeing you both in your workshops keep be motivated to keep going with building my financial security. Great convo to have, it was informative and likely self healing for you to affirm what you’re doing. Peace and pineapples 🍍
Thank you so much for this – when looking for a home for my tiny SIPP I followed the FB page really carefully and saw constant referral codes for IE and II and didnt know what to do. I tried to sign up with IE as it was recommended / free/cheap etc – but I couldnt even get past registering my security authentication, kept getting the same message from a bot. So I left it – then spent time going back to your ‘platform review’ – read the article – took on board all the info and made the decision to go witb HL – which Im aware isnt the cheapest but – it eas super easy yo set up, communication has been great -the transfer was prompt, I easily bought the Vanguard global fund – set up a monthly DD just from my phone. My son haz also opened a LISA with them and I feel quite confident in my choice – abd that is what I needed to make – a decision based on information that was relevant to me. Thank you so much for this.
So very true. Follow the motive there you’ll find the money. Thank you for your transparency, your generosity is a reminder that there is good in humanity. You both are legends! (that’s what we say here in Aus)
I have only just found you two, oddly, from mumsnet ( odd because you go on the forum for family advice!), and I have started watching the course via catch up on YouTube! It is really informative and I feel I am getting financially literate by each session. I can’t wait to put this knowledge to use once I am through with the course. And to you both, simply a HUGE THANK YOU for dedicating your time this way. I do not take it for granted as I am sure most of your fan base. God bless
Violet, thanks for the lovely message. That is so cool you found us through Mumsnet. wow. And we had so much fun putting the course together. Please let us know hoy you get on! Thank you for writing. Alan
Thanks guys
I know how upsetting you two found this.
You are great at Transparency and I believe you two to be genuine generous people. ❤️
Thanks Melanie, this one stung a lot to have people working against us and for a different higher value. Thanks for commenting. It means a lot. Alan
Thank you Kate and Alan. I have learnt so much from you both. Thank you both for your honesty and integrity – qualities which are often in short supply in the world particularly the world of finance. I wish I had discovered your course many years ago (though it did not exist 10 or 20 years ago when I was much younger). I hope to pass on your expertise to younger members of my family.
Keep doing what you are doing and posts like this are essential Alan as the community gets bigger and you become more well known.
Thank you
Catherine, we wish we had discovered all this earlier too! lol. I am so glad you are sharing the message with the younger generation and helping set them up too. That is awesome. Sending you huge happiness. Alan
Ethical thinking and behaviour is sadly missing in action these days, maybe it’s always been like this and we just weren’t aware! So many many thanks for being ethical.
Thanks for replying Susan. I think we are more aware of the unethical thinking through writing and media which is good to keep us safe. I still think there are mostly wonderful people in the world but there are those that will take advantage given the opportunity! Thanks for commenting. Alan
I totally agree with what you are saying and feel people are simply taking advantage of other people’s lack of knowledge. And while it’s controversial the phrase “have you done the course yet “ is sometimes appropriate, just to try help them gain additional knowledge and be able to help them make their own decisions.
Hey John, that was always the aim, share the knowledge so people could decide for themselves, empower people to make decisions based on fact, maths and knowledge not emotion. Thanks for commenting it means a huge amount. Alan
Thank you so very much and Katie for spending your time and money
In protecting our interests as ever. This article highlights why we all need to be extra vigilant when others are looking to gain personality from you, when instead you transparency teaches us that we each have the capacity to work for our own long term gain without the need to be be influenced by the takers of this world. Your mission to help as many people as possible through your own personal experiences and knowledge, so that we all do not fall into the same traps as you onc did, is a priceless gift that I can honestly say has completely changed my life. Having had the gift of freedom to choose what I do at a very difficult time in my life has been an indescribable blessing for me and at a time when I have needed it the most thanks to Alan and Katie directly. Reading this article brings home to each person that reads it, why it is important to read small print and the real difference it can make to your life. Thanks a million Alan and Katie for literally everything you both do for all us Rebel followers – the world is a much better place because of you both being here in it!! With much appreciation, peace., love and pineapples. Sally May x 🤗❤️🍍🍍🍍
Sally May, your comments always light up my day. Thank you for writing. it has been ages since we have seen you and I am sorry it has been a tough time but I am glad of the freedom you have had to deal with it. You are awesome. Thank you for writing and sending you so much love! Hope to see you next time we are home… Alan
Thanks Alan and Katie. Solidarity to you and the work that you are doing. It was nice to see you in the RBS last week. Stay strong. Vamos!
Oriol, Vamos! I loved being on RBS with Simon and working on that. He is fabulous and Katie and I loved designing the two new sessions for them this year. Sending you huge happiness. Alan
Thank you for all you are doing and being in the world. I hear in this a value of right livelihood and so appreciate your courage and strength and resilience for making the tough calls and standing for the best! Carry on!
Vicky, thanks for writing back. You are awesome. Sending happiness back to you. Alan
Agreed, your point of view is always greatly appreciated! I’ve been a member and follower of RFS for over 4 years and the practical advice and way to implement has made my financial life MUCH better. Additionally your approach has served as a true inspiration to me, and I want to follow your lead by offering my services for free to my end users, and hopefully leave the world a better place. Thanks for all you do!
Thanks for taking a stand and explaining your point of view. I have a ton of respect for what you two are doing for the community. Stay strong.
Thank you Alan and Katie for sharing your financial knowledge and appreciate the stance on integrity within this community. I felt I had come late to the party and wish to thank you so much for the access to the course which has led me to change financial decisions which has led to my money working for my benefit in retirement. Keep doing what you are doing, all the best, Mary
Alan and Katie, thank you for all that you have done and continue to do. I am retired from law enforcement and investigated financial crimes, elder abuse, and cyber crimes for many years. I agree with your analysis of the problem and I like your approach.
Thanks Steve, we really appreciate that. Wow I bet you have some skills from that work. if you ever want to help us up our game in protecting people or have ideas please tell us. Sending happiness. Alan
As always well thought out and lucid.
Cannot thank you enough for highlighting potential pitfalls and standing up to the unscrupulous who are hiding behind the cloak of affiliate fees etc
Brilliant as always
Thanks Alister. I really appreciate your response.
A great post. Integrity is everything and you are protecting the integrity of the Rebel brand. The behaviour you highlighted is not within the spirit of Rebel.
I read a book years ago about investing in property. The author said always ask why people are giving your information or guidance, what’s in it for them?
I am sad, but unfortunately not surprised that this has happened to your fabulous group. It must have been very upsetting for you both on several levels. Since stumbling across RFS from a recommendation in another completely unrelated group, I and my extended family have benefitted more than I can express in a few words, from everything you have given to the world from a position of kindness, generosity and, I believe, genuine concern. Thanks to RFS I and three generations of my family now have a MUCH brighter future. I also feel somewhat conflicted because I have had some excellent help from very knowledgeable group members, and I really hope this will continue to be the case. However, I had noticed some contradictions in behavior and group rules, so I’m thankful for your actions there and admire your willingness to uphold your own principles. Maybe there is a case for separate groups for beginners (where they can be helped through the basics until they have made their own initial informed decisions) and ‘graduates’ of RFS (where there is more advanced help and an assumption of basic knowledge and experience). I think this could solve a few issues, but obviously as groups grow, the admin task becomes huge and there are few truly altruistic people like yourselves who would be able to do it. I hope to be of some support to the group and one day give back something myself, as I try to do in all groups where I received help. Please know that in time, everything will work itself out and that everyone is where they need to be right now. Please keep on being you two!
You guys are so correct, and I hope people value all you say and all the incredible honest advice you give . Excelent advice …. and you’ve always tried to explain this to people and I’m sure it’s very appreciated . You both a great team. Thanks for Rebel Finance
Why not just have approved referral links on your web site, with the proceeds going to charity and point people to those? Perhaps as part of the choosing a platform blog post?
Love that idea Steve, Thank you. We will look into that!
I want you to know that I fully respect and support the actions you’ve taken. I also want to acknowledge the intellectual and emotional labour involved – it’s obvious to me that this has taken a great deal of thought and heartache for you both.
Would you consider a fundraiser to cover the costs of what you do? Or some means of financing it consistent with maintaining your integrity? I think it’s time for this given the growth of the community.
Dorothy you are so kind and so wonderful. Thank you. We have been considering it and how to do it. costs have gone up, but YouTube income has gone up too which covers a lot more. The integrity piece is the biggest piece for us and we haven’t worked it all out yet. Thank you for the message. It really made me feel more comfortable this morning reading it. Sending you much happiness from Colombia! Alan
Thanks for writing this, its very refreshing to read this and thank you for your help, but its left me slightly confused as ive just opened a II account at the recommendation of others in the group, where as I wanted to go with vanguard, as thought it would be better for my funds all round, I’m just about to transfer my pension from SJP to II, should I go with my gut and stop the transfer and go with Vanguard – I want to pay in from my business as well and dont think I can do this from vanguard – thanks for your help
Hey Raea, both ii and Vanguard are great choices. ii let’s you do employer contributions where as Vanguard doesn’t yet. It does allow you to do director contributions though so if it is your company and you are a director you can do that straight from your company. Both platforms get good reviews. I can’t give you advice. Either one will be a good choice bit if it was me I would go with Vanguard. There is no wrong answer…. Does that help? ALan
I found this post reassuring and heartening. Im not surprised you have discovered dishonest and untrustworthy people infiltrating the group, they will pop up in all areas of lfe unfortunately, but its fantastic that you dealt with this and filled everyone in on what has been happening. A large part of why I love RF and yourselves so much is down to your integrity and openness. Peace, love and pineapples to you both.
Douglas thank you for the lovely message. I really appreciate that. It does happen, I am annoyed it did happen but we have tackled it and we both can’t help getting the feeling that it is going to happen more and more as the course and communities grows. We will have to keep looking out for it! THanks for messaging. it means a LOT!
Hi Alan, thanks for all the info. I just have a quick query regarding what you said about Vanguard. I have a Vanguard account with about £4000 in it, and last year they emailed to say they were raising the fee to £4 per month. Possibly I’m doing the maths wrong but that seems significantly higher than the old 0.15% they used to charge – I need to look into whether there are other cheaper options available, but was wondering if they still deserve the accolade of being super cheap? Maybe that’s only the case for higher rate investors?
Thanks, and apologies if I’ve misread or got the figures wrong – I find these kinds of things very confusing!
Sarah, yes they annoyingly put in a minimum account charge of £4 a month so as a percentage if you have a relatively small pot of £4k then it is a bigger percentage. There is a free SIPP and a free ISA now with Trading 212 and Invest Engine which is better when starting. Vanguard is excellent value between 30k – 120k ish and then interactive investor becomes cheaper after that. Vanguard offers better service and the ability to call them than the free ones….. Does that help at all Sarah? It took us ages to get our heads around it too! ALan
Thank you so much Alan, really appreciate the reply and the clarification. I’m going to do a big review of my finances when I have some time off over Christmas so will take a look at the two you’ve suggested for starters. I had much more in Vanguard originally but then bought a flat which cleaned it out!
Thanks so much again, it can be so hard to cut through all the numbers and advertising with this so hugely appreciate all the time and effort you put in to providing a truly ethical source of information and support, it really is unique. Thanks again!
Sarah your message made my day! YAY. It is our pleasure and please let us know how you get on! Christmas is a wonderful time to do it! The best gift you could give yourself! Alan
What worries me is the fact that after a period of time will Kate and Alan get fed up with helping people,
Give some people an inch and they take a mile,
It’s all about to words loyalty and integrity,,,
Here’s away 3/4 of the population know nothing about,
Two people have gone out of thier way to help thousands of people have a better life,
The pair could of just gone about their lives and thousands of people would still be working the work tread mill until old age
But Kate and Alan you know when you win, is when the fiance sector slag you down, you have them worried,
I personally agree with kicking individuals out of a group when it challenges the ethos of what that group is set up for,
So please don’t get disspondent you really have changed people life’s for the better
John thank you for your kind words. I am reading them over breakfast and they gave me hope and energy to keep going. I really appreciate you commenting! Sending happiness. Alan
This statement is simply not true:
“If an advisor recommends low-cost index funds, they earn little or nothing.
If they push high-fee active funds, they make big commissions – at your expense.”
It is not true at all. Please learn properly about this. It is just so wrong.
1 – commissions on advised investments were banned in 2012 and advice fees were separated from products / funds.
2 – the vast majority of advisers recommend low cost index funds – either entirely – or as part of a portfolio. Even SJP now offer very low cost index funds.
3 – advice fees are not linked in any way to whether their investment philosophy is passive (index funds) or active funds.
4 – the role of an adviser is far broader than advising on fund selection
Paul thank you so much for your comment. I really appreciate it. I have completely reworked the article this afternoon and you were right to message. Thank you. Please let me know if it is better and now reflects what you rightly pointed out. Alan
Thanks. It’s an improvement on the previous. Still disagree with some of the framing, but at least the factual statements are broadly right.
Thank you Alan and Katie for sharing all your knowledge and expertise to help the rest of us. A year ago I knew nothing about investing and would have happily let a financial adviser invest my money, thinking that a 2% fee was fine. I came across rebel finance by chance and I’m so glad I did – now I’m confident to invest my own money and make my own financial decisions about my future. I’ve told my friends and family about the course and now they’re doing the same. You guys didn’t have to help anyone but I am very grateful that you made that choice
Lee what an amazing message to get and congratulations for taking charge! 2% is crazy and so high. We fell into the same trap initially as well and only learnt later of the impact of fees over time. Thanks for messaging. It means a lot. Alan
Thank you!
Thanks bunches 😊 🍍
You guys are amazing.
Thanks Victoria! Love you!
Great article. Would it be possible for you to have a space for recommended IFAs on your site from either yourselves or other rebels? It is very difficult to know who is good or bad if just wanting one off advice from the hundreds that are available. Maybe they only get listed if more than two people recommend them or they meet certain criteria? Maybe an article on what to look for or when they can genuinely add value?