

Join the mailing list!
After every single Rebel Finance School session in 2025, Katie and I sat down and wrote notes about what we could improve for next time.
We had a lot of ideas.
But here’s the thing we’ve learned the hard way over the years: our ideas are not as important as what actually works for real people, for you.
So instead of trusting our instincts alone, we went back to the data. More than 1,700 Rebels filled out the feedback form after the course.
What if the difference between feeling lost with money and feeling calm, confident and in control was not intelligence, income or willpower, but clarity, structure and one or two simple actions done consistently?
That is what this data shows.
The 1,700 feedback forms didn’t just tell us whether you liked the course or not, but what actually helped you move from confusion to confidence, from fear to action, and from “I’ve got no clue” to “I can do this.”
This article is our attempt to reflect back what actually happened inside RFS 2025, what worked brilliantly, what surprised us, what the data tells us really helps people change their finances, and what we’re now thinking about as we make it even better for 2026.
With less than two months until we run Rebel Finance School again, this felt like the perfect moment to stop, listen properly, and share what you taught us.
The headline results
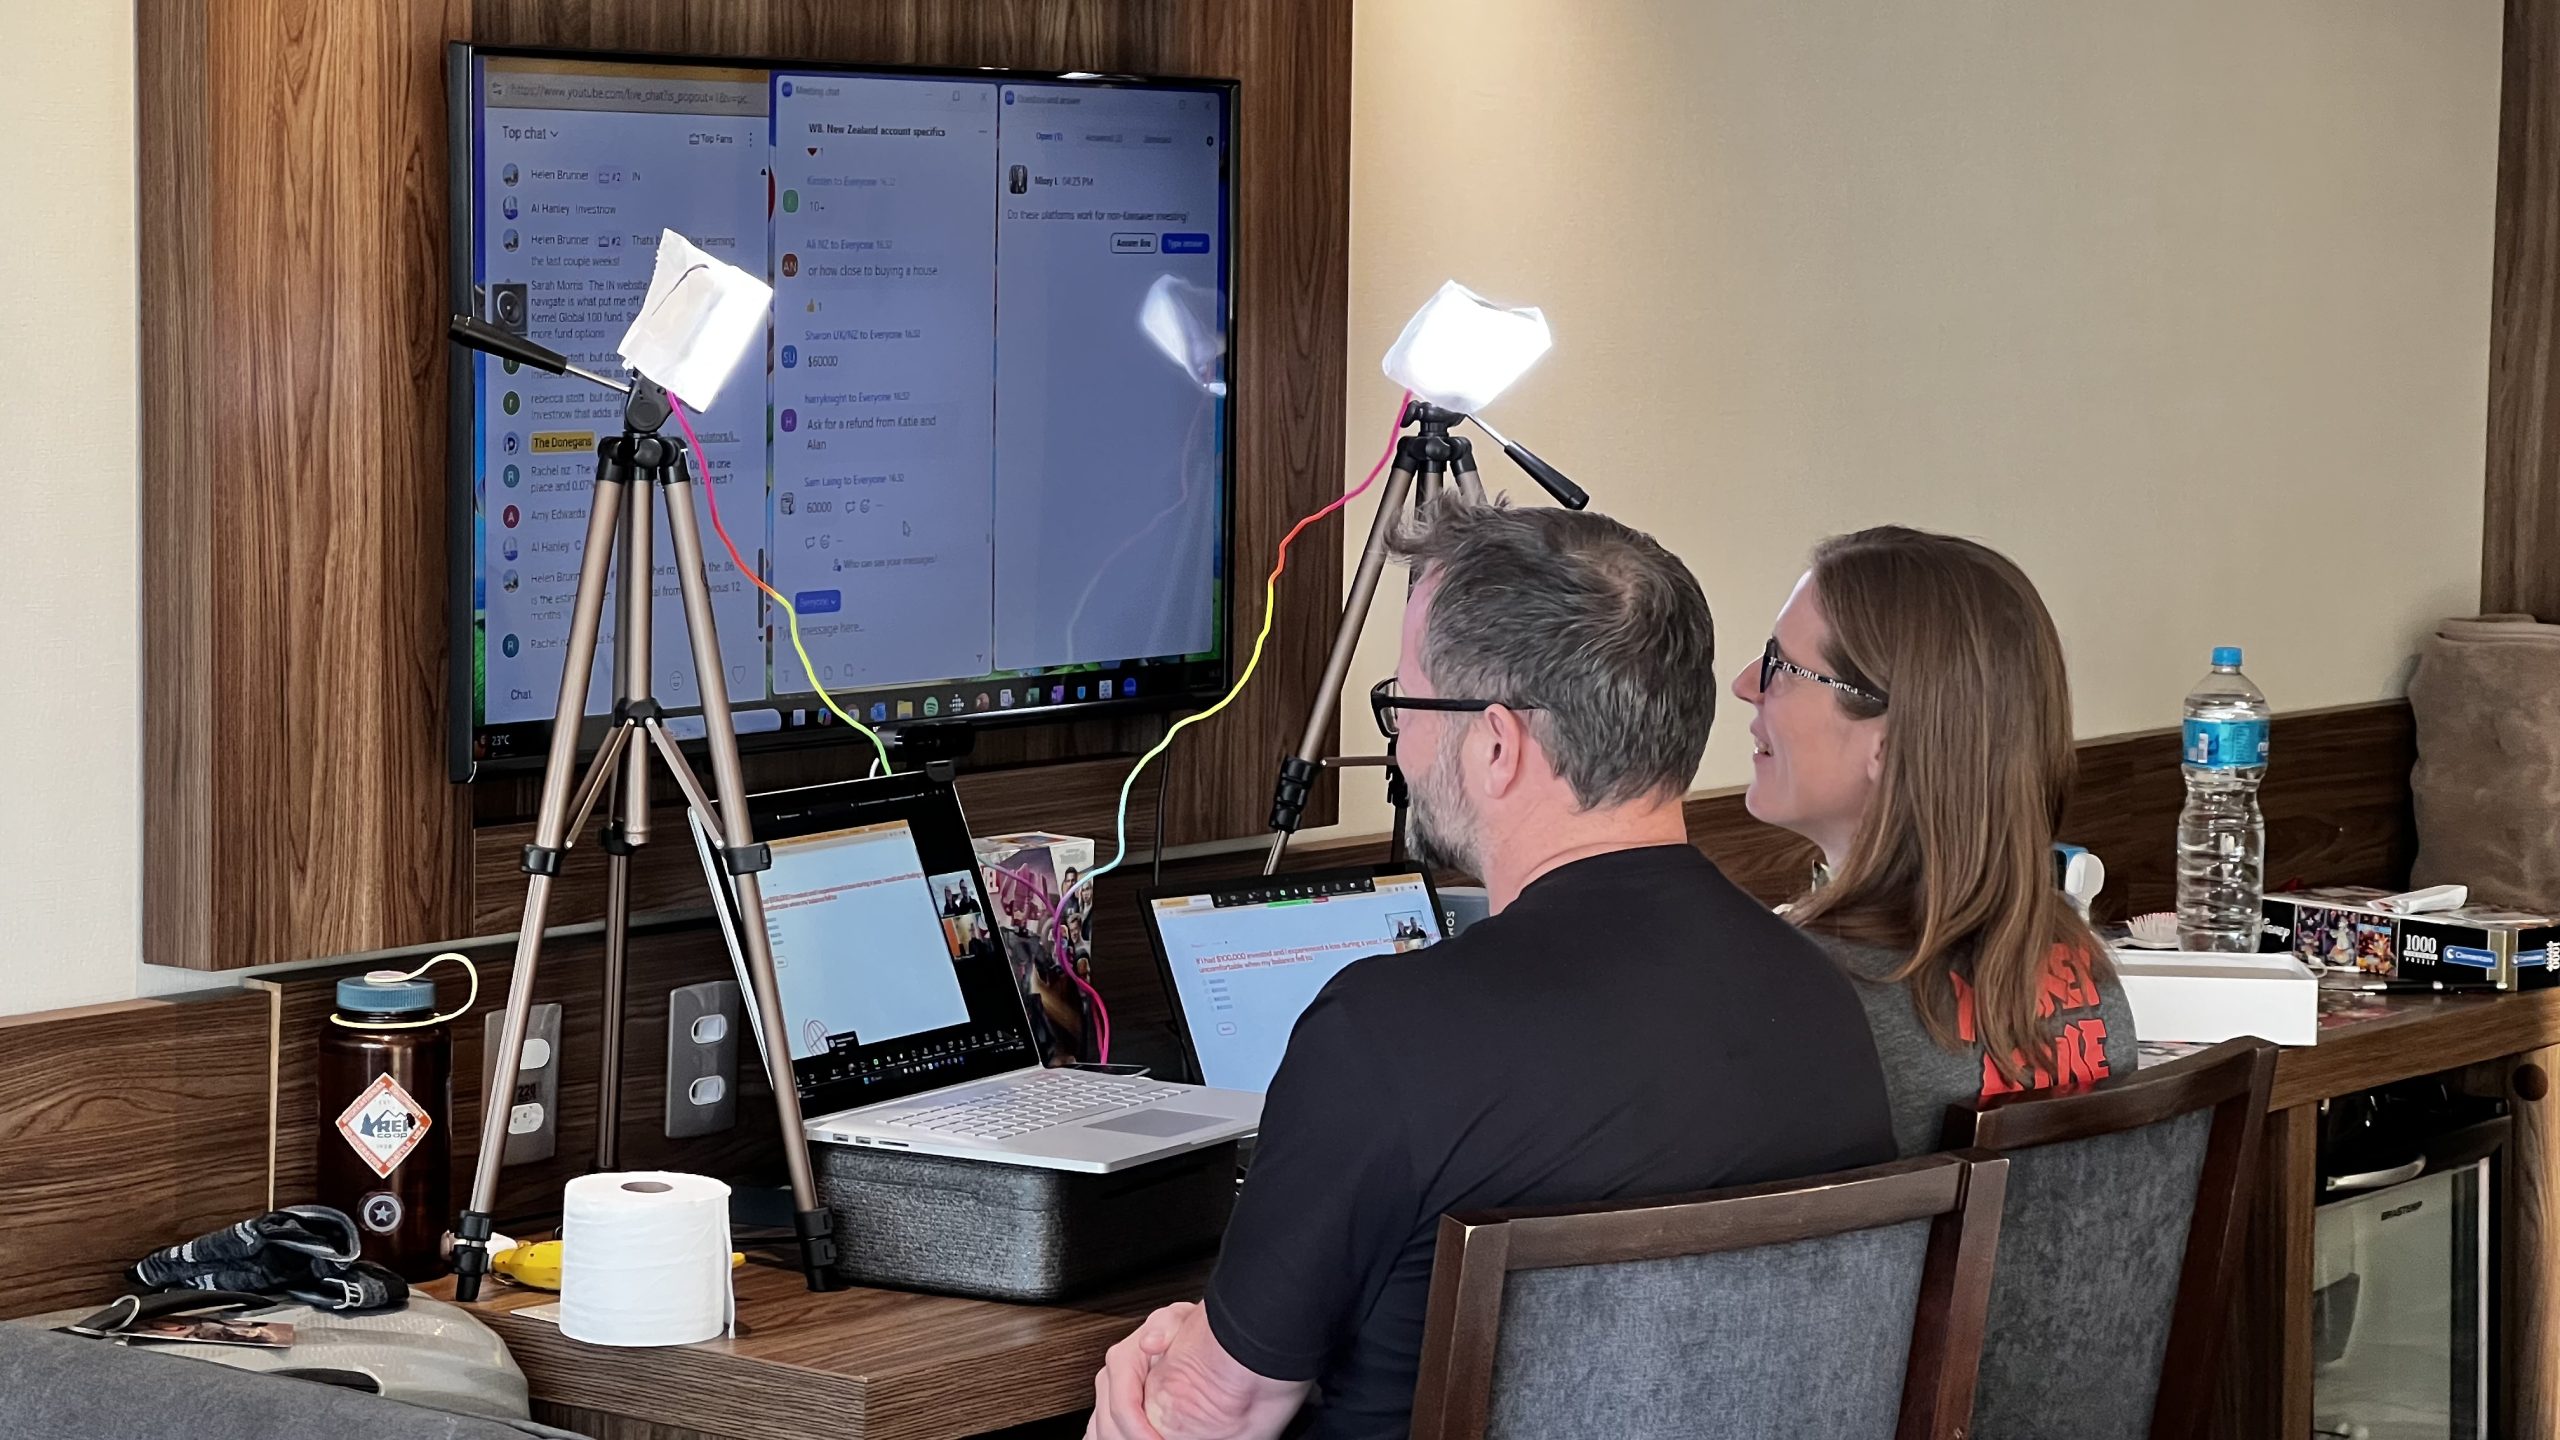
The Donegans running Rebel Finance School 2025 from their hotel in Brazil.
The short version? Rebel Finance School 2025 worked.
- Average self‑rated financial knowledge increased from 4.4/10 before the course to 8.4/10 afterwards.
- Average sense of control over money increased from 6.0/10 to 8.7/10.
- 98% of respondents said they got what they wanted from the course.
- The average life‑impact score of Rebel Finance School was 8.8 out of 10.
We are over the moon with those numbers. The headlines prove that RFS works, helps make a difference in your life and gives you control over your finances!
But the really interesting bit is not that the scores went up. It is why they went up. And that matters whether you joined RFS or not, so read on for what actually changes people’s financial behaviour.
There is another result that really inspired us: at the start of the course, a large proportion of people described their financial position as “no clue”.
By the end of the course, that category had almost disappeared. Not because everyone suddenly became wealthy.
But because clarity replaced confusion. And clarity is the foundation of every good financial decision.
Read on and you’ll see what actually helped people change their finances, what kept getting in the way, what surprised us most, and ideas you can implement in your own life. If it worked for 1700+ people the chances are it will probably work for you too!
Top 5 lessons from 1,700+ Rebels
We went back through the feedback to find the patterns that mattered most. Here is what actually helped people move from confusion to confidence.
Clear beats clever
People made more progress when money was explained simply and clearly. Complexity does not build confidence. Clarity does.
Investing unlocked the biggest breakthroughs
For many Rebels, this was the moment fear turned into action. Once investing finally made sense, momentum followed.
Confidence matters almost as much as knowledge
This was not just about learning facts. It was about feeling calmer, more capable and more in control.
Beginners are not too late
The people who started with the least confidence often improved the most. Starting from scratch is not a weakness. It is a starting point.
Small actions compound
The people who engaged with the homework and followed the structure tended to get more out of the course. You do not need perfect action. You need repeated action.
Who came to Rebel Finance School?
- demographic data from 1,700+ RFS 2025 feedback responses, and
- YouTube audience data from the last 12 months. This reflects a much broader slice of people engaging with our work before, during, and after the course.
Age:
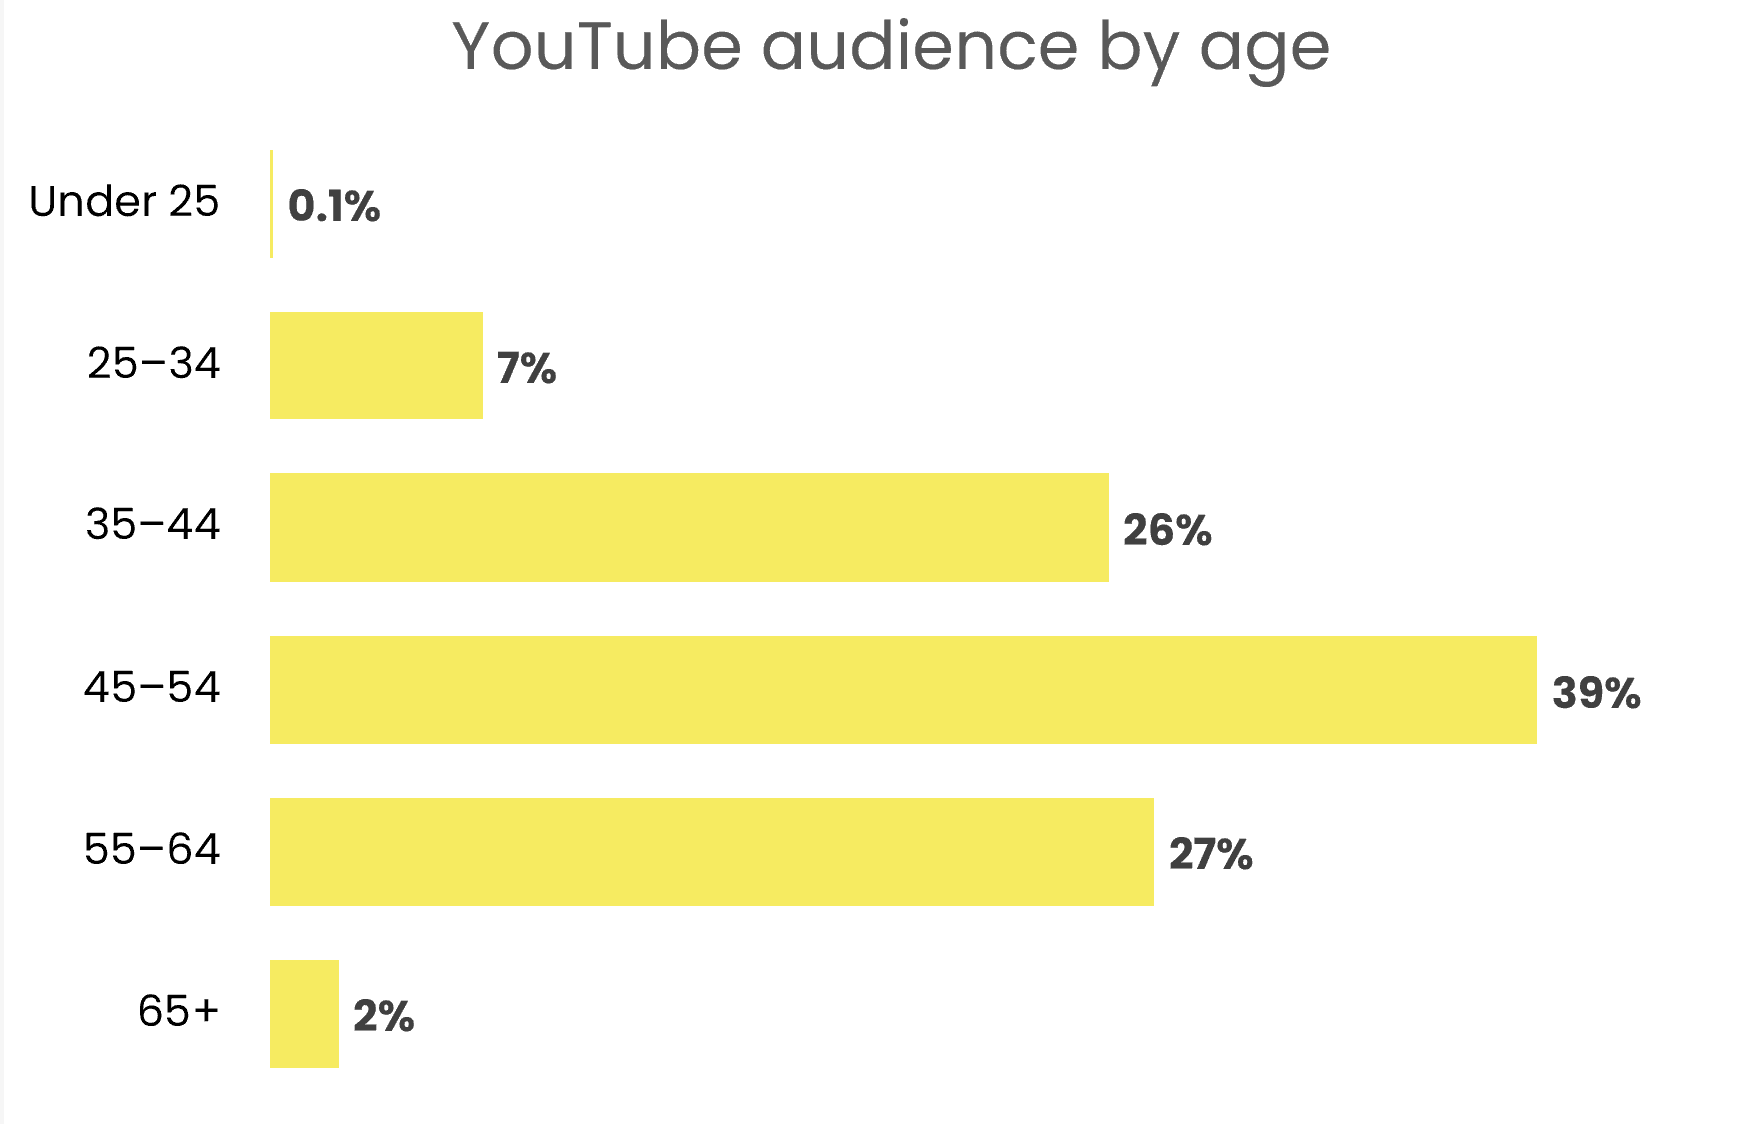
Our theory is that as people start to move towards retirement they suddenly “wake up” to the fact that they need to get their finances in order. The younger audience has not yet had enough financial pain to know they need to sort out their money.
The course still works for the younger audience with 3,522 25-34 years olds attending the course this year alone. That is a huge number of younger people!
Not only did they attend but they saw massive progress with 18-24 year olds telling us their financial knowledge increased by the biggest movement from 3/10 to 8.5/10. not only did their knowledge go up but their sense of confidence increased dramatically from 4/10 to 8.25/10.
Katie and I are buzzing from these results. This suggests that when people learn these ideas early, the impact can be both immediate and substantial.
Not only that but across the whole cohort:
The people who started with the lowest confidence saw the biggest improvements.
What the audience data tells us:
Across both the YouTube audience and the feedback data, Rebel Finance School is mainly serving people in mid-life.
That tells us that people do not wake up thinking about financial freedom at 18. They wake up when retirement starts to feel real, when time starts to matter more, or when they realise they do not want to work forever. If that is you, I would LOVE you to know you aren’t late, you are very normal.
Katie and I are the weirdos for starting to work on our finances at a “young” age. We obviously would like to create more weirdos like us in the future, but if you think you are starting late then know that is normal.
Gender: The Course Is Reaching the People Who’ve Been Underserved
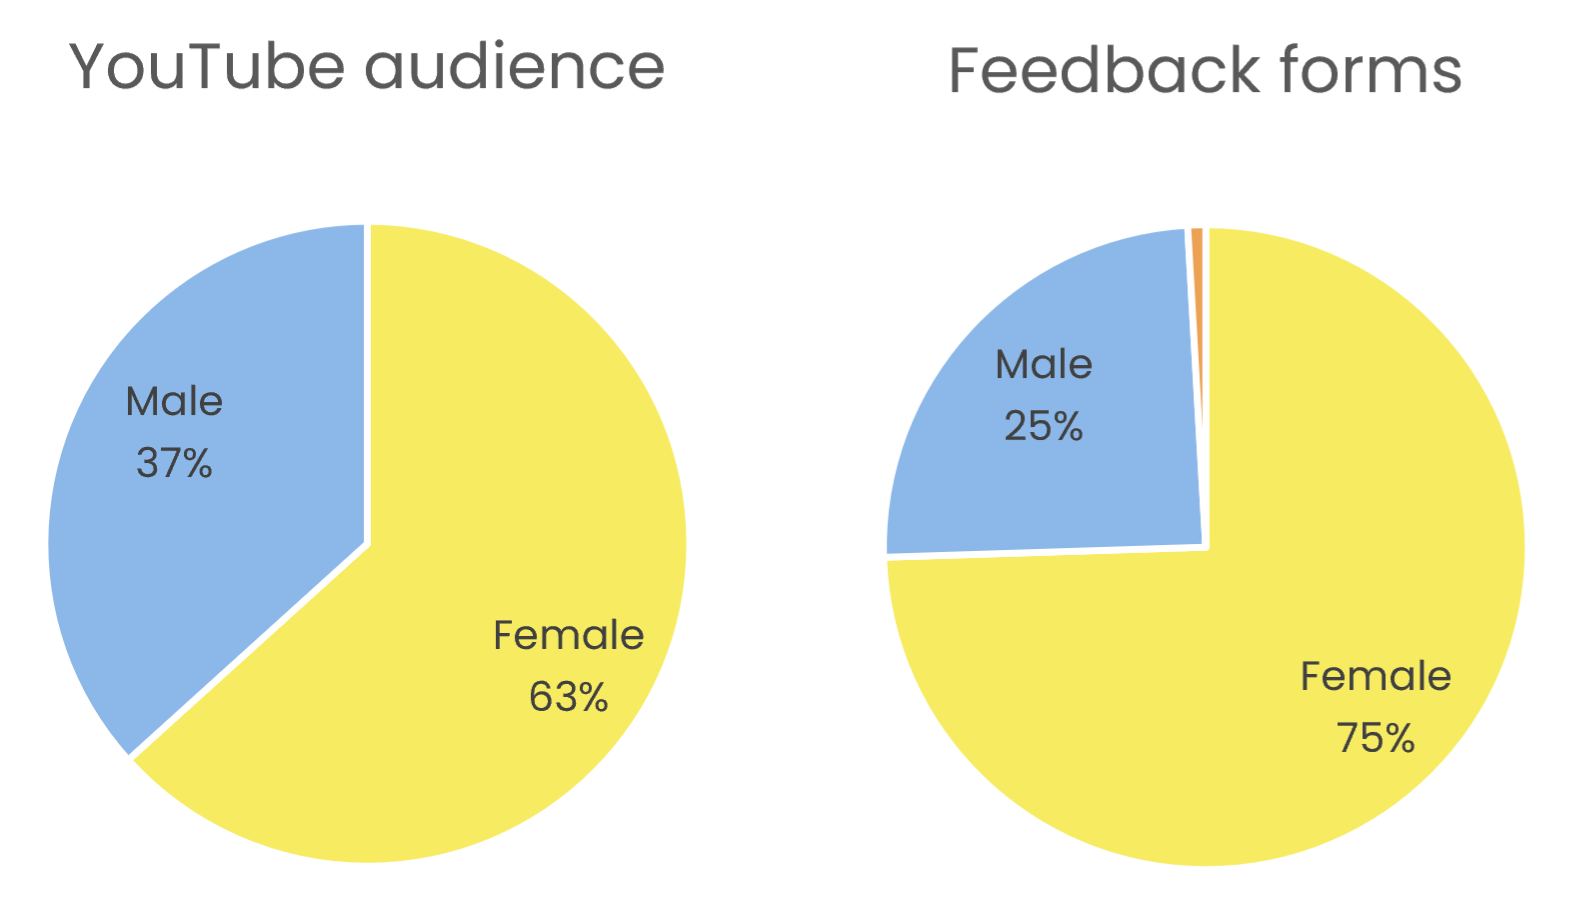
The written feedback repeatedly mentioned that many of you have felt excluded, patronised, or overwhelmed by traditional financial education before finding RFS.
The course is doing what we hoped: creating a space where people who’ve historically been under-served by financial education can actually thrive.
We know that we need to continue to develop and maintain a non-judgemental space where it is safe to ask any questions without feeling dumb for asking.
Geography: UK‑Led, Globally Relevant
- United Kingdom: 82%
- New Zealand: 5% (Go on the Kiwis!)
- United States: 4%
- Australia: 1%
- Spain and others: small but growing
And the RFS feedback data mirrors this.
- The course is clearly resonating with a UK audience.
- The underlying principles are translating internationally, even where systems differ.
We are super proud of the New Zealand and USA sessions we added into week 8 this year dealing with the different tax and investing systems! Shout out to Ruth The Happy Saver and Bob Haines for their amazing work and giving up their time to run and develop those sessions with us.
How do you watch RFS?
YouTube viewing devices
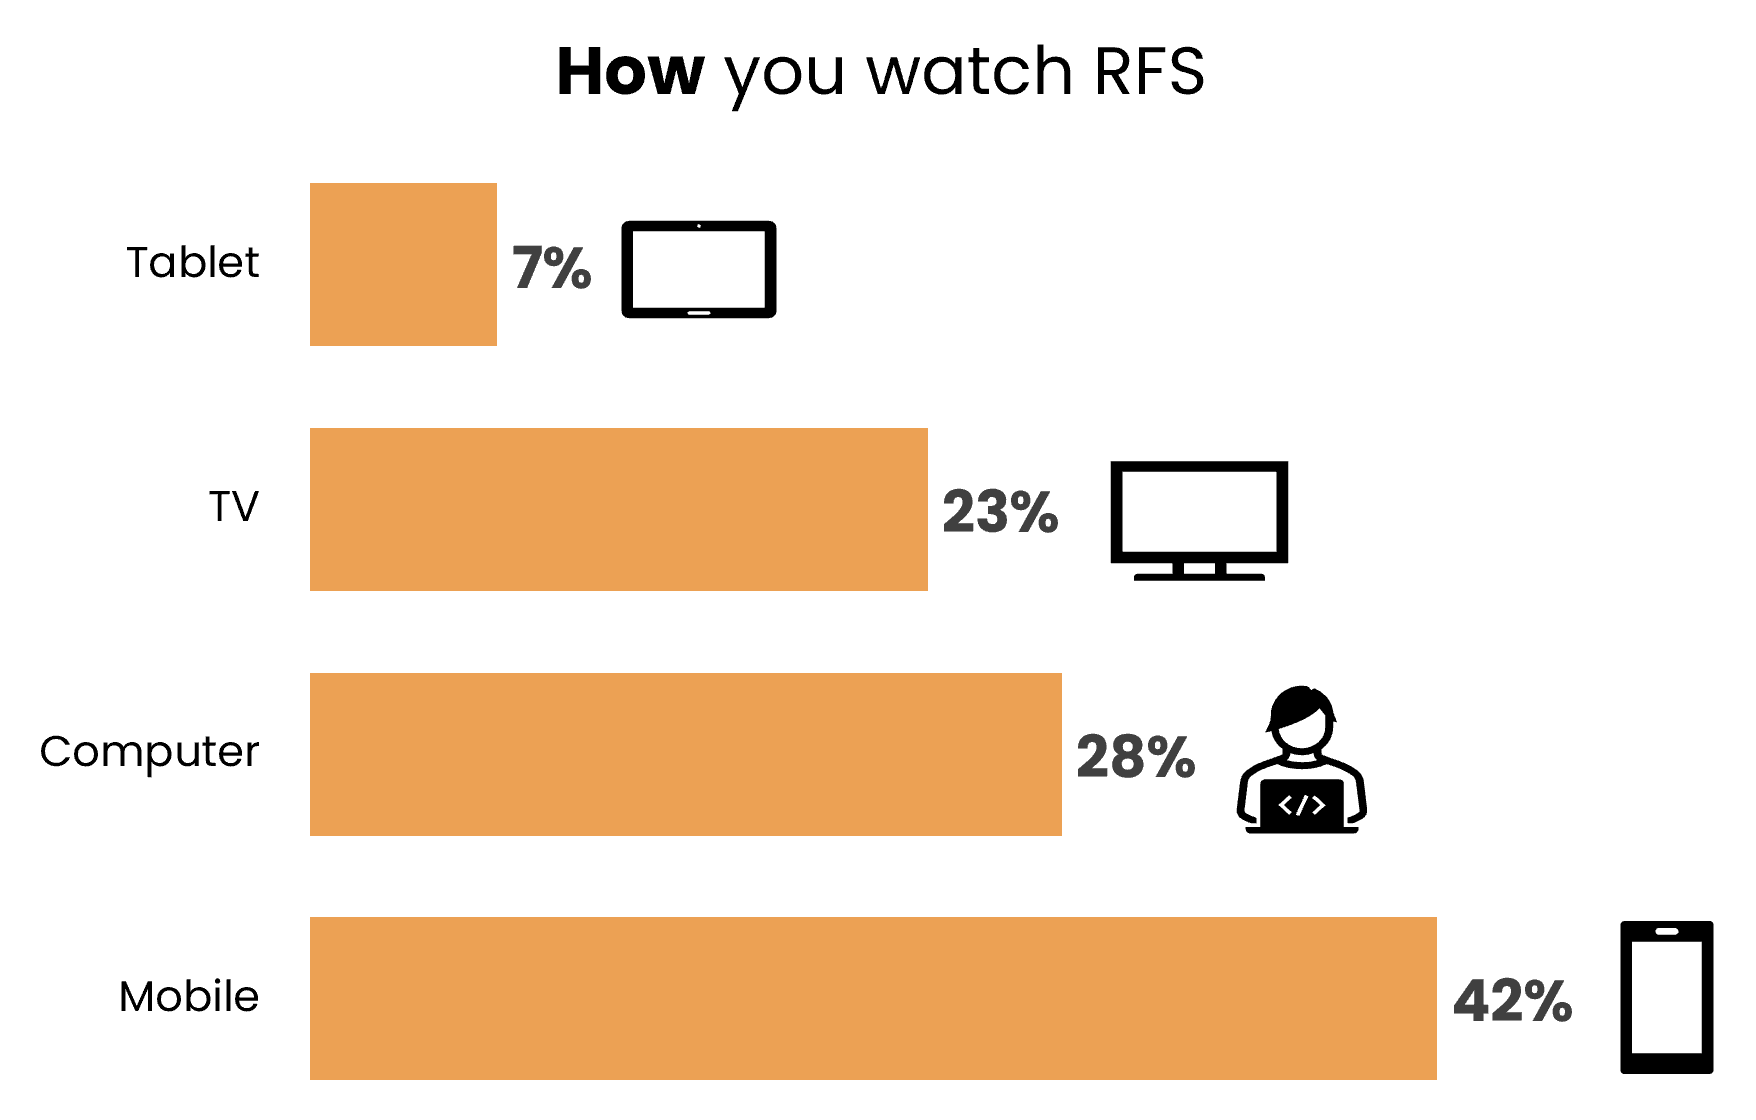
- watching on phones between life admin
- listening while cooking or walking
- having watch parties at home with their family
- fitting this into real lives
This one in particular reminds Katie and I to work to make the visuals for the course work on mobile as well as larger screens.
Prior Financial Independence knowledge (before the course)
- 32% had never heard of Financial Independence
- 29% knew a little but hadn’t acted
- 23% had heard of FI but never applied it
- 12% described themselves as well‑read
- 4% considered themselves “FI geeks”
In other words, roughly 60% of people were beginners.
Our goal was to reach the people that had never taken steps to sort out their personal finances. We wanted this course to be accessible to anyone.
The fact that 60% of people who come are beginners warms our hearts and tells us we are reaching the people that need this education the most!
It works for people starting from zero.
And the data backs this up. Those who started with the least knowledge saw the largest improvements by the end!
How many people came to RFS?
This one took us a while to crunch the numbers from the Zoom stats, YouTube Live and YouTube catch up data to work it all out. We also had to make sure that the data was not skewed by the YouTube Algorithm and how they send people to watch the course on opening day.
Here is the final count for 2025…. Drum roll please!
The median number of people that watched and engaged in each week of the course in 2025 was…
50,392 people
Katie and I are still blown away by this. A free course, that loses money every year with no marketing budget at all helped over 50,000 people to improve their financial situation!
Holy Moly!
Obviously at this point Katie got excited and created some charts to show you the data. We have two charts. Firstly this is YouTube data showing how the number of channel views in total has grown over the years.
We are pumped to see the channel grow and to engage more people, but it is at this point our critics come in and tell us that we are only doing this for the YouTube income.
We are doing the final figures at the moment for the finances of RFS 2025 but the money we made on YouTube from advertising didn’t cover the expenses. RFS is currently a lose making venture. I would love that to turn around at some point but at the moment this is our donation, our volunteering, our gift to the world.
If I was doing this to make money there are so many better ways to make money than this for less effort!
Here is the second chat Katie has been working on which shows YouTube views by week and year over time. Each line shows a year and it builds!
You can see how the livestreams each week increase engagement and get people moving through the course content with us. You can also see the growth year on year of the course as we reach new people.
Katie and I are so proud of what we and the Ninjas have achieved. Thank you for helping us spread the word of RFS!
What worked really well
1. Clarity beats complexity — and the data backs that up
- clear
- simple
- easy to understand
In other words: this wasn’t just “nice feedback”. It showed us that breaking down personal finance into clear and understandable terms helps people to really “get it”
“I’ve tried to learn this stuff before and always felt stupid. This is the first time it actually made sense.”
“You explained investing in a way my brain could finally understand.”
The Finance industry uses confusing terms and complex language that often leaves people more confused after the interaction than before. Katie and I have long hypothesised that this complexity is used to justify high fees.
Our aim is to help you understand the decisions you are making, why you are making them and be able to have a conversation with anyone about your personal finances.
What this means for you:
If money feels confusing, do not assume you are bad at money. It usually means it has been explained badly. Stop consuming clever finance content that makes you feel thick.
Find one clear explanation, one simple tool, and one next step. That is how you make progress. The people who did the homework each week saw more progress than those who didn’t. Funny that!
2. Investing was the single biggest lever for change
- “I’ll mess this up.”
- “This is for other people.”
- “I’m too late.”
- “I don’t have enough to start.”
- starting or simplifying their investments
- using ISAs and pensions properly
- choosing simple index funds
- actually taking action instead of endlessly researching
“I’ve been frozen around investing for years. I’ve opened my first account this week. That feels massive.”
It feels massive to us too!
Statistically, this matters because people who reported taking even one concrete investing action also reported higher gains in confidence, not just knowledge. Doing beats knowing.
This has inspired Katie and I to think about how we can make the course even more practical and easier to take action on. Read on for some ideas of how we might do that….
What this means to you:
If you have been avoiding investing, this is probably the thing to face next. It was the biggest breakthrough for loads of people. So stop circling it. Learn the basics, open the right account, and take one small action.
Once you have learnt index investing it is surprisingly simple to do.
3. Confidence moved almost as much as knowledge
Knowledge went up a lot. And control went up too.
Knowledge is great but completely useless if not applied. Knowing about an index fund is completely useless if you don’t open a tax advantage account and stick some money into it.
Control to us represents the power to be able to use money as you want to. You can control it. It doesn’t just disappear every single month on sausage rolls! You can take some of it and use it to build long term wealth through investing. That is the goal.
Knowledge is lovely. Control, action, implementation is where the real progress is made.
Across the cohort, people consistently reported feeling:
- calmer
- less ashamed
- more capable
- more confident talking about money
- less overwhelmed by decisions
“For the first time in my adult life, I don’t feel stupid or behind when I think about money.”
This is not just about learning facts. It is about feeling calm enough to act. If money still makes you freeze, your next step is not “learn everything”. It is make it feel safer, simpler and more doable.
Here is a picture of Katie comparing pineapples as light entertainment between text. Enjoy the rest of the article…
4. Beginners and late starters benefitted the most
One of the clearest statistical patterns in the data was this: people who started with the lowest confidence and knowledge showed the largest improvements.
Which means Rebel Finance School is not just for people who already “get it”. It’s especially powerful for people who feel late, behind, or unsure.
As one Rebel put it:
“I wish I’d learned this 20 years ago — but I’m so grateful I’ve learned it now.”
We all wish we had found this stuff sooner.
One of the things we are most proud of is that Rebel Finance School starts at the beginning. We do get some complaints that the early weeks feel obvious, but we designed the course that way on purpose. No matter your starting point, you need solid foundations, and the data shows that approach works. It helps everyone, and beginners often improve the most.
We have tried jumping in at investing before. It sounds exciting, but it creates problems. People who think investing is not for them switch off. People who do not think they have enough money to invest feel left behind. And some people start investing before they understand their gap, their emergency fund or the basics of how all this fits together.
We learned this very early on.
On one of our first ever coaching calls, a couple told us they wanted to talk about investing, so that is where we started. Right at the end, Katie asked, “Do you have any debt?”
They said, “Just the normal amount.”
We looked at each other and thought, “What is the normal amount of debt?”
It turned out they had £50,000 of high‑interest debt. In that situation, investing was not the answer. Trying to earn 10% while debt is compounding against you at 25% is not a smart place to start.
The first step was getting out of debt.
That is why we begin where we do. We cannot assume people already know the basics. We have to help people work out where they are, take control, build strong foundations and then move on to investing from a much safer place.
And even when people are very confident, we still often find gaps in the basics.
Our aim is simple: teach personal finances from the very beginning and leave no human behind.
What this means to you
If you feel behind, good news. This course works for everyone, and beginners often improved the most. So do not waste energy feeling embarrassed. Start where you are and take the first step.
5. Structure matters more than motivation
- YouTube views – this is warped by driven through YouTube’s algorithm and watching for a few seconds and then dropping off. This gives week 1 of the course a huge number of views but not all of them are meaningful.
- Feedback forms – this is super useful but has what is known as survivorship bias. Only the people who made it to the end of the course filled it out and therefore are more likely to have attended the entire course.
What the data taught us about real behaviour change
- higher confidence gains
- higher control scores
- higher reported impact
Where people struggled (and why that’s useful information)
We asked : “What’s your biggest challenge moving forwards? What might stop you?” in the feedback form.
Because this was a written-answer question, people could tell us what was really going on for them, in their own words.
And the same themes came up again and again. When we grouped those answers into themes, the biggest ones were:
- fear of making a mistake at around 20%
- tax and pensions confusion at around 13%
- lack of time at around 10%
- overwhelm / not knowing where to start at around 8%
Where we can improve RFS
1. Tax and pensions still feel intimidating
- more clarity
- more examples
- more practical explanation
2. Overwhelm, not difficulty, is the blocker
- “There’s a lot.”
- “I’m not sure what to do first.”
- “I need help prioritising.”
That is a really useful distinction.
The problem is not that people cannot understand the material. The problem is that when everything feels important, it is hard to know what to do next
That gives us a very clear job for RFS 2026. We need to make the course easier to implement, easier to follow, and clearer on what to do first.
Katie and I talk a lot about the fine line between education and financial advice. We do not want to tell people what to do. We want to help people understand their options, make good decisions, and feel confident in the choices they make for themselves.
So the challenge for us is this: how do we reduce overwhelm, give clearer guidance, and use practical examples, without taking the thinking away from people?
That is one of the biggest design challenges for RFS’26, and one of the things we are most excited to improve.
3. People want help turning clarity into action
- lack of time
- fear of making a mistake
- uncertainty about where to start
So what does that mean for RFS 2026?
- simpler
- clearer
- and easier to act on
Thank you
If you were part of Rebel Finance School 2025, thank you. Thank you for trusting us. Thank you for your honesty in the feedback forms. We can’t make things better without hearing what worked and what didn’t work for you. Thank you for doing something brave for your future.
One message we saw over and over again was simply:
“Thank you. This has genuinely changed my life.”
At times, doing this work is tough for Katie and me. There are ups and downs. But it is messages like this that keep us going, keep us working and building. Rebel Finance School exists for one reason:
To help you take control of your finances and use money as a tool to build the life you want to live.
Thank you for reading our article about RFS 2025. If you made it this far, good work!
Katie and I would love to know what struck you from this article. What did you learn? What surprised you? What do you want us to know?
Your comments, messages and ideas are the fuel that keeps us going.
Peace and Pineapples
The Donegans
101 Comments
Leave A Comment
Related Articles

Blog, Financial Independence, Save and Invest
Where do I put my money? Hello there! We wrote this article in 2025. Platform fees in the UK have changed a lot since then! Look out for an updated article coming soon.....With such a confusing array of platforms, funds and fee structures how do you ever decide where to put your money? In [...]

Blog, Donegan Update, Keeping Track
5th Jan 2026 At the end of the year, Katie and I always get excited because this means a chance to do our annual finance review! How often do you review your finances? Do you check daily, as some people do when they first find out about investing, or are you a set it [...]

Blog, Financial Independence, Keeping Track, Save and Invest
Where is your net worth? Most people have no clue what their net worth is, let alone where it is. Your net worth is the total of what you own minus what you owe. Your split is the shape of that number. How much is in your Freedom Fund? How much is [...]

I like the fact that you review and make changes for the new courses as new information for taxes etc is updated . I am so excited to start the course . I can’t wait . Your content is what I need at age 62
Janinne, we have spend so much time understanding the feedback and working out how we can improve things. We enjoy it. We can’t get better at what we do without people’s insights. You are awesome. Thank you for your lovely messages today! Alan
Hi Alan and Katie,
I’ve only discovered the course recently and watched as much as I could on Youtube but I am really looking forward to the next course! I have also recommended it to countless friends and family.
I did think it was clear and I have opened a S&S isa for myself and a SIPP for my husband (put in 3 tiny old pensions that were hanging around). I’m still gathering details of my old pension and will put that into a SIPP too. I felt really confident doing this after watching the course. I felt ‘safe’ to open the isa with Vanguard and invest in the Global all Cap. I know we need to think for ourselves but it was so easy to have that as a starting point. What I’m not confident in, is knowing how to put my husbands pension into a fund that will grow (it’s with Standard Life). I have asked on the facebook group but I didn’t get any info… It would be so helpful to have a list of good options (offered by SL) to switch to. For me, who had absolutely no knowledge of investing, it is hard to assess the options myself. Hoping I’ll learn, and understand, more as I go!
Thank you for everything you do, I hope you know how much it is appreciated by so many!
Kathy that is SUPER useful feedback. Thank you for replying. We are planning more practical sessions this year to tackle exactly this. LOVE that. Thank you
In the mean time here are my thoughts:
1. Standard Life probably has some global index funds – can you get your husband to call them and ask what is the closest to a low cost global tracker fund or etf?
2. This might help with reading the fund fact sheets? https://www.youtube.com/watch?v=Cyy1dIYfLAo tell us what you think
3. What are the fees on Standard life he is paying? This will tell you a HUGE amount. We want to get those fees down, but if they are already down he might be in a good fund?
4. What is the past performance compared to the FTSE Global All Cap? That might give you an idea if he is doing well or not. Just look at the 10k invested over different time frames to get an idea…
Does that give you a starting point?
Sending happiness
Alan
I loved reading the stats. My main investmentd are pension based. I really have been able to understand and accept the volatility of market bumps by checking my pension everyday during these times. At first it was scary but I could see the recovery after each bump and gave me the confidence to contine to invest and not panic. I would have NEVER done that without your course so thank you. All the work you do helped me grow my portfolio and at 58, I am semi retiring and going part time which is amazing xoxo
Hey Kathleen thanks so much for writing back. Congratulations on experiencing volatility and getting used to it. The first time is absolutely uncomfortable and I am so proud and happy that you have looked at it, learnt about it and now mastered it! Amazing work. Thank you for writing back to us and you are fab! sending happiness. Alan and Katie
LOVE the feedback spelled out so clearly. Reinforces that I’m not late or stupid but normal!!! From shame of inaction to learning to invest, this course has been invaluable. Will redo in 2026 & look forward to it very much, especially the silly photos ;0). Keep up the great work K&A. M
Moira, you are amazing. We loved meeting and hanging out with you. Thanks for comenting. love Alan and Katie
I’ve been watching for 12 months now. I’ve gone from being a good saver to a considered investor, I’ve hammered compound calcualtors having never even known what compounding was, been scared witless with my first investment last year to confidently doing Bed and ISA on 6th April this year and setting up a JSIPP for my 3 year old grandson. Every time I get stuck, I review the videos or ask on the fb page. Honestly, it’s transformed my life and my husband who has no interest in money whatsoever now willingly engages in our monthly finance meetings. I love that every year the course is refined and gets better. Thank you both – and of course the Ninja’s.
Suzanne, this made me smile all the way through. I loved reading your comment. Thank you.
From saver to confident investor, hammering compound calculators, Bed & ISA, JSIPP for your grandson, this is epic progress. That is a massive shift, and it doesn’t happen by accident.
I also love that you’ve noticed the course evolving year on year. We put a lot of energy into refining it based on feedback exactly like this, and it’s brilliant to hear that landing.
THANK YOU for writing back to us. it means a lot.
Peace and pineapples
Alan & Katie
Thank you both so much! I am your biggest cheerleader and tell EVERYONE about the course. I love that you are also working to make it an even more positive and helpful course, thank you both so much.
Emily, thanks for writing back You are awesome and thank you so much for telling people! we don’t have a marketing budget so your help means so much! Sending love! A&K
Thank you. Donegan’s. Really interesting.
I believe understanding how to build personal wealth for yourself, family and future generations will help with Social Mobility. Helping those from low socioeconomic backgrounds (disadvantaged / working and non working class) live a more fulfilling life.
I would be interested to see diversity data on RFS reach across various SEBs. See social mobility commission for more details. Perhaps you feedback forms could ask questions on SEB diversity. Wealth should no longer be for the rich.
I work within Social Mobility – and have recommended RFS. Love it!!
Michelle, thank you for this — it really matters.
We completely agree that understanding money is a huge lever for social mobility. When people can see how money works, it unlocks options that previously felt closed off. That is one of the things we want to change because we want everyone to be in control of their own financial destiny and understand the choices that they are making. It is SO important.
We love that you’re recommending Rebel Finance School. THANK YOU. We don’t have a marketing budget so need all the help we can get.
Your point about understanding who we’re reaching (and who we’re not yet reaching) is also a really important one, and something we actively think about as the course evolves. We haven’t done the SEB diversity questions, we have just kept it simple till now. Do you work in this area? Do you understand the questions?
I am interested in this as I would LOVE to prove that we help with social mobility and show it works. We can show it works for beginners and helps them and we have some great evidence so far….
Tell us more…
Peace and Pineapples.
Alan & Katie
Well done, great course and structure. Life changing for most people.
Thanks Maggie! Appreciate it! Sending happiness. Alan
I found the course absolutely amazing, and it’s really helped me get all my ducks lined up ready for our retirement in the next few years. Sooner than I thought that’s for sure!
As an ex teacher, I agree clarity and keeping things as simple as possible is key. I often gave my students a simple one page checklist / instructions / flowchart to explain a topic or problem. Could this be something you can develop? It might give people that initial starting point to follow through. It would probably follow the weeks of the course structure, which is logical.
Thanks again for all the time and effort you put in to help us mere mortals. I’ve signed up for 2026 to run through it for a second time!
Carol Ann, thank you — and I LOVE the ex‑teacher lens on this.
One‑page clarity, checklists, flowcharts… YES. When emotions are involved, simple beats clever every time. People don’t need more information — they need a calm, clear starting point.
Want to help us develop it? I would LOVE LOVE LOVE to give that away to everyone and a flow through all the content. So many ideas and so little time to do them all!
So glad you’re joining us again — second time round is when it really sinks in. Sending happiness and Love
Alan & Katie
Reading your overview of the feedback made me feel quite emotional, as it’s clear how much you care about your course and the people following it. I think it’s really interesting, that finance and numbers feel as if they should only involve the head, but emotions are very much in the mix too – and having taken on board what I have learnt from you and used my head to sort out my finances, my heart feel happy as well!
Thank you to you and the Ninjas, and I am looking forward eagerly to the 2026 course!
Laura, what a fabulous message to get. Yes we get emotional with it too seeing the impact, thinking about what we can do differently. Defending it all from different things! I am so glad it helped you and thank you for writing. it means a LOT! alan and katie
I am in awe of the effort you put into this course, review of course and provision for free.
I am one of the late starters due to divorce and life circumstances with a touch of head burying through lack of education while being a bookkeeper!
You have given me the tools and confidence to go hell for leather trying to pull a pot together to equal state pension in the nxt 12 years. So I can be somewhat comfortable.
Your course is changing lives i am forever grateful 🙏
Tina, what an awesome message. THANK YOU. I am so glad you are taking that on and working on your finances. Divorce and things like that can really rattle it and it takes time to recover but I am so happy you are on that path. THANK YOU for writing back. Sending you love. Katie and Alan
I just signed up for the upcoming course and am very much looking forward to it. I don’t know how many people you have from Canada, but if it’s enough to have a session like you did for the US and NZ folks, Dave Chilton (The Wealthy Barber) might be someone to look at. He’s where I’ve gotten the majority of my limited knowledge. :-)
Hey Lisa thank you so much for the message. We have been asking Kristy and Bryce from millenial revolution if they will help us with a Canadian Session. We really want to get one of those. I think if we do that it will give more value to the Canada Audience. I want to get sessions for Canada, Australia and Ireland this year added. We are working on it! THANK YOU for that and let us know how you enjoy the course. Alan
I binge-watched the 2025 course on YouTube every spare moment of the day and it was so engaging (addictive!) no wonder drop-off was minimal! I too have been recommending it left, right and centre. Life-changing for me and has given me a boost in confidence across the board, not just re finance. Thank you guys so much, looking forward following the new course live.
Helen, you are amazing. THANK YOU. We really appreciate you writing. It was so much fun to run it last year and we have so many improvements we are making for this year. It is going to be fnu fun fun! See you soon. A&K
Great article. You’ve probably considered this already but what about offering a mentoring program for the implementation piece – more expetienced volunteers who agree a plan with a mentee and help them by checking in say weekly post course to track progress and offer support.
Hey Steve, we would LOVE to do this. I think what has stopped us is the work to do it and set it up and manage it all. That is our sticking point. There are plenty of people who I am sure would volunteer to help others on the implementation. It is just bringing together that as a programme and managing it. You are right, it is a great idea and would add value! Alan
Hi Alan & Katie, I stumbled across the RFS Facebook group last year after the course ended. Raced through all of the vids on YouTube and enjoyed enormously. Luckily, I have been investing since my 20s as my first boss was a real advocate of saving for early retirement. I worked in financial services technology for 30 years so fully conversant with investment terminology. Have signed up for the 2026 course as I’m sure there is more I can learn, particularly regarding drawdown which I will probably start in 4-5 years time. I am enjoying being a member of the Facebook group and try to help answer people’s questions – which leads me, finally, to my feedback. One of the most frequent questions I see is people not knowing what their pension funds are invested in. With very few exceptions, the information they need is extremely easy to find on the internet with a simple search as virtually everything is online. So, perhaps it would be useful if you could cover how to search for information on pension funds for the people that already have a company pension so they can make an objective decision on whether the fund makes sense and how to identify the best passive global index fund offered by their pension provider. Oh, and you definitely need to update your comparisons for ISA and SIPP providers as the landscape has changed dramatically since last year..!
Chaz you are amazing. Thanks for the feedback and wow having a boss that tells you to save and invest at a young age is AWESOME. Love that.
Plus your feedback here is amazingly helpful. Love this. And you are right. I have copied out your comment and put it in my ideas tab to go through with Katie and work on that. That is genius. We are planning some new sessions this year and I think this will fit right in and will be super valuable for people.
Yes we need to update the platform review. Cheeky ask, want to help us do it!?? lol! Thanks for commenting. We really appreciate it.
Hi Alan,
Not a cheeky ask at all… would be happy to give something back and help with a platform review..👍
Just tell me what you need.
Chaz…
will email! you are amazing!
Loved the course. Watched the recorded episodes on YouTube and can’t wait for the 2026 course! Do we need to register for it? Or will we get all the info automatically through your regular emails? Love and Pineapples! xx
Carrie you are amazing. Sign up page is here: https://rebeldonegans.com/finance/rfs/ And love that you signed off Peace and Pineapples. That made our day! A&K!
I’m keen to know how the interaction with the course notes was? Number of people watching and going through notes, heat map of notes – did they read all the notes or flit around and just get links?
What was attendance at bonus sessions vs course sessions like?
That is a really good question Samantha, We have google analytics so I could find some of the data you talked about for the course. I have spend the last week working on the course notes home page and completely updating it for this year. That is a HUGE project. I did ask a while ago, is anyone using the notes (I had spend 2 days on them and had doubt) and we got a huge positive response but I could be more data driven about this. Great idea to pull it in. What made you ask those questions? Sending happiness. Alan and katie
Great article! Did the course crash-style while on holiday in Bali, trying to beat the clock before it was taken down in 2025. Did the course again in real time later in 2025 and loved it even more! At aged 62, and going through significant changes in life situation last year, this was extremely helpful to give me clarity and reassurance that my financial situation was actually ok, and to not feel so panicked.
One small suggestion for the NZ section this year: InvestNow TWF seems to be the main platform people here choose to invest in (me included) However there has been some discussion lately about tax leakage and maybe we should be questioning this choice. It would be great if you (or Ruth) could discuss and clarify what this actually means, and how to analyse options taking tax leakage into account.
Looking forward to the 2026.. Off to register now!
Lisa love the post and comment. Have copied your blog comment into my notes to discuss with Ruth and make that happen. Tax leakage doesn’t sound fun but I will work that out and get back to you. We will cover it this year. THANK YOU.
I am so glad the course helped and how cool you got to do it live with us last year! Early mornings in New Zealand!
Sending you happiness and love. Alan and Katie
Loved the course, have spoken so much to friends and family about it. Messages were clear, concise and relatively easy to implement. I loved the non judgement and fun factor. Wish I knew about your course years ago. Huge, huge thanks to you both for this gift of your time and expertise. You are amazing and inspiring. Wahoo!! Go kiwis! 🇳🇿
Trudy! GO THE KIWIS! lol. Thank you so much for your wonderful message. We had so much fun running it last year! gonna work to make it even better this year. We will be over your way later this year. Hope to see you at a meetup somewhere! Peace and Pineapples. Alan and Katie
Chat GPT mentioned this course about 8 weeks ago and putting it simply it has changed everything. Even at 59, I know I can make a difference in my finances but I’m doing this for my children, so they can learn and understand the value of investing and financial freedom.
I cant wait to do the course and a very big Thank you.
Brett, that is AMAZING that chatGPT recommended the course. wow. I haven’t heard of that happening before but it is amazing and makes me so happy. The content of the course changed our lives too! Thank you so much for writing back and telling us. it is so lovely to read your comment. peace and pineapples. Katie and Alan
Alan and Katie, I loved reading this article and I can’t imagine the amount of work and thought you’re putting in RFS 2026, and have so far. You are awesome!
Sevy thanks for commenting. It means a lot! Alan
I was waiting at hospital . My wife was having a shoulder operation. It was a long day. I was scrolling Facebook when i stumbled upon RFS( Which i had heard of) . I decided to have a look as i had the time. It really hit home to me. The presentation was very engaging. I had two pensions and a cash isa. I tranferred one pension to a vanguard sipp and also my isa to a vanguard s&s isa. I could open a gia but i just can’t get my head around how to work it with the self assessment return. I seem to have a blind spot here which makes me feel a bit thick lol , how hard can it be though. But keep up the good work, it’s very enlightening and much appreciated
Hey Gary, is your wife ok?
So glad you found the course and amazing that you took all that action. Thanks for the feedback on the GIA stuff and we know we need to do a better job of that this year and are planning a better sessions on that. It is not that easy to do so makes sense. We will do a version to help you! Thanks for commenting and you are awesome! sending happiness. Alan
We are about to retire at age 64 and 65 – we are moving back from the US to the UK and have cash and a mortgage free property in the UK and a good RN pension but I keep feeling we are too late to start putting money into investment accounts as we will now be using the money in retirement. We have no ISA’s no nothing, just a not very high interest savings ac. Is it too late for us ?
Louise, thank you so much for writing this and for sharing where you are with all this.
This is such a common feeling, especially around retirement, and I want to say this clearly: no, it’s not too late. Not at all. This isn’t an “all or nothing” thing, and retirement doesn’t suddenly mean everything has to sit in cash forever. Katie would be screaming “IT’S NOT BINARY!”
The magic is understanding what money is actually for now, what’s for later, and not letting fear quietly make the decisions for you. That clarity is what changes everything. I would suggest coming on the course in June. You can sign up here https://rebeldonegans.com/finance/rfs/ , completely free and working through it and then let’s work out if your money needs to be invested and how we can get it working for you.
We need to get your cash working for you. This article will explain why: https://rebeldonegans.com/finance/investing/cash/
It is not too late at all and you can 100% improve your situation. Are you able to do the course with your husband?
Peace and pineapples
Alan & Katie
I dipped in and out of 2025 as felt some info whilst educational wasn’t always relevant. Personally I have retired but don’t yet receive my pension, I have a private pension but not yet drawn down any – living off savings but not very wise ie best tax efficient way I’ve been told! I got so overwhelmed I didn’t know the best most effective way to use pension and savings! So I’d like more information on what to do with this in betweener stage of life!! Pension is also with you know who – but overwhelmed and scared to move it!!
Hey Lee, thanks for your message. What stopped you from moving away form those that can not be named? It would help me to understand what question you are trying to answer?
And the course is designed to start from the very beginning so isn’t all going to be relevant to everyone depending on your starting point. Help me to understand what exactly you are trying to solve. Sending you happiness and thank you for writing. Alan
We discovered RFS just over a year ago 😅 After watching the 2024 course in Feb 25 we had food for thought 🧐
We did the 2025 course and are looking forward to 2026 and beyond. 🤩
Because of RFS we are now mortgage and debt free. We are also invested for our futures 🤩
Katie, Alan and all involved, 🙏🏻 You are changing lives – Bravo 🥰
Dennis, that is amazing. WOW. Congratulations on taking action and getting going on all this! you post made my day! THANK YOU. Congratulations! Alan and Katie
I’m a 2025 RFS Graduate and one of the females that provided feedback. ;-) Thank you for using the feedback constructively. I was most struck by the age distribution. It’s not surprising that the lion share are middle-age. I’m right there and consider myself a late starter.
I was already impressed with you, both, and sang your praises. I tell everyone that will listen to take this course–family, friends, co-workers.
I am pleased as spiked punch to share that you helped me achieve early retirement! I will be giving my notice, tomorrow, with an effective date of June 1, 2026. I’m signed up for the 2026 course. It seems poetic that the first day of 2026 RFS is my last day at my corporate W-2 job. :-) I am looking forward to the freedom to live the life I want!
Andrea! WOW. Congratulations. This is epically exciting. Wow. First day of retirement and you can celebrate with us. Come say hi on the zoom and we can celebrate together. I am so excited for you. YAY. Loved your message and thank you for writing. Your feedback means so much to us to help improve things! Sending love and happiness A&K
I found RFS by chance mentioned on a retirement planning group. I’m so glad I followed the link to see what it was all about. I definitely fit your typical late starter demographic (mid life, female, lacking in knowledge and confidence).
We had all our savings in cash ISA’s – a large amount of money barely keeping up with inflation. I knew it wasn’t the right thing in terms of growth but fear was paralysing me… and did so for years.
I completed the course via YouTube in October last year and finally took my first step into investing transferring my first matured cash ISA into a global all cap just 1 week before war broke out in Iran. Doubts rushed in as I saw the value of my investment fall. Had I fallen into the very trap I’d been avoiding all these years. What really helped was the messages you put on the group and the time you took to answer every single one offering understanding, clarity and reassurance. That and the Ninjas and more experienced Rebels constantly offering support. The drop continued and I just didn’t worry. In fact I added another matured cash ISA! I’m a changed person – calm, more confident to ride the waves, although I am still checking daily!
I rave about your course and tell anyone who will listen. It surprises me how many people out there still know so little about how it all works.
I’ve also shared much of your course with my 24 year old daughter. I only wish I’d had just a smidgen of knowledge at that age! I wonder therefore if there is an opportunity to do something that is almost bite sized (young people are time poor and want speedy info) as a starter pack almost for young people to follow. A short course in finding the gap, the wonders of compounding and importance of saving into pensions maybe? I know it’s covered in the early weeks of the course but I think having something more bite sized could appeal to that audience.
Sorrry for much longer post than intended! You are doing incredible work, thank you and congratulations!
Clare, thank you so much for taking the time to write this I loved reading your email and stories. LOVED.
I love that you got into the market and it is always the way! lol. Right before the war and a mini-crash, although it has charged back up since which is awesome. So if you got that second cash ISA into the market in the dep you bought at a 7% discount which has seen massive growth since. WOW. I am so happy for you
THANK YOU for sharing the course and spreading the word. We don’t have a marketing budget so that means a huge amount. THANK YOU
You’re also spot on about young people. Even a tiny bit of understanding about compounding and time changes everything. We’re actively thinking about how to make this stuff simpler, shorter and easier to pick up earlier, so your suggestion really helps. I think we could film a mini-series of the course topics and deliver it to young people’s emails. I think that would work, short videos, helping them understand it. i want to film that. Maybe even with them asking the questions and us giving them the quick thoughts….
there is so much to do and so little time. This is on our list!
Thank you for spreading the word.
peace and pineapples
Alan & Katie
Thank you both so much for everything you do. I completed the 2025 course in early 2026 and the knowledge you share is truly life changing. I’ve always been a saver rather than a spender but these days I’m catching myself more and more thinking “do I really want to buy this or do I want to pop that amount of cash in my SIPP instead?” I’m driving my husband nuts!!! I’m planning on watching again this year to see any new info and to help with the bits I still get stuck on e.g. a fixed term cash ISA is ending soon – now should I be putting that in a S&S ISA or my SIPP? Also the Facebook group confuses me a lot with “Vanguard is bad now, you should be using this instead” vibes. I’ve changed things so much in the 3 months since did the course, I don’t want more changes!
Vicky, this made us smile and laugh a little in recognition. That “do I really want this, or do I want to pop it in my SIPP?” moment is awesome and what we had in our head for years..
You’re absolutely right to pause rather than keep changing things. Constant tweaking rarely makes things better, it usually just adds stress. If the plan still fits your life, that’s enough. The whole point of RFS is set it and forget it. Let’s get it all set up and working for you and then go about happily living life!
So glad you’re coming back for another run-through this year. Things land very differently the second time and it makes more and more sense.
On the vanguard is bad stuff, that is utter rubbish and annoys me a lot. They introduced a minimum fee which has annoyed people and then they attack the whole company. It is still a great platform but not the cheapest when starting out and you can’t even do drawdown on the free platforms yet so you have to switch to ii or vanguard later anyway…
We will help with all this on this years course. We are having fun updating it all at the moment. You are fabulous. peace and pineapples. Alan & Katie
Passionate and organised, focused and keen to improve are the words that came to mind as I read that, may have cried a bit… As well as cheering. What you taught was life changing for us. We are both looking forward to this year’s course. Thank you doesn’t quite cut it. I have always been a saver and my husband was always a spender. Now we are on exactly the same page, we know each others bank accounts inside and out and investing and loving life.
Sarah, That is amazing that you two have come together on the same page and have a plan. This made my day reading your update! YAY. Congratulations to you both. I am so so so happy. and thank you for writing. Your words mean a lot! Sending happiness. A&K
I found RFS just before Christmas and spent every free moment watching your videos on Youtube with my fiancé. It really is incredible and extremely easy to follow. We already had S&S ISA before the course but course taught me to be braver with my investments and gave more clarity on how to pick funds. We are doing monthly finance meetings and we populate our trackers with RFS supplied (we actually improved your spending tracker to give us even more data inside!). Like you said, it’s an education, not the financial advise. We signed up for the RFS 2026 to see what else we can learn from you :)
Erika, LOVE you improved the spreadsheet. That makes us so happy. YAY! they were always meant to be a starting point. There are some amazing charts and things you can create from your data. This is so so so cool! thanks for writing back and telling us. You made us both smile! Sending happiness A&K
Hi Alan and Katie, loved the course last year and made lots of changes to our personal finances. Would be great to have some more practical info / examples of GIA and CGT as still a bit unclear on that. The drawdown episodes was great, and be great to have some course notes on that this year so can study in more detail as is rather intricate at first sight! Thanks again – great work and looking for to the new course.
Hey Simon, here you loud and clear. We will do a practical GIA and tax session this year. I think this is a blocker for a lot of people and it is not that simple. We will create something. Love that feedback. Thank you. On the course notes yes I need to develop that and in the future break that one mammoth session into a mini-series of workshops to help people. First job GIA stuff…. Thank you for writing. I really appreciate it and the feedback. Alan
Im a late starter (66) and didnt even have a pension. I have got savings though but had them in cash isas and premium bonds. It was so helpful to learn about index funds (never even heard of them before). I transferred my isas with Vanguard’s help (brilliant customer service).
I also transferred my son’s pension (he’s disabled and is 34) into a sipp with Vanguard and chose the same index fund. I got power of attorney recorded on their system to do it. He will be thousands of pounds better off when he retires!!
I couldn’t totally understand the Net Worth calculations but just kept watching the 2025 RFS you tube videos (brilliant).
I followed Katie’s spreadsheet videos too but couldn’t quite work out how to transfer the skills to help me sort my own finances. I managed to do all the homework but still couldn’t do it for my own simple finances! I will persevere!!
Thank you so much your invaluable help. I would never have attempted anything like this without your videos.
Elizabeth that is AMAZING work on your son’s sipp. I am so proud and happy you did that. You have set him up so well for the future and that will continue to double until he can access it. WOW. Good work .
tell us more about the blocker’s on doing your own finances. this would help us develop the course for this year coming even further. We are planning a new session where you would do a net-worth tracker with us and we would work through it all together on a call. That is the plan for the 2026 course. I am so glad you wrote Elizabeth and thank you. Alan
Hi Katie and Alan,
I took the course for the first time last year. I couldn’t join the live sessions, but caught up soon after—and I’m so glad I did. Before that, I’d only had some light exposure to investing through a work webinar and was putting a small amount into the S&P 500 without much conviction or understanding.
The course genuinely changed that. It was engaging, clear, and hugely motivating. It gave me the confidence to rethink my approach, move to a more diversified strategy, and start putting my savings into global index funds.
I’m still early in the journey, but a massive, heartfelt thank you to you both and all the Ninjas. I honestly don’t think I would have taken these steps without the course.
I’d love to give something back and help with the 2026 course. I’ve signed up to be Ninja-curious. I’m also telling everyone I know about the course :)
Chess, you are amazing. Thank you. What a lovely message to get and congratulations on getting investing and moving broader than the S&P500. That is awesome. Thank you for writing back. We really really appreciate it. Love that you are ninja curious. We are planning an email out about that soon! Sending you much happiness. Alan
My fear, or actually my certainty, is that the day after I start investing there will be a new Wall Street Crash.
hey Bob, 2 thoughts:
1. if that is true and you are still working, it is the best thing that can happen as the next month you are buying stocks on a discount
2. the stock market always goes up over the long term
Are you still working? Retired?
Thanks for sharing. Alan
Still working. I understand that crashes are a buying opportunity, but I’d torture myself with counting how much I’d lost, and all the hindsight wisdom of ‘if only I’d done X’. I know it’s self-flagellation 😆
I also think you (Alan) are one of those people who always land on your feet, you’re a trier who gets up again and again after knockbacks. It’s a great trait to have. Whereas I land on my noggin, then create a spreadsheet listing all my knockbacks sorting by how much I’ve lost. It’s brutal being me 🤪
Bob, sounds like you need to be nicer to yourself. We create the spreadsheet to show how dumb we are and share it with the world to make sure they don’t make the mistakes I made! This mistake is currenlty running north of 100k for me https://rebeldonegans.com/finance/investing/just/ and it was my fault. You are right though, just got to learn and have another go. How can we help you to be nicer to yourself? Sending you love. Alan
A great read thank you. I completed RFS2025 and I made significant changes to our lives and finances with my new found knowledge and confidence. This has cemented my wife joining me in retirement at Christmas this year which is amazing. I have also set my kids on the investment pathway! I love the confirmation that the early weeks gave me that we were in good form with debt, emergency funds etc and starting from a stable platform. The main body of work for me has been the confidence to invest rather than save and spreading the Rebel message. The course was brilliant to allow me to understand volatility better, the main barrier to investing. I’ve signed up for RFS2026 and look forwards to auditioning as a Ninja when you’re next interviewing lol. Keep up the great work you Rebel legends.
Hi! Have you thought about about doing the course over the winter months instead of summer? I loved it but it was hard to be disciplined and stay inside on summer evenings to stay the course!! I did it but it seems like ( in the uk at least) the winter would be more productive…
Just a suggestion and Thabk yoh for all you are doing 🙂
Kristy that is a great idea. I hadn’t thought of that. Summer was just the rythum we got into. I did enjoy seeing the people watching the course outside on zoom last year. I understand what you mean. We will stick the same as we have launched for this year but will chat to Katie about it for future years. You are awesome. Alan
Plain and simple Al and Kate I learnt thousands of people have a better understanding of investing myself included. Doing again this year with my other half.
Mike what a lovely messasge to get this morning. THANK YOU. See you on this year’s course. Sending happiness. Alan
I love that New Zealand shows up so strongly in your numbers. And, I’m not surprised! There are key financial habits that are global, so your course absolutely works here – and NZ is small enough that I can put the word out that it is available. Having enjoyed EVERY SINGLE YEAR, I can’t wait to drag myself out of bed for a mid-winter 7 am start in 2026. Thank you for all you do. There is not a day that goes by that I don’t share your course with someone, and I can’t wait to help out again in 2026. Ruth (The Happy Saver)
Ruth we are SO SO SO lucky to have you. We are excited to do a New Zealand session with you and we have loved your blog and content and thank you. We are lucky to call you and Jonny friends. Love you both and can’t wait to see you later on this year. THank you. Alan
Thanks for sharing Alan and Katie’s course on your blog, Ruth. I wouldn’t have found this otherwise, and it genuinely is one of my favourite times of the year, haha, money geek that I am :)
Ruth is amazing isn’t she……
Thanks Alan and Katie for RFS25, we felt that the financial advice we were receiving prior were by people with vested interests and felt paralysed by making the wrong decision and didn’t know where to start. My top 3 ah ha moments….the financial tracker, this is what gave us confidence that there was alternative to IFA software, 2) the volatility training….hilarious and useful given the recent ups nd downs, 3) the clear structured path to follow. My no.1 wish would be for more content around drawdown / tax strategies and tools for those of us about to retire. Plus a list of good IFA/accountants that can provide tax advice not investment advice. Have forwarded my entire family the link for your 26 course. Thanks again for both your efforts….it gave us clarity and confidence to move forward. Have you thought about requesting govt funding to put courses into schools?
Emma what an awesome message to receive and I loved your top three ah ha moments. Thank you for sharing. I appreciate it. Love the thought about more about tax and things like that. We will be doing GIA tax this year and some more bits. I think draw down needs to become a mini-series and we need to develop it and create new content. it will be interesting to take what we started and develop it.
on the school we would love to help do that. We need a team to do that which the finances would allow us to do. We haven’t done it as we are so focused on the course, book and youtube channel at the moment! Got to remember to have fun sometimes too! lol. Would love to get this kind of education started earlier!
you are awesome. THANK YOU for writing. Alan and katie
yes please to more content about pensions and tax efficient ways to draw down 🥰 that would be amazing!!!
Hey Zozo, that will be coming later. Course first and then later afterwards we will redevelop that series! you are awesome. Alan
Dear Katie and Alan. I enjoyed reading this article, you guys have done a fantastic job in analysing the data and I think you really nailed it. What a fantastic legacy you are building! I have been doing the course for at least the last three years, and even though much of it now is what I already know I do still enjoy watching every single week because I use this time of year to be a total refocus on our finances. Every year has seen a new focus: early on it was understanding about creating the biggest gap as possible and understanding market volatility, the next it was checking fees on our investments and making appropriate changes, and last year was simplifying our investments (it feels so much better now things are ‘clean’). I’m feeling more confident than ever, and the time has almost come for me to think about our next focus…I’m not too certain but I’m thinking it will revolve around money psychology- spending on what we enjoy without guilt. As a born saver, this is a challenge and I’d really like some tips around ways to manage this. I love what you do and can’t wait for you to start your 2026 course. Thank you for everything you do!
I absolutely LOVED the course and was a proper swot with my notebook and homework. I’ve signed up for 2026 already because I know that there will be real value in coming to it from a much higher starting point and revisiting everything. I already had a share ISA with some fairly broad based ETFs that my partner had set up for me, but I really didn’t understand it and felt I had no control. For me, the biggest changes were my behaviours. I had inherited some money, but also had some debt. Guilt was stopping me from using any of the money to pay off the debt, but the course pushed me to make some absolute ‘no brainier’ decisions that have put me in a much much stronger position. I have tracked EVERY penny I’ve spent for almost a year now, and faithfully hold my monthly meeting. I am hoping to retire in less than 5 years (I’m 53) and Katie’s incredible spreadsheets have made me feel so much more in control. I can’t tell you how much difference this course has made to my life… honestly. Thank you so much
What an AMAZING post. Congratulations for taking charge of your finances and all you have done to put yourself in a great position. Sometimes it is just doing those no brainer things and getting them done and allowing time to show you the positive impact. LOVE that you have done the finance meeting for a year now. That is incredible. I am so happy. Thanks for telling us Zozo. Can’t wait to see you this year’s course! Alan
Love it – thanks for the stats and all your hard work Katie & Alan! S&S ISA and SIPP set up, everything is automated and investing like a dead person! Currently working my way through Rebel Business School to get increase the gap! “Action eases anxiety” is something that came up in the last video and that has really struck a chord. Looking forward to Rebel Finance 2026!
Hey Karen, absolutely. Action does ease anxiety and you have done SO much with your finances. NICE WORK. I am so impressed. Thanks for replying. Alan
I felt like I learned a lot, then I got hung up because I live in the Isle of Man and the tax structure and products are different here as you know. I also then became scared because I want to retire in no more than 5 years which will leave me 5 years to fill before SS pension.
I do check my dc pension value every day because I’ve worked pretty hard to lift the value in the past 5 years. I decided to photograph the value each day so I could see the value and to be honest, although I was mad about a certain person’s actions affecting my pension I didn’t panic thanks to RFS. I’m still sat on a ridiculous amount of cash and with the support of this year’s course I will fix that.
Hey Jo, thanks for commenting and telling us what happened. WoW what a roller coaster you have been on. Let’s get your cash invested and the next time you see a the person that can not be named messing with your pension think “this is a good time to get my money into the market” or ideally just do it anyway and get it invested! Sending you happiness and can’t wait to see you on this year’s course. Alan
Thankyou for all your work! 2025 was the year when I felt I was in a position to open a SIPP and invest after starting my journey with RFS in 2024. I was really inspired by your in person tour and have met some fantastic finance friends at my local meetup. This year I’m aiming to change my platform and probably change the fund I’m investing in to further reduce my fees. I’m excited there’s going to be 2 more free options for SIPPS this year (Freetrade and T212). Now they’re free maybe it could be one of your homeworks to open an account?!!!! I’ve also putting on a training session at work to try to encourage more people to find out about FIRE and will be pointing them in your direction for this year’s course.
Carrie, you are AMAZING. Love the progress you have made and it is exciting about the potential free SIPP options. T212 could be huge to help people get going with a free iSA and SIPP. That would be amazing. And congrats for putting on the work session. That is awesome you are doing that and thank you for sharing this years course! It means a lot, we don’t have a marketing budget! lol. THANK YOU. Alan and Katie
Kinda weird how excited I feel about the 2026 course starting – bringing hubby along (and hopefully adult kids) for the ride yay! Learnt so much and felt so empowered from doing the course last year, would so love to join live but still working, so will do catch up from NZ. Really just wanted to thankyou so much for your knowledge, support, time, energy and kindness – forever grateful.
Toni what an awesome message and we LOVE that you are doing it as a family. That is amazing. I love that. And maybe catch up in the evening with food and drinks? That is so exciting. Thanks for commenting and let us know how you get on this year! Sending happiness Alan
I am spreading the rebelution: since autumn 2025. I have influenced my three sons in their early investment journeys and told many of my friends too. Best bit was my Aviva win whereby during my transfer enquiries, I managed to encourage the young girl on the phone to look up RFS! She scribbled down your details saying that her and her boyfriend would be straight on it! Thought you’d appreciate the irony of this! ( would have been funnier still if it had been an SJW employee!)
Your altruism is awesome -never stop pineappling!
Thanks so much to you both and to the ninjas. Everything you’ve covered here resonates. Excited for RFS 2026.
Corinne, thank you for taking the time to comment! YAY! We are excited about this year too and making it even better! Sendning Happiness. Alan
Hello, what a great article and what findings!! A friend introduced me to your RFS course last summer, as a result i watched RFS25 on you tube over the autumn…. starting to take action late December!. I’m so looking forward to joining live in 2026 (filling in on YT on return from hols), I’ve asked friends who have signed up for RFS2026.. I hope to pick up more tips in areas i still have some questions – but i know you will be helping many people to improve their lives by taking action.
Thank you both and FB ninjas for all you do.
Hey Amanda, what a lovely message to get. Thanks for writing back to us and glad you found us! Welcome back to the course and excited to see what you think of this version! You rock! Alan