

Join the mailing list!
5th Jan 2026
At the end of the year, Katie and I always get excited because this means a chance to do our annual finance review!
How often do you review your finances? Do you check daily, as some people do when they first find out about investing, or are you a set it and forget it person?
The yearly finance review is the single most potent, low‑cost habit we know to build clarity, calm, and momentum with money. If you’ve never done one, start here: How to do your annual finance review. Then come back and read our story for inspiration, and maybe a nudge to make breakfast part of your ritual, too. (Because… breakfast.)
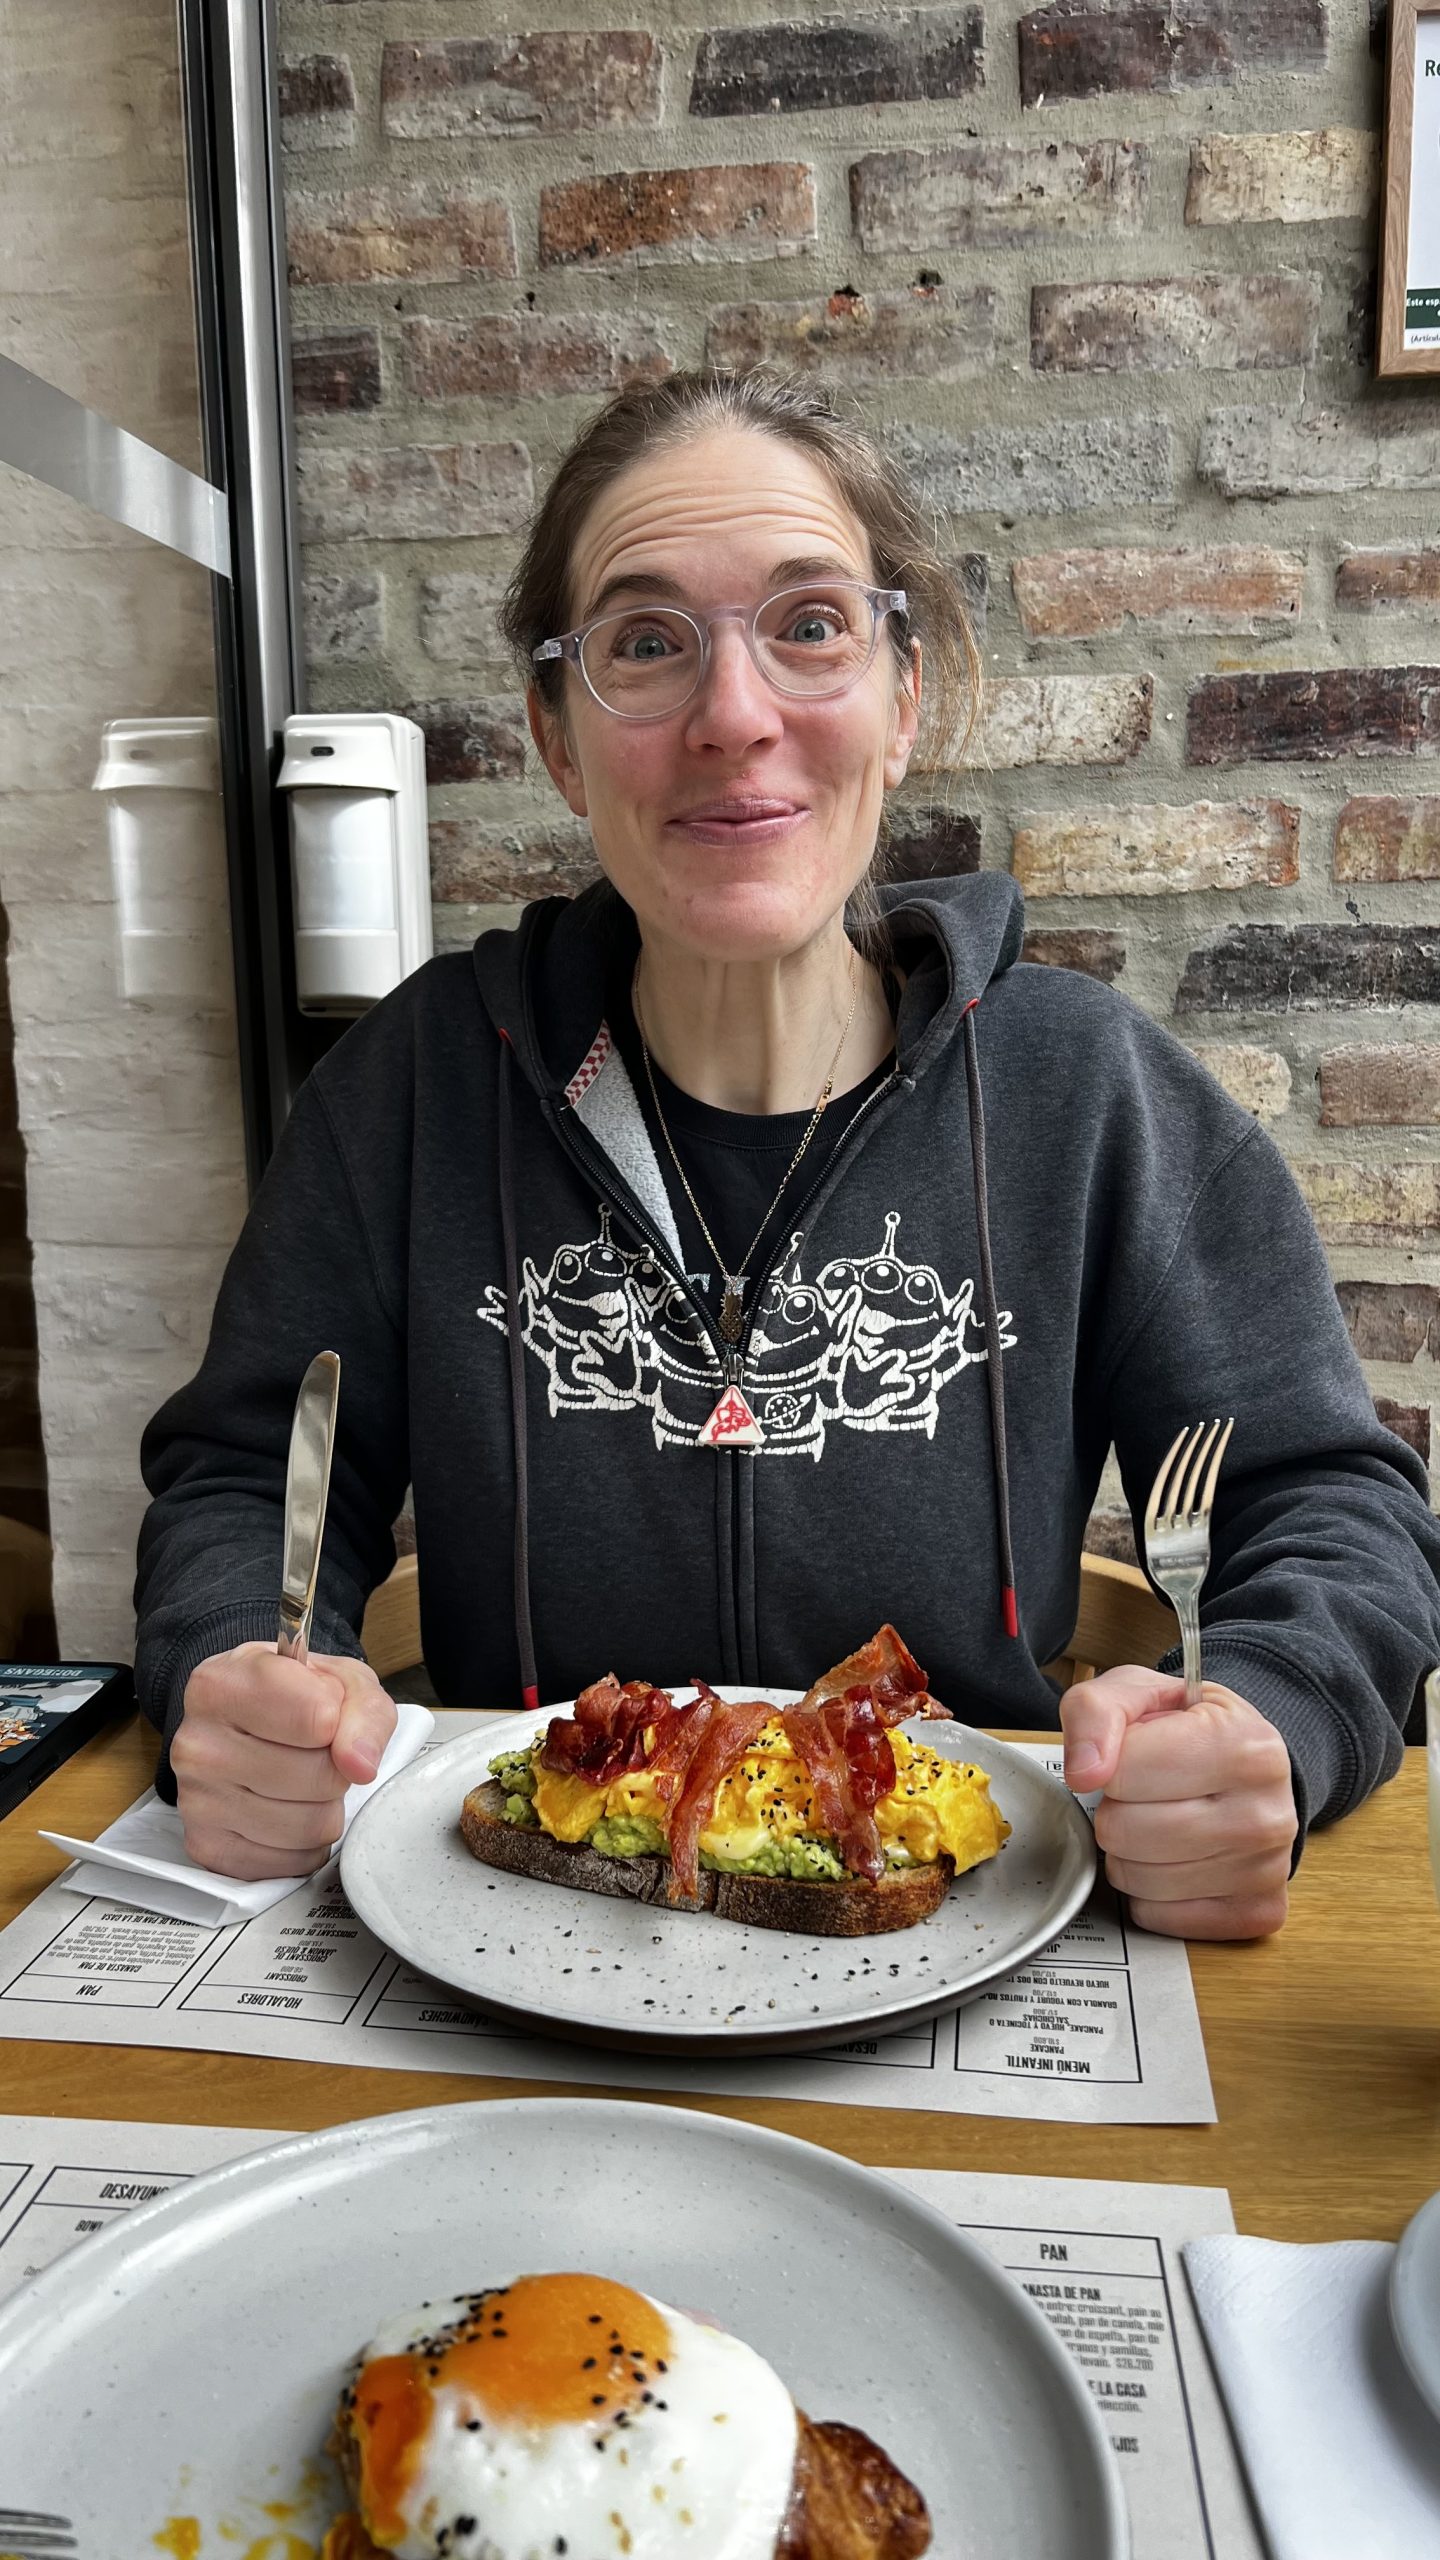
This year-end, we headed to one of our favourite cafes, Masa in Bogota, for breakfast, coffee and a cheeky almond croissant!
This annual finance review is special for us. It marks ten full years of monthly finance meetings, ten years of turning up, tracking, laughing, course‑correcting, and making decisions that actually align with our values. Consistency matters. Habits matter. These are the habits that created the financial abundance we live today, and they can do the same for you.
Every year-end we do a lot of reflection. Read on for the charts Katie has created, all the numbers and what we think are the habits that have built our financial success. Maybe just maybe they will do the same for you.
Why are we sharing our numbers and net worth? Because we want to break the taboo around talking about money and so we choose to lead by example. We are doing that by sharing our exact numbers and everything we have learnt on our journey. Read on for our net worth, learning and more…
Remember: don’t compare your pineapples. Please don’t stack our numbers against yours. We are all starting in different positions. Comparison is the thief of joy.
Instead, run your own race. The key thing to do is compare your situation now to your situation last year and see if you are improving. Enjoy our numbers, learn the lessons and then focus on your own race and improving your own finances year-on-year.
Different strategies for different stages. Remember that you need different strategies for how you do things at different points in your financial journey. If you are building your net-worth you will want different strategies to the ones we use now we are living off our portfolio. In the article I have tried to highlight the differences. Let me know if you spot anything that doesn’t match!
2025 Predictions (not ours!)
Ever year Business Insider runs an article where they gather together all the expert predictions for the stock market and how the S&P500 will end the year.
I have written a glossary of terms towards the end of the article. If you don’t know what the S&P500 is then click here to skip forward to the glossary then come back!
During last year’s Rebel Finance School lots of people sent us expert opinions showing what the stock market would do in the future and it made them scared to invest.
We have seen these same articles for over a decade now so we thought it was time to look at what the so-called-experts predicted compared to what actually happened.
We spent 4 joyful hours collecting all the predictions from 2015 onwards and comparing them to what actually happened in the stock market.
I’m going to show you the 2025 predictions first and then what actually happened last year.
The predictions ranged anywhere from a 2% increase predicted by Jeffries all the way to the rather impressive prediction of 20.7% growth by Oppenheimer!
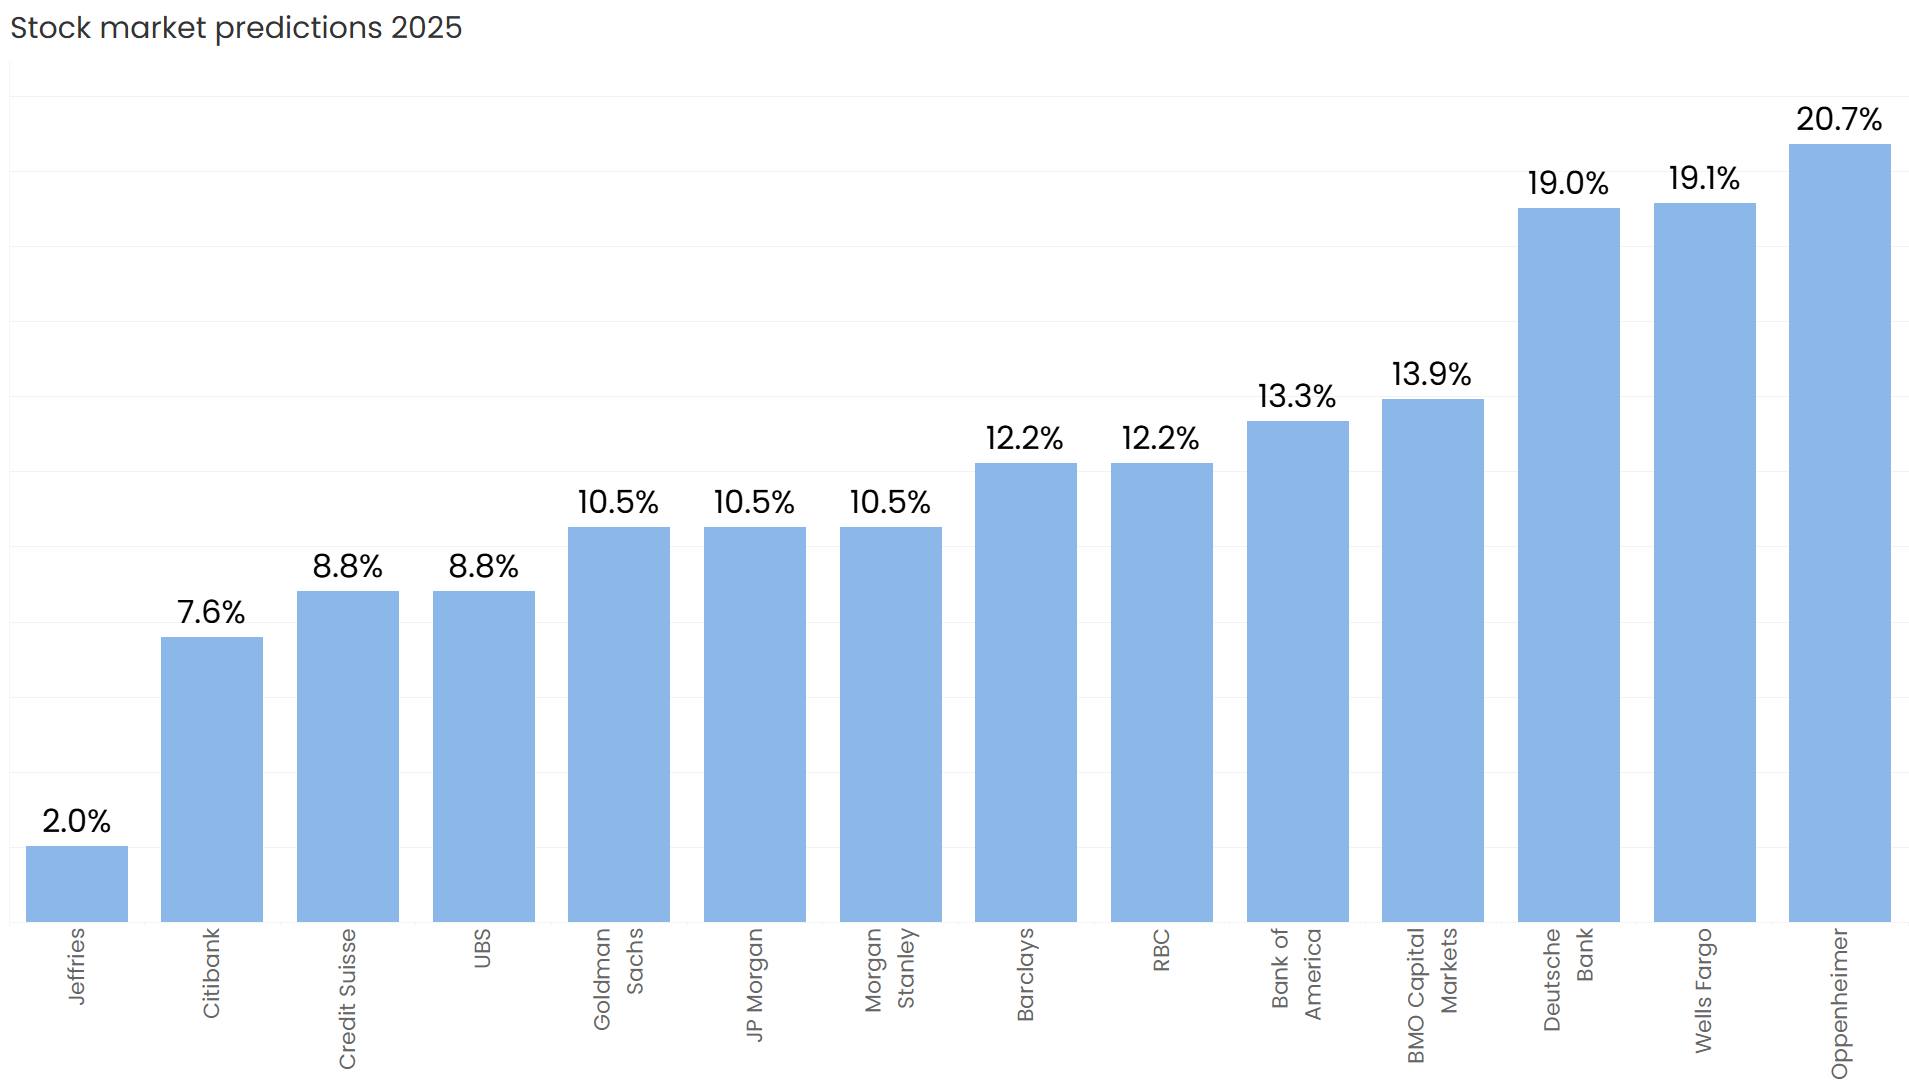
Who got it right? Did anyone guess the right answer? What actually happened?
The S&P500 grew by 16% in 2025, somewhere roughly in the middle of the prediction pack. In reality this isn’t actually a bad set of predictions from Wall Street about the stock market, although most of them were out by 5-10%! What’s 5-10% between friends?
Doesn’t sound like a lot but to give you an example…
@ 5% annual growth for 10 years, $10k turns into $16,889
@ 10% annual growth for 10 years, $10k turns into $25,937
I know which I’d rather have!
Back to the predictions… here’s the same graph with the actual performance of the S&P500 added in in yellow:
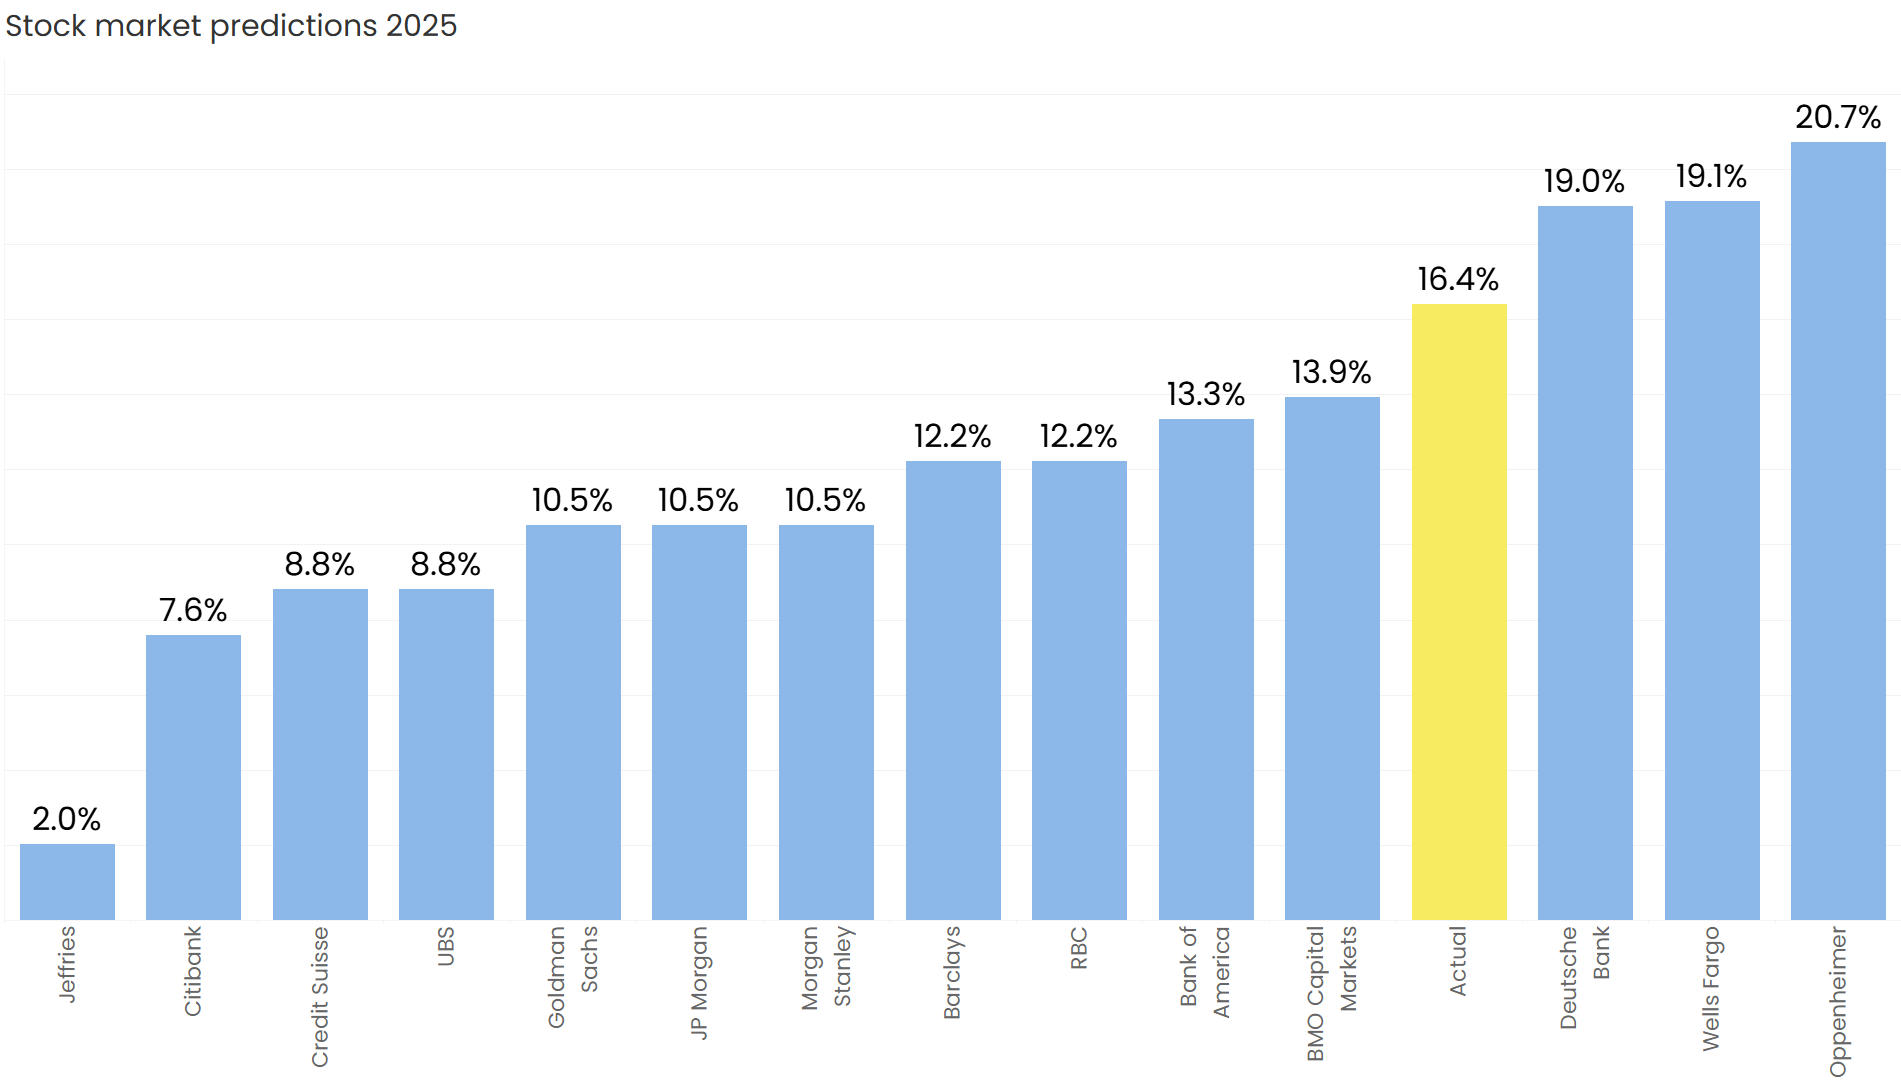
Jeffries got it wrong by 14%, Citibank missed the mark by 9% and the closest to the mark was BMO which was “only” 2.5% off the mark!
Now we don’t believe we could do any better. We know we can’t predict what is going to happen in the markets so we don’t bother trying. The point of this is to show you how wildly inaccurate “expert” opinion normally is!
The “experts” can be wildly off! In 2024, JP Morgan predicted the market would shrink by 12% and in reality it grew by 23%. They were 35% off in their prediction. If you’d have listened to JP Morgan, panicked and sold out of the market, you would have missed out on a year of bumper returns.
You might be thinking “Donegans, why are you so interested in predictions?”
Up until this point we never have been because we know how wrong they are every single year. But with the growth of Rebel Finance School and the number of people spooked by the media and these expert predictions we thought we should actually get the cold hard data to disprove what the “experts” say.
Check out our stock market predictions article that shows you all the results from the last decade and even gives you a chance to predict what will happen in 2026!
Conclusion: No one, not even the “experts” can predict the future
✔ Annual Finance Review Checklist
Run your review this week (60–90 minutes):
The 2025 Story: A Correction, Some Facebook Fear, and a steady climb
What happened out there: Markets hit new highs in mid‑February 2025 and then slid into a 10%+ correction by mid-March.
In early April, the U.S. announced “Liberation Day” tariffs that intensified volatility for a while and there were some spicy headlines and massive single day market swings, but it didn’t end up in a full-on bear market.
Translation: a market correction, not the end of days. We stayed invested and from a personal Donegan perspective ignored the media.
What happened in the Rebel Finance School Facebook group? The group bubbled with “Is this the end?” energy. It got extreme for a while with some people commenting “I can’t take this, watching my life savings disappear day by day!”
We get it, corrections poke your amygdala. But the plan is built for storms we cannot predict. We remembered: corrections happen, then eventually the line slopes up and to the right.
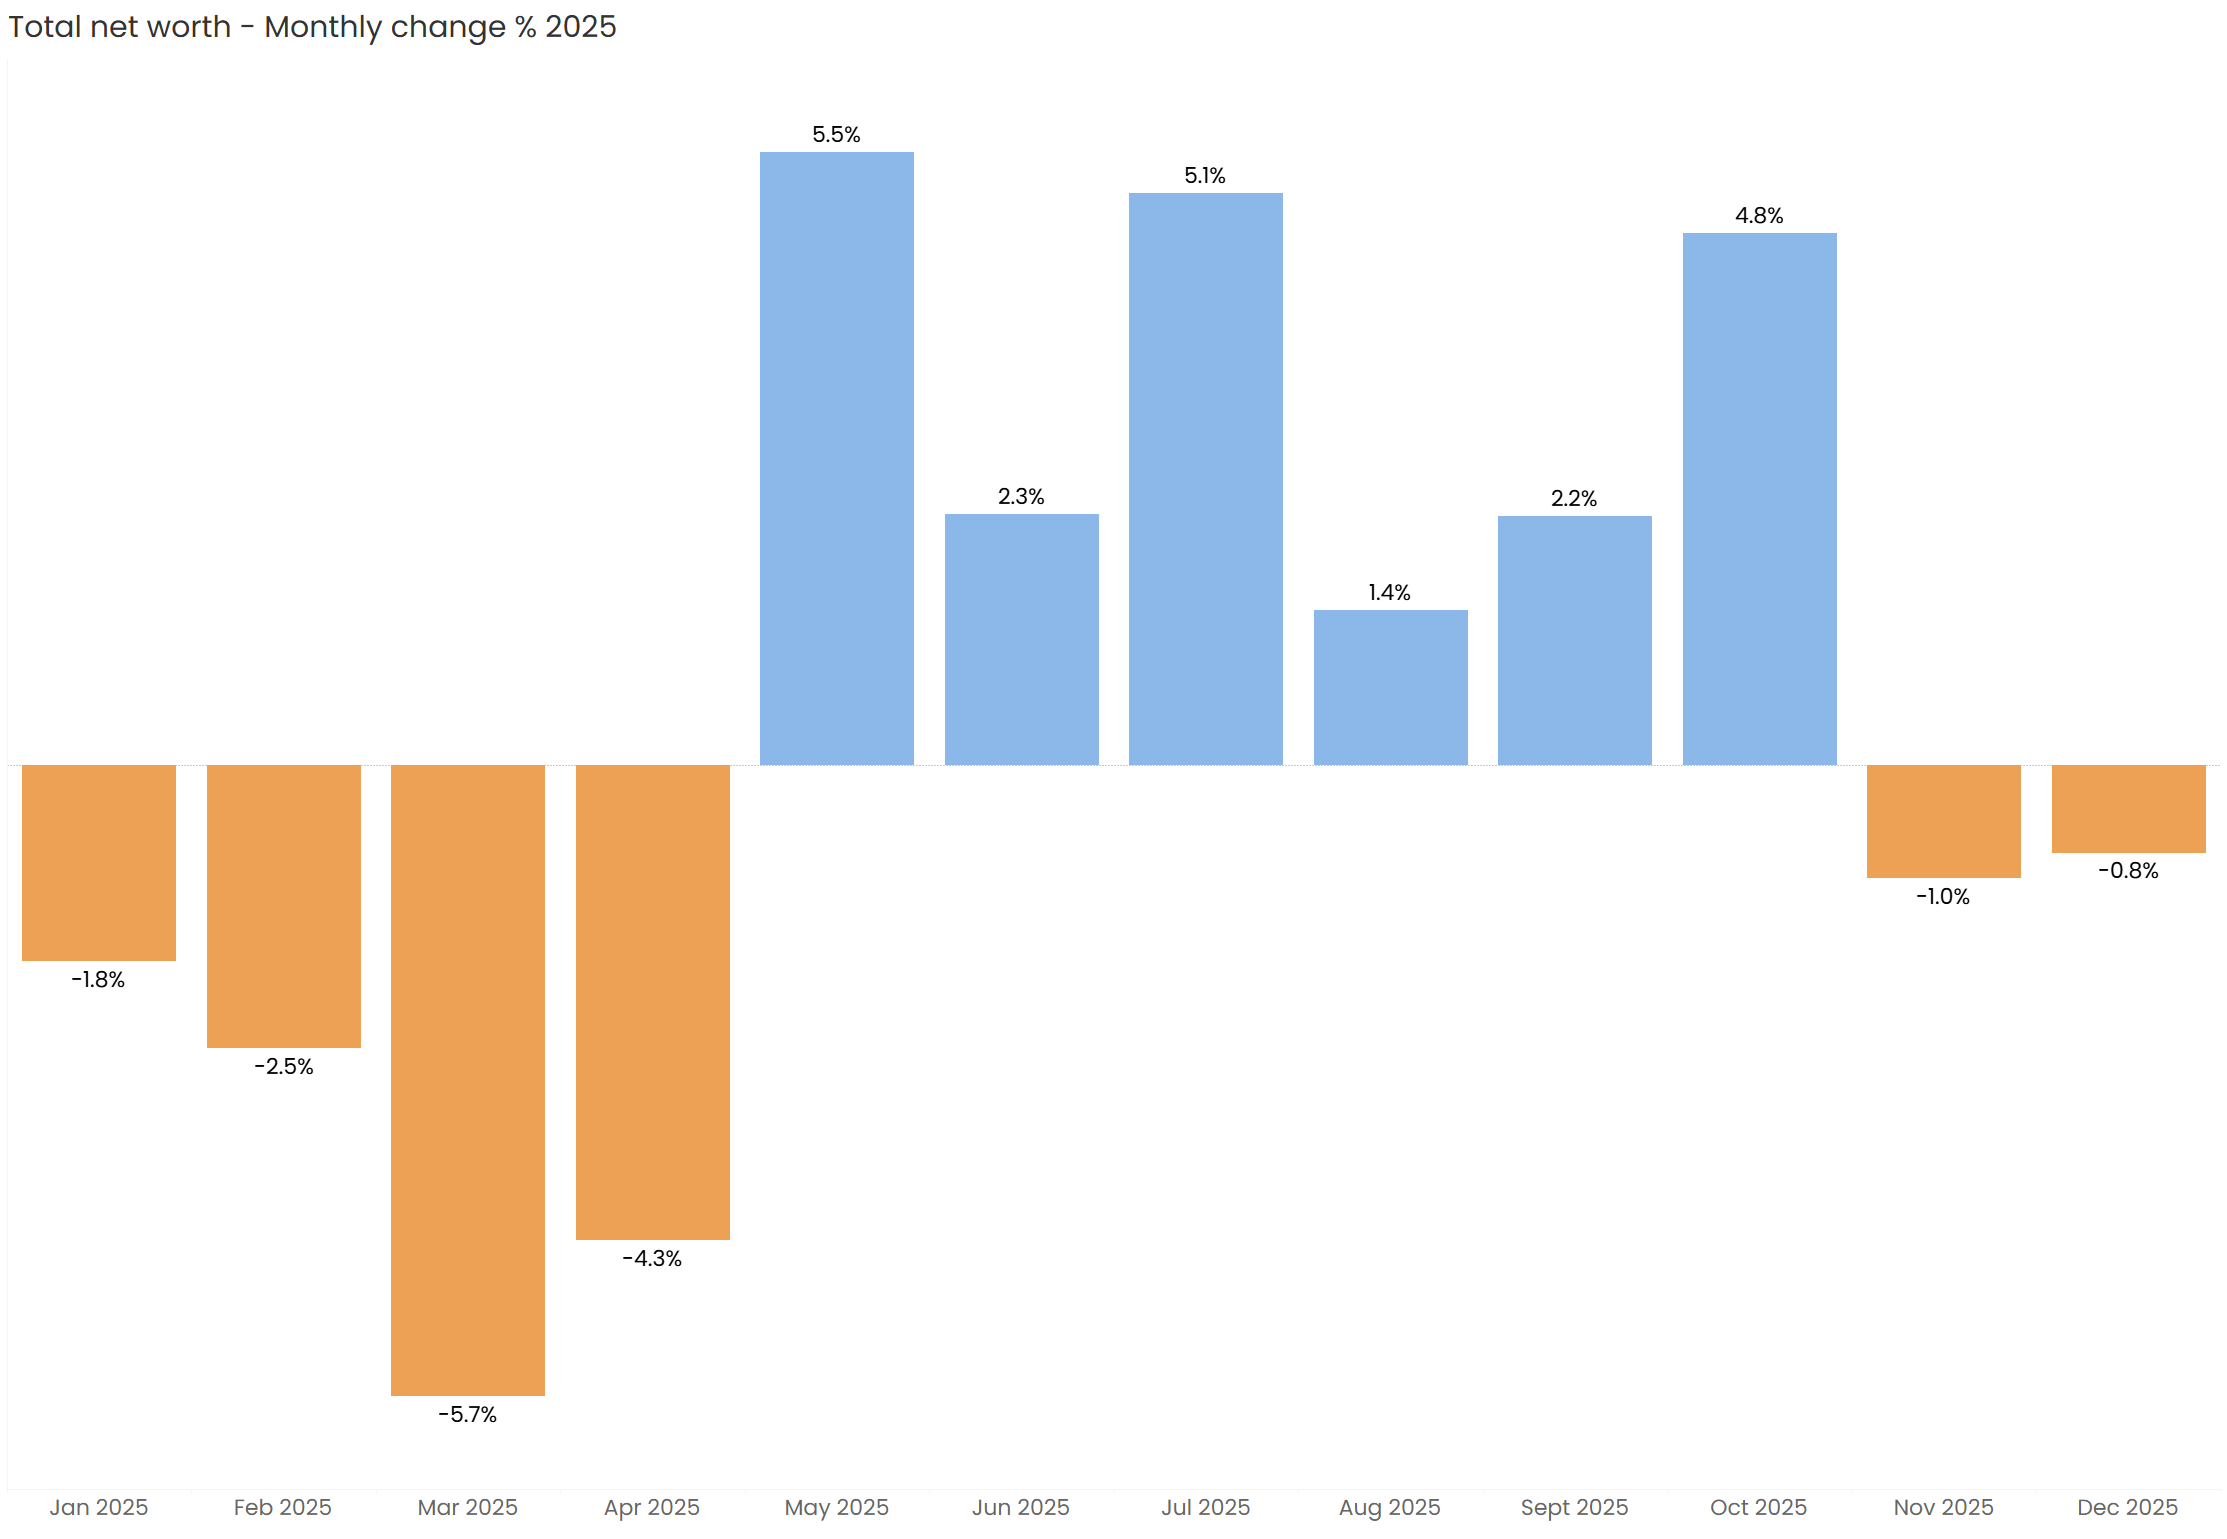
And 2025 did exactly that: a dip in March/April, then a steady climb through the back half of the year. You’ll see that rhythm in our Monthly Net Worth 2025 chart.
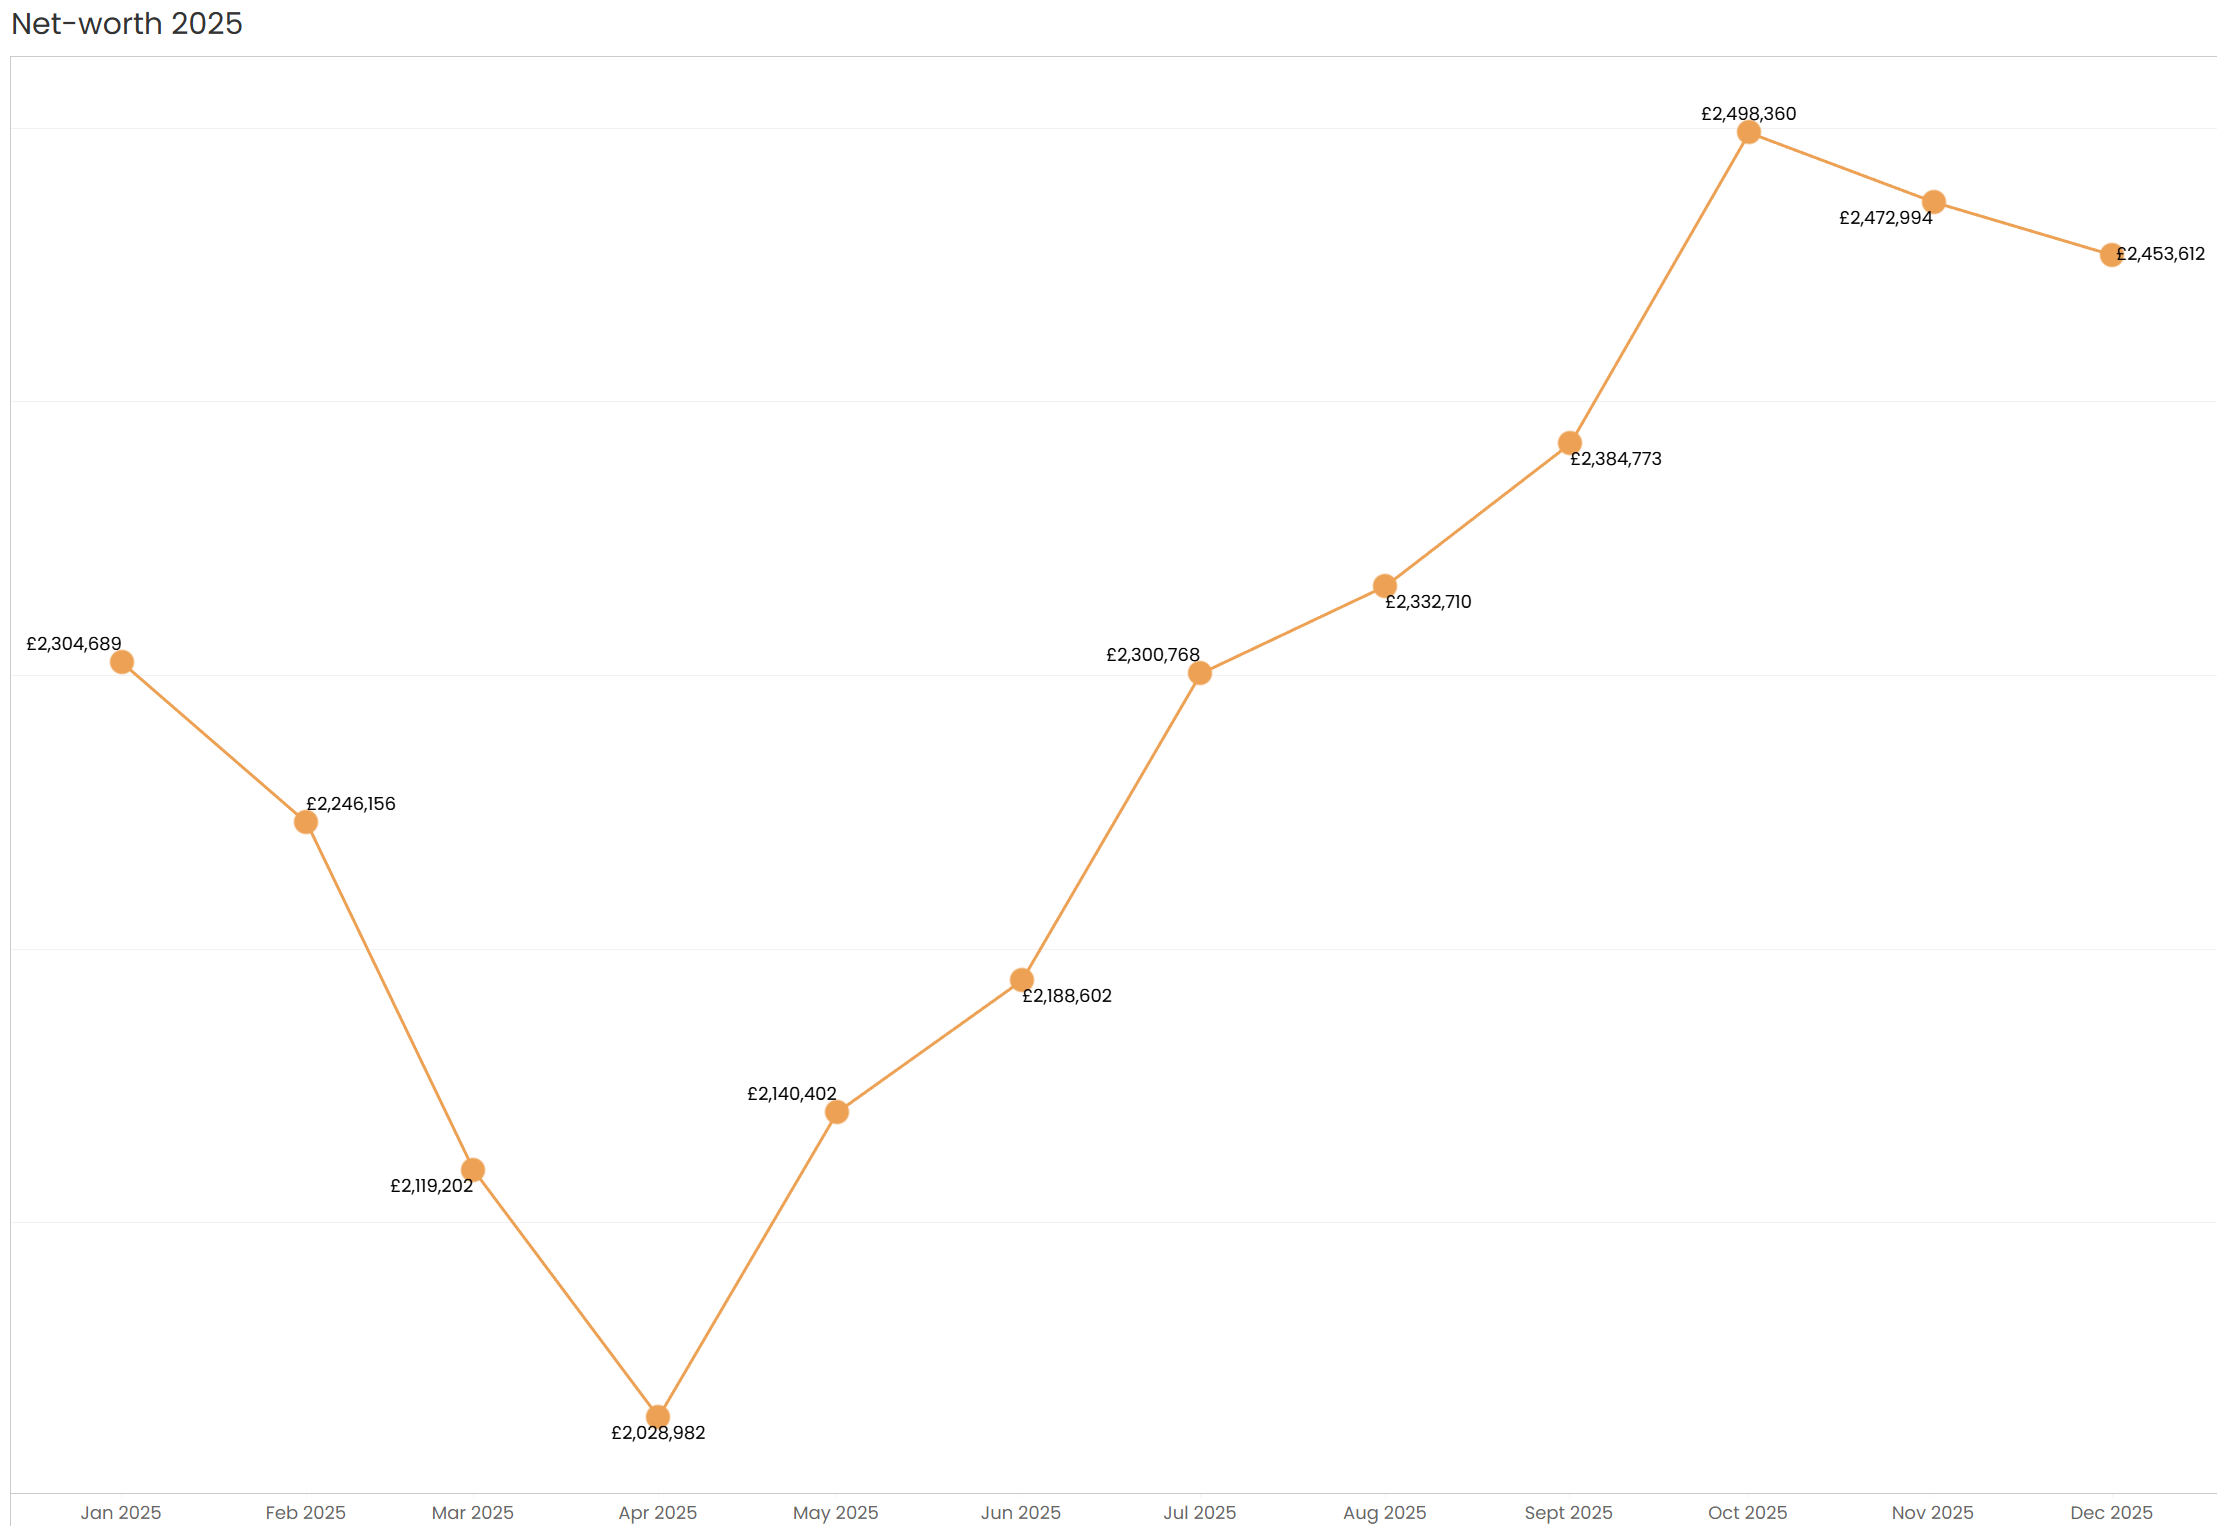
In the period from January to April our net worth reduced by £275,707. Yes you read that right. Our net worth reduced by over quarter of a million in three months.
You might be thinking “Donegan’s how can you tolerate this? Surely you panicked? My portfolio went down by £10,000 and I was panicking a little bit!”
We barely notice these things unless they are posted in the Rebel Finance School Facebook group. We don’t read the papers or listen to the media, we are too busy having fun, living life and enjoying the world.
Here are the thoughts that kept us safe during this rocky period and every rocky period in the market. Bookmark these or keep them at hand for the next market downturn.
Thoughts That Keep Us Safe During Market Downturns
- I haven’t lost anything unless I sell.
The number of units I own hasn’t changed – just the temporary price tag. Volatility is just the market breathing. - Volatility is the price of admission.
Ups and downs are the cost of using the greatest wealth-building machine ever created. If I want the long-term gains, I have to ride the roller coaster. - The long-term trend is up.
Zoom out. Over decades, markets rise despite crashes, corrections, and scary headlines. My job is to stay invested and let compounding do its thing. - Focus on what I can control.
I can’t control the market, but I can control my Freedom Rate, spending, and mindset. I pour my energy into family, health, and the life I’m building, I don’t obsess over the daily price! - I have a plan before the storm hits.
An Investment Policy Statement (IPS) or clear rules stop panic. I know my allocation, my cash buffer, and my “do nothing” rule before volatility arrives. - Remember: downturns are normal and temporary.
Corrections happen every 3-4 years on average. They feel dramatic in the moment, but they’re just part of the journey.
Units vs Price: Staying Calm
When markets wobble, your unit count doesn’t change - just the temporary price tag. Tracking units shows the progress you control (contributions, reinvested dividends), while price reflects short‑term noise.
- Track units monthly if you prefer fewer emotions: watch your holdings climb over time.
- Accept volatility if you want the full learning: the best way to get comfortable is to experience a downturn and survive it.
- Bookmark the rule: you haven’t lost anything unless you sell; volatility is the price of admission.
Either approach works. We believe the winning combo is: track units + experience volatility + stay invested.
The next chart is the monthly percentage change in our net-worth over the year. You can see that the first 4 months represented a 14.3% drop in our net worth. That is huge.
But the growth in the second half of the year was 21.7% This year was a game of two halves!
Our numbers:
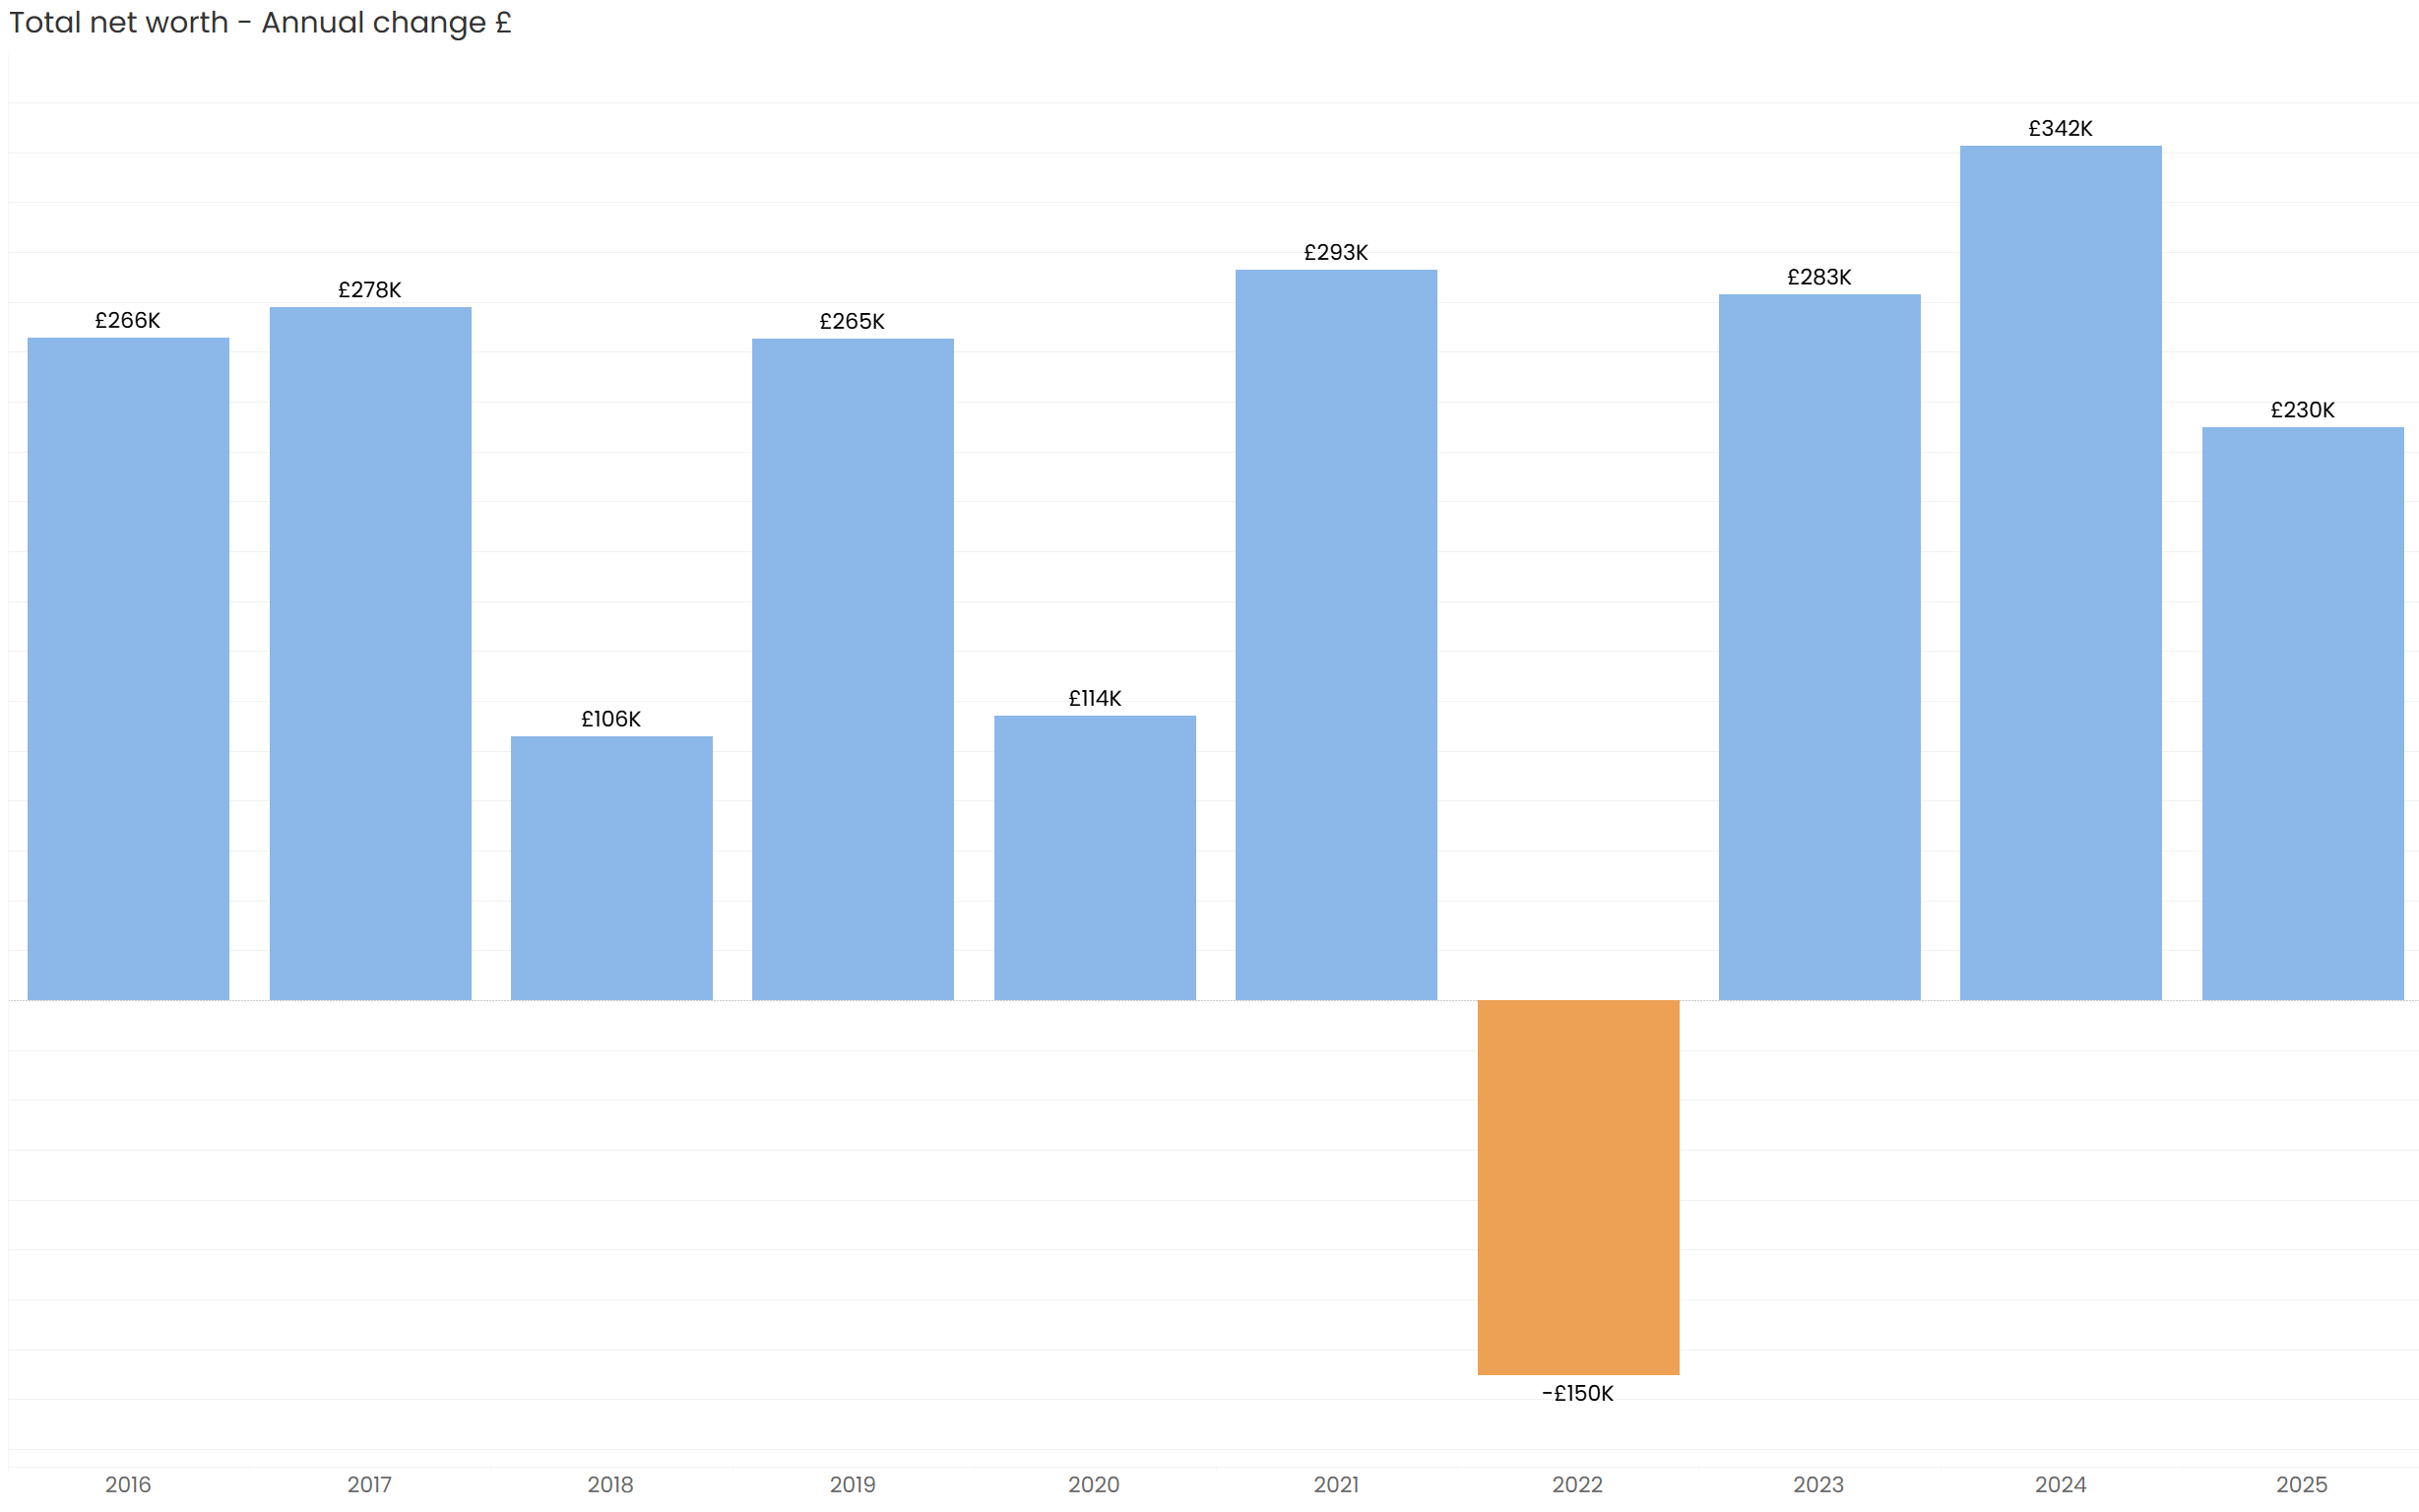
- Donegan net worth at 31 Dec 2025: £2,453,612 (up from £2,223,978). That’s +£230k while living well. We’ll take it.
- Spending (context, not a score board): We spent nearly £100k this year and that included lots of travel and adventures. Our spending varies year to year, and we don’t believe in comparing pineapples! The biggest challenge with Financial Independence is shifting from frugality when you’re building your Freedom Fund to spending when you’re living off your Freedom Fund and we are working hard on it!
The expression that has really helped us loosen our grip on our spending and our old frugal habits is “We don’t want to be the richest people in the graveyard!”
Frugal habits will make you wealthy but they won’t help you enjoy it!
Every year we ask a set of questions in our annual finance review and one that always sparks interesting discussion is “What bought us joy this year?”
Where money bought joy in 2025: Venice Beach months, a gym‑upgrade hotel in Bogotá, and a Puerto Vallarta stint that delivered serious life quality at £3,600/month.
Plus Disneyworld for Alan’s birthday, money definitely well spent. This is us meeting Black Panther at Avengers Campus, Disneyland!
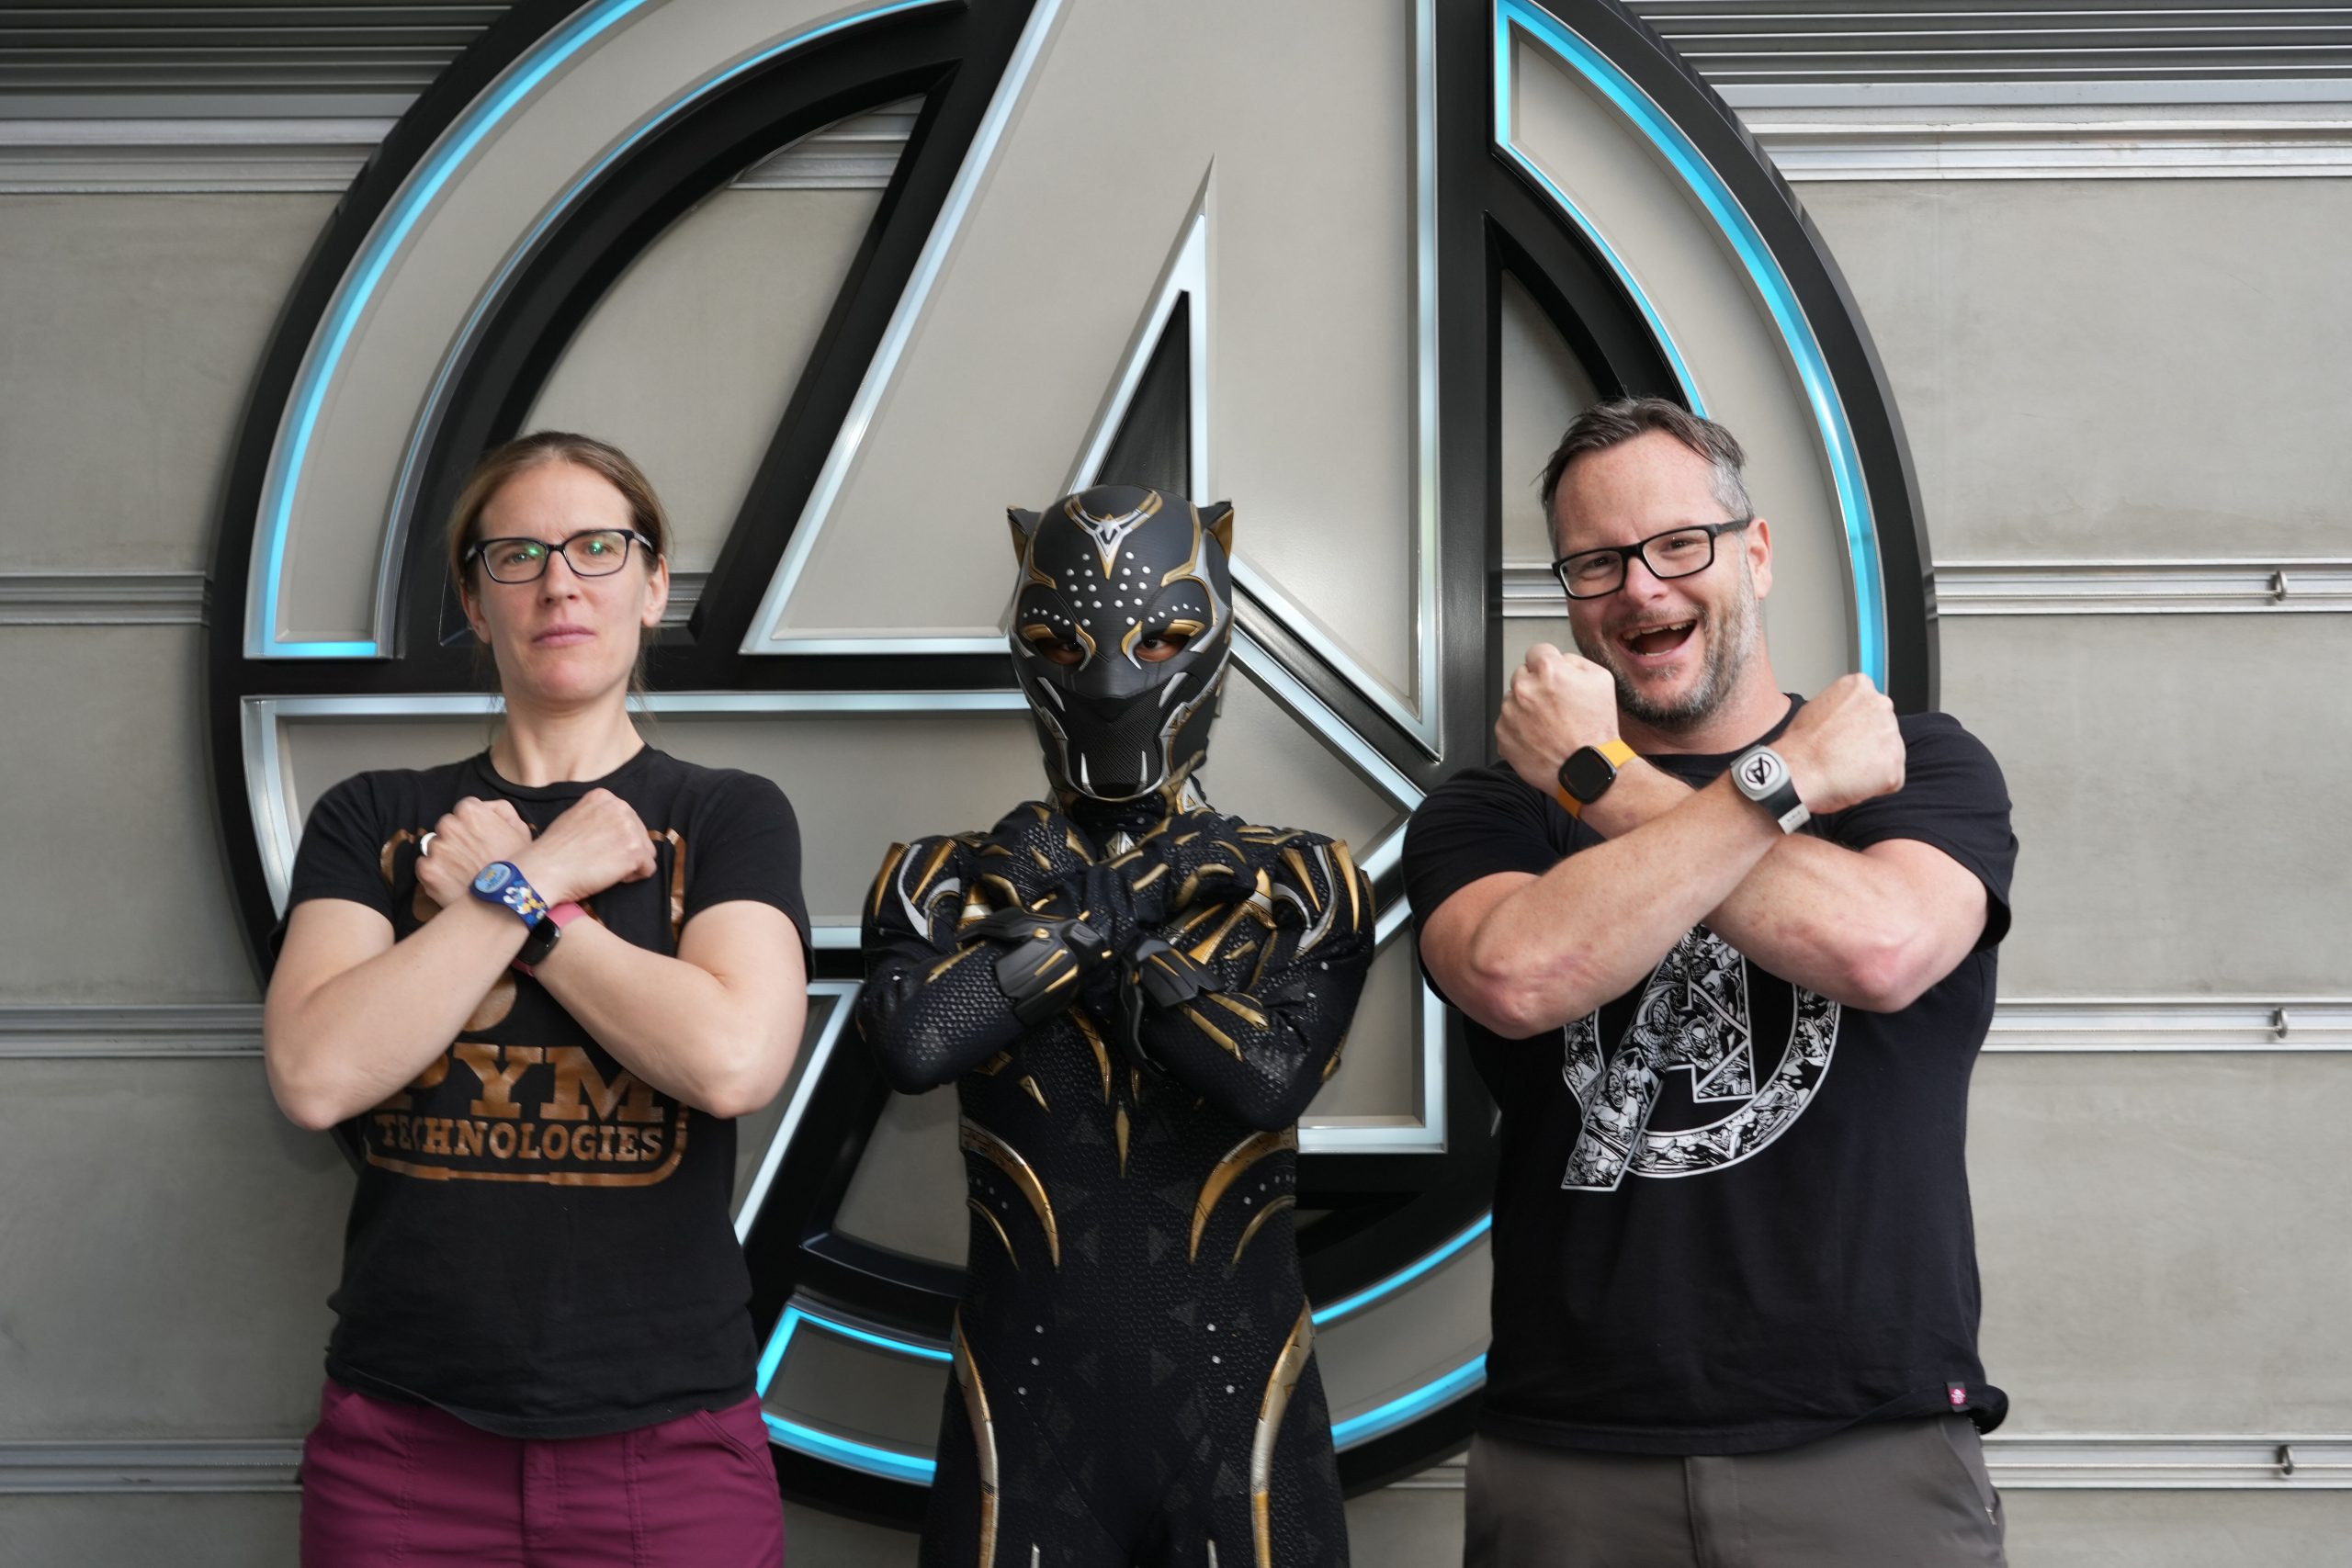
Spending Aligned to Our Values
- Health & Energy: Hume Gym, LA - a premium environment that boosted consistency, strength, and daily happiness. Plus for the first time ever we invested in a daily supplement regime to increase health and longevity.
- Contribution & Community: UK Tour - significant expenditure, worth every penny for connection, impact, and shared learning.
- Playfulness & Teaching: Printing Pineapple Cash - a fun, tactile teaching tool that helped people “get” the money lessons.
- Fun & Adventure / Environment: Disneyland for Alan’s birthday & two months in LA on the beach - peak joy, creativity, and recovery time that fuel everything else.
Reminder: money is a tool. Use it to buy energy, connection, and memories - not clutter.

Our Most Joyful £100 Spent (small thing, huge payoff)
Eye masks. Specifically, Manta Sleep Masks. Not glamorous. Not expensive. But game‑changing for sleep and daily energy.
Why they matter for us:
- Blackout anywhere: red‑eye flights, bright hotel rooms, odd Airbnb curtains – full darkness on demand.
- Zero eye pressure: 3D cups mean natural blinking and no “squash” – so we actually keep them on all night.
- Compounding effect: deeper sleep → calmer mornings → better decisions → more joyful adventures.
Mini‑lesson: Don’t wait for big‑ticket purchases to improve your life. The smallest upgrades in sleep, recovery, and environment can deliver outsized returns every single day
Zoom Out: 2022, 2023, 2024, and 2025
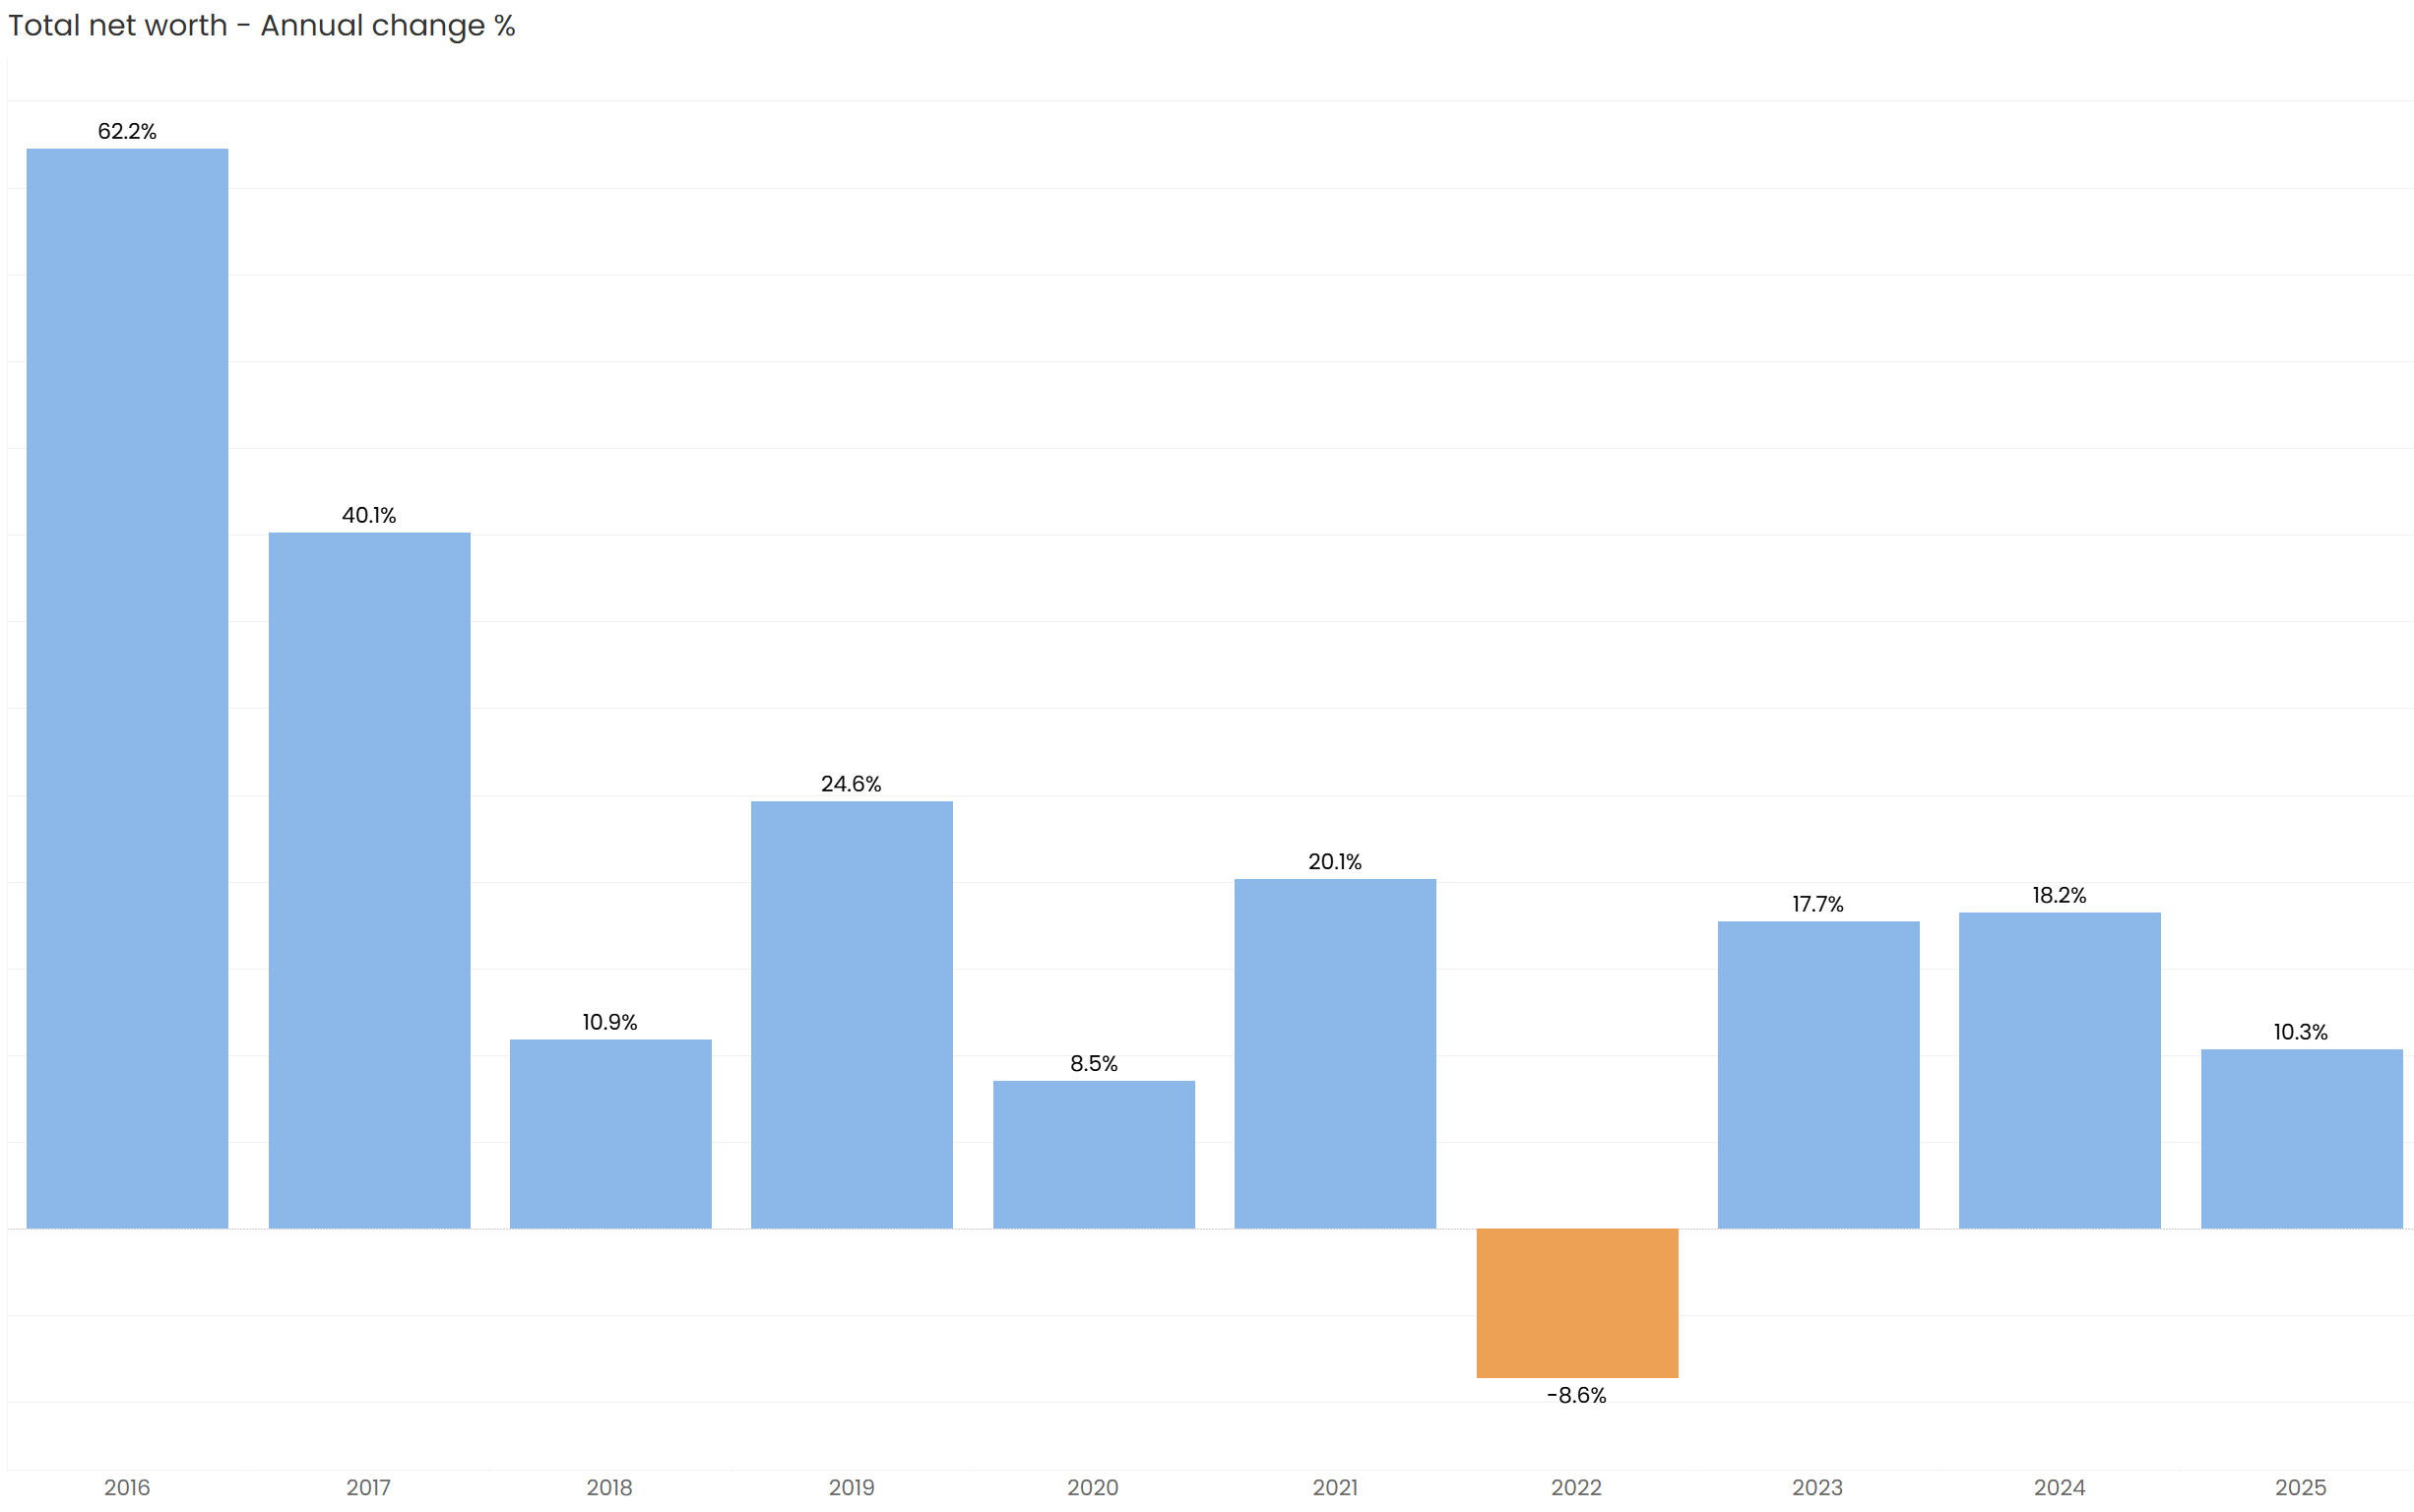
One out of four years ends down on average for global equities. And that’s exactly what we’ve seen reflected in the annual change in our net-worth:
- 2022: –8.6% (ouch)
- 2023: +17.7%
- 2024: +18.2%
- 2025: +10.3%
Short-term noise, long-term signal. That sentence means that there is lots of volatility (short-term noise) but over the long term the market always marches up (long-term signal). That’s why we invest like dead people: buy global, sit still, and get on with enjoying our life!
This chart shows the change in our net worth year-by-year in percentage terms. The big change at the start was because we were just starting and focused heavily on getting going quickly so it created HUGE percentage shifts.
You can see the dip in 2022 when we didn’t have enough earnings to ride out the volatility as we were living off our portfolio at that point.
This next chart shows the change in net worth by actual £ amounts. Not percentages but the real amounts that our net worth grew by. You can see the big orange block in 2022 which shows our net worth decreased by £150k that year.
That is a huge dip and we remember running Rebel Finance School that year and helping people to start investing whilst the market was falling.
What’s our net-worth split
This chart shows you the split in our funds and account types all in one go! I love Katie’s dashboards! You can even see how it’s changed over the last 10 years.
This next chart is an interactive Tableau Dashboard and best viewed on a laptop or desktop. It shows three different splits pulled into one easy to view dashboard.
- Net-worth split between Valuable Liabilities, Debt, Cash and Freedom Fund. You might notice we are heavily Freedom Fund biased!
- Freedom Fund split between account type – ISAs, General Investment Accounts (GIAs), Self Invested Personal Pensions (SIPPs) and investment properties (when we had them).
- Fund split – what funds we are invested in and what proportion of our stocks and shares is in each.
You can choose which date you’re interested in and it will show you these splits for that date.
The chart is interactive so you can hover over each element and you will see a pop-up box giving you details.

How did our funds do this year?
This year we were looking at the funds we held and we wondered how they compared on performance. We haven’t changed anything and wouldn’t as a result of the fund performance alone, it’s just interesting to see.
Here’s each fund’s performance:
| Fund | % growth |
|---|---|
| Vanguard FTSE Developed World ex UK (ACC) | 13.5% |
| Vanguard FTSE Developed World ex UK (INC) | 12.1% |
| Vanguard FTSE Global All Cap | 13.6% |
| FTSE Developed World ETF | 13.8% |
| Vanguard US Equity Index Fund | 8.7% |
You can see the best performing funds were the Vanguard FTSE Global All Cap, the Vanguard FTSE Developed World ETF and Vanguard FTSE Developed World Ex UK Index Fund.
The difference between the two FTSE Developed World funds is one is an income unit and one is an accumulation unit. So the 13.5% return includes the dividends being reinvested where as the 12.1% return doesn’t include the dividends as they were paid out in cash to us and we spent them on breakfast out.
When you are building your wealth you want to have accumulation units so the dividends get automatically reinvested and your pot grows faster.
When you are in retirement you can have either. The income units that pay out dividends or the accumulation units that reinvest it and then you just sell off a portion to live off.
You might also be thinking “Hey Donegans, you have more than 1 fund, do I need more than one?” The simple answer is no, we only have these because of legacy reasons and if we were starting again we would probably pick the Vanguard FTSE Global All Cap or VT as our one fund to invest in.
10 years of data – Donegan Net Worth
These next charts show how our net-worth has changed over the last decade and the split between Cash, Valuable Liabilities and Freedom Fund. The race chart should auto play and you can see how it has changed over time, including when we sold the apartment we lived in and how that money moved from Valuable Liabilities to our Freedom Fund (investments). You can hit the replay button in the bottom left corner to send it back to the beginning and watch it as many times as your heart desires!

Have you ever heard of a waffle chart? Neither had I until Katie built this one to show the same data in a different way!
Are you ready for your first ever waffle chart? Each dot is £10,000 and the colours represent Cash (green), Valuable Liabilities (orange) and Freedom Fund (yellow). You can hover over each element to see the values.
The magic of compounding continues to grow our money even though we have stopped formal employment!
The Habits that built the Donegan Net worth
These aren’t hacks, they’re habits we’ve repeated for a decade. They turned financial stress into freedom. Copy the principles, adapt them, and watch what happens.
1. Relentless Tracking & Reflection
- Monthly finance meetings – no excuses. Even when life is busy, we sit down, eat breakfast, and review the numbers. It doesn’t have to take long but it has to be done!
- We check net worth and spending, and ask:
“What added value?” vs “What was a waste?” - Annual deep dives and now a 10-year review give us perspective. Zooming out stops panic and fuels better decisions. How to run an Annual Finance Meeting
2. Keep Investing Simple
- Global index funds. Low fee. No tinkering.
- Allocation? Our Freedom Fund is 100% equities.
- We ignore hype and headlines. Simplicity beats attempts to be clever every time.
3. Intentional Lifestyle Upgrade
- We spend boldly on experiences and environments that matter, Disney trips, great gyms, quality stays, and we cut the fluff.
- Lifestyle creep? Yes – but by design, not by accident. This is something we avoided like the plague on the way to Financial Independence but now, having created abundance, it has become the way to enjoy the wealth we have created.
- Money is a tool for freedom and fun, not a scoreboard. It gives you a target to aim for to know when you have enough to be able to stop working.
4. Learn, Iterate, Improve
- Mistakes become lessons. This year we worked out the cost of holding too many premium bonds and we will never be doing that again. Watch out for that article soon! The key is to learn each and every month / year and improve your position!
- We experiment and refine. Progress over perfection.
5. Plan for the Future
- We don’t sweat small purchases, we think in decades.
- We use our Financial Forecasting Spreadsheet to model scenarios and ensure we have enough for the life we want.
- Big decisions (dream home, cruises) are planned years ahead.
6. Make It a Ritual
- Finance reviews aren’t chores – they’re celebrations.
- Breakfast, reflection questions, laughter.
- That’s why we’ve kept this habit for 10 years. Joy makes it sustainable.
I believe with every fibre in my soul that these are the habits that have created the abundance we have in our lives and my hope is that sharing them with you will inspire you to take control of your finances.
What gets measured gets improved
You don’t have to do all these habits, just doing the monthly finance review is enough to change the course of your financial future. What gets measures gets improved after all!
Katie and I have experienced the power of this idea this week. Katie wanted to start tracking the weights she was lifting in the gym as she struggled to remember how much she lifted last time. So we got an app and we started to write down what we were doing.
The motivation and change in our workout sessions the very first time we went was insane. Yes, it took longer to start with as we learnt the app and added the exercises but the impact was that we both started to increase our weights and have consistently set new personal bests ever since.
There is MAGIC in tracking alone.
We Posted About Our Annual Finance Review… and Got an Interesting Comment
When we shared our annual finance review on Facebook, one comment really made us pause and reflect: “Why do you still do monthly finance meetings after 10 years?”
Eric wrote:
“I think at ten years, you are getting pretty close to having the option of opting out of monthly financial reviews! I imagine they are still fascinating from the point of understanding the costs associated with travelling to different locations and collecting that financial data, but I also imagine you have become so good at managing your money that these meetings could soon reach the point of becoming less of a necessity and more of an excuse to eat a delicious and fancy breakfast! But it is fun to track spending and see the areas where you can optimise. Either way, enjoy all that bacon that you’ve brought home!!”
Our Unified Donegan Response
Eric’s comment inspired us to think deeply: Why do we do monthly finance meetings? Here’s why:
- We look forward to it every month. It’s not a chore, it’s a date we both get excited about.
- Breakfast makes it a ritual. We head to a favourite café, enjoy great food, and make the process joyful.
- It keeps us calm and confident. Seeing the numbers regularly removes anxiety and gives clarity.
- We catch leaks early. Subscription creep and small oversights don’t get the chance to snowball.
- It encourages intentional spending. After years of frugality, this habit helps us embrace abundance without guilt.
- It strengthens our relationship. Money becomes a shared project instead of a stressor.
- Reflection drives improvement. Every month we ask: What added value? What was a waste? and adjust.
- We love the data. Tracking net worth monthly shows trends and keeps us engaged. Who doesn’t love charts!??
- Spending review matters. Understanding where our money goes helps us align with our values and stay abundant.
- We lead by example. Doing this publicly shows others that financial clarity is a habit worth keeping.
Do we need to do it? Probably not.
Do we love it? Absolutely.
And we believe this ritual is one of the biggest reasons for our financial success.
The all time Donegan Net Worth Chart
Every month at the monthly finance meeting Katie updates our dashboard that includes all our key numbers.
This is best viewed on a laptop or desktop! There were some elements we had to remove to get it to fit on a mobile screen.
The blue line is net-worth including the home we lived in until 2020 (referred to as 512) and the orange line is net-worth excluding the home we lived in. In 2020 we rented out 512 whilst we waited for it to sell and it changed from being a Valuable Liability to an asset and so we added it to our Freedom Fund!

The main things we look at every single monthly finance review are:
- Overall net worth and whether we are heading in the right direction. This year was a good direction!
- The change over time, 1 month, 1 year and 5 years. This helps us zoom out from monthly fluctuations
- Withdrawal rates. To help us recover from our frugal habits we look at how much we could spend with a withdrawal rate of 5%, based on this month’s net-worth. We do this to try and help us feel abundant and to enjoy the wealth we have created. You will also notice that Katie has made that dynamic so we can stress test it down to 3% and up to 6% to see what the figures are! This is not the true application of the 4% (or 5%!) guideline which says set your spending to 4% of your Freedom Fund at the point you retire and adjust it by inflation each year. You’re not supposed to re-set your 4% figure every month because by doing that you re-start sequence of returns risk. We do it to encourage ourselves to spend as we are not close to it (yet!).
What do you think of the Donegan net-worth dashboard that Katie has created? Would you add anything? Write us a comment below as we are always looking to improve what we are doing.
Enjoy the Journey
We didn’t quite hit £2.5 million this year – we were a few pounds short – but that’s not the headline. The real story? We’ve spent the last decade learning that money is a tool for joy, not a scoreboard.
Early on, we made a pact (Katie says she was “forced” to sign, Alan swears he has the signature and Katie signed willingly!) that every time we crossed a major milestone, we’d spend an additional 1% of our net worth on something extraordinary. Why? To break the frugal habits that got us to Financial Independence and make sure we never become hoarders.
Here’s what that looked like:
- At £1.5M: We blasted off to the Star Wars Galactic Starcruiser for an out-of-this-world adventure. Lightsabres, jedi mindtricks, and pure magic.
- At £2M: It was Katie’s 40th, so I organised BIG adventures for us both – Copper Canyon in Mexico, an epic Vegas fortnight, DisneyWorld, and a South African safari that left us speechless.
These experiences were reminders of why we did all this in the first place: freedom, fun, and connection. They’ve empowered us to keep spending on experiences and not end up the richest people in the graveyard.
Lesson: Frugal habits will make you wealthy, but they won’t help you enjoy it. Build joy into your plan. Celebrate milestones. Spend boldly on what matters.
Could you set a target that triggers intentional spending? Do you need more help spending or saving? We are all different!
Here are some images from our South Africa adventure to inspire you…
Past Alan & Katie Advice (If We Could Go Back…)
If we could hop in a time machine and give our younger selves a pep talk, here’s what we’d say – and what we want YOU to know:
- Get your money in the market ASAP. Time in the market beats everything. Stop waiting for the “perfect moment”.
- Don’t hold cash or premium bonds beyond your emergency fund. It’s a massive drag on your wealth. We learned this the hard way.
- Set your mortgage to minimum and invest the rest in a low-fee global index fund. Don’t rush to pay it off if the maths says investing wins.
- You’re going to be fine. Seriously. Don’t stress. Enjoy the journey. Have fun along the way.
- Work on confidence, happiness, and health as much as your finances. That’s the real wealth. Spend as much time on YOU as you do on spreadsheets.
- Track your weight, Alan! USA + all the food = trouble. Health matters as much as net worth.
- Ignore the media and fear. We lost out on nearly £100,000 in growth in 2016 because Alan panicked about Trump and Brexit. Stick to the plan. Headlines are noise.
Bonus mindset tip: Your financial plan should feel like a trampoline, not a cage. Build flexibility, joy, and resilience into it.
This is Alan and Katie from 2015. Don’t they look young and impressionable!?
Impact Report: Rebel Finance School + YouTube
This year, Rebel Finance School cost us £10,000 – and it was the best donation we’ve ever made. That money helped over 40,000 people from 61 countries take control of their finances and start living extraordinary lives.
People always question us, “yeah, yeah Donegans you are making money out of your YouTube Channel” and we are. We made £16,761 this year which is incredible and quadruple what it was last year! We should be dancing in the aisles!
What people don’t understand is that we spent over £27,000 on hosting, mailing list software, camera equipment, studies, editors, the UK tour and more.
That is how we end up with Rebel Finance School costing us personally £10,000 this year.
Why do we do this? Because helping people is worth every penny. We hope Rebel Finance School breaks even one day, but for now, we’re loving donating our resources to make a difference. Every workshop, every video, every blog post is fuelled by the belief that financial education should be free and fun.
Impact in numbers:
- £16,761 earned from YouTube revenue
- £27,000+ spent on running RFS
- Personal cost to the Donegans £10,000
- 40,000 people from 61 countries supported.
- £0.25 spend per person supporting people. Do you think this is a good investment?
Our dream: To keep giving, keep teaching, and keep proving that money can be a force for good.
This is us running Rebel Finance School 2025 from Brazil.
🍍 Our Net Worth… in Pineapples (Colombia vs UK)
Because we love playful reframes: how many pineapples could our 31 Dec 2025 net worth (£2,453,612) buy?
Colombia (Bogotá/Medellín retail)
- Retail price per kg (2025): COP 4,684/kg.
- Average pineapple weight: ~1.1 kg for a medium fruit.
- Price per average pineapple in Colombia: COP 5,152.
- Exchange rate (2025 avg): 1 GBP ≈ 5,428 COP.
- GBP price per pineapple: ~£0.95.
- Pineapples our net worth could buy in Colombia: = 2,584,765 (about 2.58 million).
United Kingdom (supermarket shelf)
- Sainsbury’s large pineapple is £1.70 (UK whole pineapple range roughly £1.00–£2.35 across major supermarkets).
- Pineapples our net worth could buy in the UK: = 1,443,301 (about 1.44 million).
Why we include this: Converting money into something tangible keeps finances fun and grounded. It’s a light-hearted reminder that net worth is potential energy for experiences, contribution, and daily joy – not just a number.
🌟 Start, Share, Shine: Your 2026 RFS Invitation
Compounding works for anyone. It doesn’t care where you live, how old you are, or what you earn. Put money in the market, leave it alone, and time does the heavy lifting.
Index funds work for anyone at the same rate. When you own the whole market through a simple global index fund, you capture the world’s growth. You don’t need to outsmart fund managers or guess headlines. All you have to do is start.
If you’re brand new, begin tiny and begin now. £25 or £50 set up today is infinitely more powerful than the “perfect plan” delayed for another year. If you’re already invested, keep feeding the machine and let compounding do its brilliant work. Just make sure you’ve paid off high interest rate debt and have a full emergency fund before you invest.
🗣 Share your wins and your needs
We want to hear your 2025 story. In the comments:
- Win of the year: What changed for you? First index fund purchase, debt paid off, ISA opened, emergency fund created, confidence up?
- Lesson learned: What did you discover about your money, your habits, or your mindset?
- Help for 2026: Tell us exactly what support you need to make 2026 awesome. Tools, coaching topics, live Q&As, deeper lessons on drawdown, tax wrappers, IPS examples, or calm‑during‑volatility scripts. We’ll prioritise what the community asks for.
💛 A personal note from us
We do Rebel Finance School and this blog because it lights us up to watch people get on top of their finances. We want to share our hard‑fought lessons and painful mistakes so you can avoid them and have a better time. That is the work that feels like oxygen for us.
This year’s tour moved us. Meeting so many of you in person, hearing your stories, and then seeing a staggering 300 people show up to the Kings Cross meetup in London was wild and wonderful. We wished we had time to sit with each of you. The most emotional moments on the tour were hearing from people who had taken what we’d taught at RFS and used it to make a true lasting impact in their lives. Some of those stories were people who’d reached Financial Independence using what they learned at Rebel Finance School but just as moving were the stories from people who told us that RFS had brought them closer together as a couple or the solo mum who told us that just knowing where her money was going gave her an incredible feeling of calm and peace of mind. That is impact you can feel in your bones.
Our philosophy is simple. Money isn’t magic, it’s a tool. Learn the skills, start now, and let compounding turn simple steps into extraordinary freedom.
This year also reminded us that small daily choices matter. Better sleep, calmer mornings, simple systems, fewer distractions. The boring stuff compounds into confidence.
Our hope for 2026 is simple: help more people take control of their money, feel calm and confident, and move closer to the life they truly want. If our tools, workshops, or words make that happen for you, thank you for letting us be part of your journey.
Anyone can do this. We believe in you, we are sending love and pineapples, and we are your biggest cheerleaders. You have got this.
✅ Make 2026 your compounding year
- Start: Open the account. Buy the global index fund. Automate a monthly amount you can sustain.
- Stay: When volatility hits, breathe, reread your IPS, and do nothing dramatic.
- Share: Post your progress and your obstacles so we can cheer you on and design the next RFS resources around what you need most.
Drop your comment below with your win, your lesson, and your 2026 support request. Let’s make this the year your money works hard while you enjoy the journey.
Frequently Asked Questions
Glossary of terms used in the annual review
- S&P500: a list, or index, of the 500 biggest companies in the USA. When people refer to “the market” they are usually referring to this list. We use this as a proxy for the global market as it makes up such a big percentage of the global market and there is way more data and history available for this index than there is for the global index funds.
- Market correction: a drop in the market of 10-20%
- Bear Market: a drop in the market of 20% or greater.
- Market Crash: a drop in the market or 30% or more. although the media use this term frequently for minor market wobbles too.
- Freedom Fund: Invested assets designed to generate income for life (e.g., global index funds in ISAs, SIPPs, and GIAs or investment properties that create cashflow).
- GIA (General Investment Account): A taxable investment account in the UK. If you’re in the US, this is similar to a taxable brokerage account.
- ISA (Individual Savings Account): A UK tax-free wrapper for investments.
- SIPP (Self-Invested Personal Pension): A UK pension account that allows you to manage your own investments for retirement.
- Index Fund: A low-cost fund that tracks a market index like the FTSE Global All Cap or S&P 500. For full details read What is an Index Fund?
- Valuable Liabilities: Things with resale value that cost money to own (e.g. the home you live in) but don’t produce income.
- Cash: Bank balances and short-term savings, including buffers for upcoming expenses.
- Debts: Money owed (e.g., credit cards, loans), an element of the net-worth calculation.
- Units: The number of fund/ETF shares you own. Tracking units shows contribution progress independent of price volatility.
- Net Worth: Everything you own minus everything you owe; we report by Freedom Fund, Valuable Liabilities, Cash, and Debts.
- IPS (Investor Policy Statement) – this is a document where you write down your investing strategy so that when times are crazy you can refer to it and stick with the plan.
126 Comments
Leave A Comment
Related Articles

Blog, Financial Independence, Save and Invest
Where do I put my money? Hello there! We wrote this article in 2025. Platform fees in the UK have changed a lot since then! Look out for an updated article coming soon.....With such a confusing array of platforms, funds and fee structures how do you ever decide where to put your money? In [...]

Blog, RFS2025, RFS2026
After every single Rebel Finance School session in 2025, Katie and I sat down and wrote notes about what we could improve for next time. We had a lot of ideas. But here’s the thing we’ve learned the hard way over the years: our ideas are not as important as what actually works for real [...]

Blog, Financial Independence, Keeping Track, Save and Invest
Where is your net worth? Most people have no clue what their net worth is, let alone where it is. Your net worth is the total of what you own minus what you owe. Your split is the shape of that number. How much is in your Freedom Fund? How much is [...]

OUTSTANDING.
Gary you are amazing. Love you.
I for one, am so grateful for the 25p you spent on me. I did the 2024 course on catch-up in Feb/Mar 2025 during a break from work and then joined the 2025 course to consolidate my learning. I opened a Monzo account to track spending, moved our emergency fund to premium bonds to free up tax free allowances for S&S ISA. Paid off my car loan. Then took the plunge and moved all of our DC pensions into Vanguard Global index funds just at the low point of the Trump slump … this was very fortunate indeed but OMG what a difference you have made to our lives. The end of December 2025 finance meeting showed that we are now £191K better off than at the end of Dec 2024 !!!! (I had backfilled the figures for the 3 previous months in the tracking spreadsheet when I first started). As a result, I have chosen not to go back to work but instead to take some out to help my elderly parents (time I will not get back). I am also volunteering as a puppy raiser with Guide Dogs for the Blind. I have opened a shop to sell my woollen creations which means my hobby is fully paid for (shout out to Rebel Business School for lessons learned there). 2025 has been a huge success for us and my husband will also join me in retirement in the next 3-4 years or so. Thankyou doesn’t seem enough, but please know that you have made a huge difference to our lives and that of my parents xxx
Inspiring and honest
Thank you Chris!
Thank you for this absolutely amazing update. It’s so inspiring, holds so much data but it is broken down and explained so clearly and I LOVE Katie’s charts! I am one of the 40,000 you impacted in 2025 and you were a godsend, I can’t thank you enough. Your positive impact on so people’s lives is incredible!
I will open my first Vanguard fund this month and just wanted check with you re this comment about the fund you might pick if you were starting again “Vanguard FTSE Global All Cap or VT”. The Vanguard FTSE Global All Cap is the red box in your Fund allocation chart correct? And what is VT?
Thank you very much for your answer and wishing you both a fantastic 2026!!
Loving the smiles you have brought me with your Rebel courses. I now have some Financial Joy – before an oxymoron, now a match made in Rebel Heaven!
Keely you are amazing. I am so glad you are smiling and having financial fun! please let us know how you get on! Katie and Alan
Thank you Alan & Katie for all you do for us!
Kudos on an excellent article. It is certainly thought provoking in many ways. If that doesn’t inspire people, I don’t know what will. I admire you for sharing your figures so openly in public (as you know in the UK, it is very common place to shirk at this). It’s refreshing to take a peak under someone else’s bonnet for a change! I really like the “Tableau Public” app you’ve used to compile your data. May even have a play myself :-). Out of curiosity, what month & year was your freedom fund at when you knew you’d reached FI? Other than hard numbers, did you use someone as a soundboard to get the encouragement to jump?
Absolutely excellent article guys, as if it would have ever been anything else 😉
I can’t tell you how grateful I am to you both! I only found RFS in March 2025 and binge watched the whole of the course in a few days, then I did the course in ‘real time’ when the new course started.
My husband and I have always been ‘savers’, and I’ve tracked our spending and savings every month for quite a few years now so I’ve known exactly what was coming in and going out. I ‘invested’ in an S & S ISA for the very first time in April 2025 (after binge watching the course in March) and opened our very first SIPPs in May 2025. I wish I had a time machine as I’d have moved all our money on that first transfer in April but I was a little scared and slowly moved our ‘cash’ over a few months….. and probably ‘lost’ a few thousand by doing so 🙄 ( I know it’s not really a loss but you know what I mean 😊). I haven’t done an annual review yet as I haven’t been investing for a year….yet, but I can’t wait!
I love a spreadsheet as much as Katie (even though mine are definitely not as pretty as hers 🤣). Last night I decided to create a spreadsheet to see how much I’d be ‘up’ if I’d continued to keep saving in cash (tracking each interest rate change) compared to how it has changed now I’ve started investing. If I’d continued saving in cash I’d currently have gained £6500 from April to now (Jan 26) which in past years I’d have been happy with! My investments have increased by £31,000 in that time!!!!!! I totally understand that this can go down aswell as up and I’m fine with that (I think 😉). I’m so excited to be on this journey, and I thank you both with my whole heart. I genuinely think you have changed my life….and I’m bringing my husband along for the ride (as long as he behaves himself)😉🤣🍍
Thank you both so much for this, it is hugely inspiring to read and made me even more excited to build my freedom fund in 2026! I have sent your course to SO many people and will continue to do so!
A refreshingly open account of your financial life, much to take in on a personal level. I found RFS just in time as ‘retirement’ to reall life starts very soon. Having done the course now I’m still curious to know at what point you would switch out potentially from 100% equities?
Just wanted to say thanks. I discovered you guys just one month ago. I’m about to start Wk 6 of your course and have already learned so much. At nearly 50 I’m playing catch up but I feel positive that I can make some progress and be in a much better position than I might have been. And when they are receptive (sigh) I can teach my very young adult kids some of this. I wish I’d known it at their age. You are an inspiration! Truly. Let me buy you breakfast some time!
Thanks Alan & Katie. A great read & totally inspiring. Do you mind me asking what the monetary value of your investments was in 2015 at the start of this ten year period?
Well deserved. Thank you for all that you have done for me and people like me.
You are loved.
A brilliant and inspiring read!
Love this! Any plans of bringing FI Chautauqua out of retirement? I think it’s time :)
I only visited Columbia for a day as that was the final destination after my sailing trip from Panama through the San Blas Islands (highly recommend this if you haven’t already done it!) and I have never been to Argentina so I think they would be great locations for it lol
Very good. Well done both of you.
There’s so much good in you two to share this as well as RFS, thank you. Here’s to a healthy happy future for all!
A brilliant and inspirational article. We do our monthly finance meeting but I think it is time we made some improvements.
You guys are awesome and inspiring ❤️
Thank you!
What an amazing article! Thank you. I have shared it far and wide. I am also FI (similar numbers to you but just me!) and it wasn’t until I did RFS that I realised quite how FI I was and that I could ditch my IFA. Mid 50s, no kids, adorable partner with his own generous DB. I am listening to the podcast Human vs Retirement a lot to try to encourage me to spend more and give money away to loved ones and charities! I like the idea of spending 1 per cent for reaching milestone amounts or milestone ages – will use that one in 3 years when I hit 60 and force myself to spend £20k+ on an amazing experience for us and maybe match that with a further 1% for charity depending on what portfolio value I have reached!
Thank you for your dedication, and hard work helping financially educate others. It can be truly life-changing!
Having absorbed a lot of learning in 2025, I had great pleasure in being able to kick off my 2 Sons’ investment journey in a low-cost Global Index fund.
Having shared a document of important information, and links to useful articles (including RFS), I’m hoping they’ll see the benefit of regular investment in their future, and compounding over time.
I desperately want it to “Click” with them, but I suppose you can lead a horse to water, but you can’t make it drink!
I’ll keep on dropping little gems of info along the way. Hopefully something will land. 🤞
Miss you guys!!
GRAHAM! Holy shit. Wasn’t expecting to see you in the comments. LOVE YOU. Miss you. Let’s hang out some time!
LOVE this post. I was one of the 40,000 in 2025 and it changed my life. Thanks for being so generous and transparent – and keep on enjoying life!
Jennifer. THANK YOU for posting and replying. This made our day! Sending love. Katie and Alan
Quite simply, life changing!
If it wasn’t for stumbling across Alan and Katie and attending RFS in 2022, my (and my family’s) financial future would be very much different than it is today – Just passed £120k in VAFTGAG and on target to meet my freedom number in the next 2-3 years.
Thank you for your enthusiasm and for keeping this course free. It’s a rare thing for someone to give freely their time and learning experiences so that others can benefit.
Mike it is our pleasure and I am so inspired that you have done that! 2-3 years and dome good growth and progress. LOVE that you are doing that. It is our pleasure to have been able to help along the way and thank you. Hope to get you meet you in the future somewhere around the world. Love Katie and Alan
I found you in 2025 and am so grateful. We are lucky to work in financial services and have established pensions and a vague financial plan but we have added huge clarity and confidence in 2025 and retirement plans are designed and the crystalisation is afoot.
I feel clearer and every frivolous purchase is reviewed. Financial goals have made me feel like i am less on the hamster wheel or at least it is for a finite time.
Thank you Alan and Katie for all you do for the Rebel community. Thank you for sharing snippets of your personal life along with the nuts and bolts of building your Freedom Fund. It helps us to appreciate you are real people who have done the hard yards, and so can we. Thank you.
Tina, what a lovely message. THANK YOU. That makes us want to keep doing. Thank you and have an AMAZING 2026! Love Katie and Alan
I’ve hit the 1/2 mill dollars this F meeting :]
Hi both, I just wanted to add my thanks for all you do, you have made such a difference by explaining the simple steps to managing finances and how straightforward investing can and should be. I have just retired (end of 2025) and over the last 5-6 years I (we) have adopted many of the ideas you discuss – it’s been transformational and confidence building in terms of deciding to retire early. The subject of investing/pensions is deservedly gaining wider media attention and perhaps even compounding itself judging by your Y/T numbers! Here’s to 2026…!!
Martin, what an awesome message and I love how you are using it all and gaining confidence. You are using it in retirement and I love that. That is the whole purpose of this is to buy back time to have fun and do things and make things happen. Thank you for commenting. Please let us know how you get on and sending huge hapiness. Alan and Katie
Thank you for sharing your knowledge and tools with us. You gave me the confidence to retire this year age 54 after hubby retired in 2024, and we’re loving it!
Andrea, that is AMAZING> I love it. Congratulations and please have some adventures for us. Hope to meet you around the world. Sending happiness. Alan
So inspiring Donegans keep up the great work!
Lee you are Awesome. Thanks for commenting.
Wow you both are super detailed in this post! Thanks for sharing your info.
Happy new year!
Mahnosh it was quite detailed wasn’t it! lol. We had to make sure we included everything and you should see the lenght of our annual review. it has been interesting. Thanks for reading and sending you happiness. Alan
Donegans – thank you for your transparency and all that you do! I started 2025 by getting DOGE’D and thinking it was the worst possible thing that could have happened. One of the best things that came from the experience was someone suggested your course (which I had time to take since I wasn’t working!) and wow – I learned so much and have made so many positive changes to our finances. We gifted our kids with small starter stock accounts this holiday so they could learn about the power of compounding and practice ‘investing’ so they don’t wait until they are middle-aged to learn what I’m learning. (And I’m implementing monthly meetings with them!) Thank you for helping me turn my 2025 lemons into lemonade!!
Rebecca, HAPPY NEW YEAR. Thank you for replying and I am so excited that you message. Love the story and so glad you are here with us. Sometimes things like that have to happen for us to change course and it sounds like a lot of good has been created by you from that experience. You are amazing. I so hope we get to meet in the future for a coffee somewhere! Alan
Great read. We started last year and having mastered the basics and beginning to regularly invest our gap we are now watching 2025 to get our retirement model set up and working out what is the right balance for us between freedom fund Vs having the experiences we want with our kids while they are still young and don’t think we’re too embarrassing to hang out with!
Thank you for your honesty and transparency, it’s so refreshing! I really need and want to take the plunge into investing this year, even though I don’t earn much. THank you for running the Rebel school, I am going to go back over the course again this year. Do you do individual consultations? Or have any recommendations for Independant Financial Advisors? It’s so hard to know who to trust! Thanks again, you’re travelling life is very inspiring :)
Thank you for all the info. The one question that kept humming in my head while reading was: If you are all in stocks, what would you sell to live on during a long market downturn? Of course you would spend your emergency money first but what would you do if the market downturn lasts longer than your emergency fund reserves?
Hey Donna, the 4% rule takes care of that. it is designed to allow you to spend even if things are down so we would just live off the portfolio trusting the maths and focusing on what we can control like costs and maybe increasing income if the downturn was years long. Did you see the end of this year’s week 10 where we did the numbers for retiring into the 2008 great financial crash and whether the 4% rule worked? Sending happiness and does that help? Alan
I thought the 4 percent rule came from testing 50/50 to. 75/25 stock/bond portfolios. How does history show the 4 percent rule working for a 100 percent stock portfolio?
Thank you for your honesty and transparency, it’s so refreshing! I really need and want to take the plunge into investing this year, even though I don’t earn much. THank you for running the Rebel school, I am going to go back over the course again this year. Do you do individual consultations? Or have any recommendations for Independant Financial Advisors? It’s so hard to know who to trust! Thanks again, you’re travelling life is very inspiring :)
Hey Lucy, we have the same problem it is hard to know who to trust. What would you want to ask them? What are your questions?
Love that you want to get going. Now is always the best time to start no matter how small!. Alan and Katie
Thank you, Katie & Alan, for your kindness, transparency, wisdom, and generosity. Thank you for leading by example. Thanks for showing that even in a traveling lifestyle you are prioritizing health & fitness. Thanks for being honest about needing to change from frugal to a more generous budget for yourselves. It’s all planting seeds within your ‘tribe’ around the world. Enjoy your 2026!
What a fantastic article – honesr, enlightening, thought provoking and inspiring. Thanks so much for sharing and giving us the tools and knowledge to make financial success attainable!!
Hey guys, loved this update, including the detailed charts!! I pulled the trigger in March 2025, so your post really resonated with me. I’m working through the shift from saver to spender but it is tough! Are you guys in Medellin right now? I actually bought an apartment in Medellin and I’m here until mid March! Would be great to have lunch or grab a coffee if you are still in town!! :)
Wow, what a summary – inspirational.
I ‘found’ RBS in December last year and did the first 4 weeks of the course. We only had a car on PCP and a mortgage at the time but our spending habits were out of control (always in our overdraft even though we earnt enough to cover us). We have always invested into work shares and husband has a credit union too.
Fast forward to the end of the year and we are debt free (except mortgage), have an emergency fund and a 2026 plan (a very ambitious goal of £26,000 saved in EF, sinking funds (which will be spent) and investments. If all works out ok we should have £16,000 left at the end of the year. Also going to start putting £100 into a global index and then up that amount from the start of next year once we have our 6 month expenses saved. Thanks for highlighting and supporting so many of us :)
wow just wow
Thank you 🙏🏻
Absolutely worth the investment in RFS, thank you for making that investment in me, and always being a huge inspiration!
Win of the year: What changed for you? I realized I needed to go back to the basics, brought all my disparate accounts together and invested getting my portfolio overall to a 12.70% growth and ~$775,000
Lesson learned: What did you discover about your money, your habits, or your mindset? Totally agree on the bonds and cash, I would have been better keeping that in a high yield savings, as those accounts only had a measly 1.2% growth rate over the year before I consolidated and coverted.
I stumbled across an RFS YouTube link back in 2023 and have been hooked sorting out my finances ever since. The course made so much sense to me and now my pot has gone from under 100K (which sounds a lot, but not amazing from 30 years of work) to 250K. So I am now on target for a decent amount in retirement. The MBEs are richly deserved.
Participating for the first time in 2025, your tips have revolutionised our finances, especially with me taking early retirement following a redundancy in August. My wife will be able to retire at Easter, as a result of our newfound financial confidence!! I have invested pretty well previously, but your advice has given me/us a step change upwards. Things are so much simpler, too.
Life changing for us, as we approach our 60s; more importantly, life changing for our three children, who are in their early/mid twenties and are beginning to follow your guidance, which I pass on to them…..busy lives!
As for you guys, your altruism is truly inspirational and I will use it as fuel, as I look for volunteering roles in the Hertford area this year.
All the best to you and all the Rebels for 2026!
Truly Fascinating !..:-))…love the eric reply..where do i send my 25p RFS client contribution…i like to buy my pineapples in Aldi at 98p each….now grow my own..to help make my magic money compounding FIRE fund go even further….love you guys…have fun..keep rockin it…FIREMAN..XX
Absolutely life changing! I have only been a member for 4 months but I love being part of the Rebel community (cult), and talk to anyone and everyone about it. After being so inspired, I presented an INSET at my school, to inspire other members of staff, and who in turn have started to take everything on board. We are all at the start of our jouneys, but it is great to have a micro community at work. Lots of differences with pensions etc. unfortunately, being from Jersey, so many things are not relevant, but the life lessons are the same and the excitement of learning how to invest in our future selves is just so liberating.
Humbled that you both generously do the good that you do, making an huge different to countless, and with such honesty and transparency. Nga mihi
Love this update. So many wee pearlers amongst it that resonated with us. Can’t wait to hang out in 2026! XXX
After a hard first week back to work and the rest of it after Christmas, I read this article and I’ve started watching your 2025 course again. You have reminded me why I’m here + given me the motivation I needed to just get on with it all and build that freedom fund!! Thank you so much for your time and effort to help us all, we are so grateful xx
After coming across your course last year I took the plunge and moved my pension from Aviva to Vanguard.
As of today it is up 29.3% since last March.
A big thank you.
Happy New Year! You guys are so awesome and transparent and wonderful teachers!! Thank you for sharing your story and your knowledge with us in a light and understandable (& FUN😉) way!! Looking forward to meeting you someday when you come to the Tampa, Florida (USA) area. The impact you have had on anyone who has been a part of the Rebel Finance School is tremendous!! Keep up the good work!
Happy New Year! You guys are so awesome and transparent and wonderful teachers!! Thank you for sharing your story and your knowledge with us in a light and understandable (& FUN😉) way!! Looking forward to meeting you someday when you come to the Tampa, Florida (USA) area. The impact you have had on anyone who has been a part of the Rebel Finance School is tremendous!! Keep up the good work!
Great article, thanks for spending the time to create this to share. Love the graphs :+)
Many thanks to you Katie and Alan, We and our adult kids have joined the Donegan revolution. Our kids are just starting on their investment journey and I’m glad I came across RFS to share with them at their younger age so many years to invest. I managed to retire early at 56 before I discovered RFS ( just think how much earlier I could have if I’d seen RFS earlier :-) I’m finding my biggest issue is stopping saving and starting spending, very hard habit to break. All the best for 2026 from NZ
Thank you for continuing to share your numbers and be an inspiration to everyone. Congratulations on another awesome year!
I found you in 2025 and am so grateful. We are lucky to work in financial services and have established pensions and a vague financial plan but we have added huge clarity and confidence in 2025 and retirement plans are designed and the crystalisation is afoot.
I feel clearer and every frivolous purchase is reviewed. Financial goals have made me feel like i am less on the hamster wheel or at least it is for a finite time.
Thank you for the epic amount of effort you both give away to us for free. I’ve binged your YouTubes over Xmas. I work in HR in the hospitality sector and am publicising RFS to our staff. I plan to review our default workplace pension offering too as I have a far better idea of what I’m looking at now. Your session on ‘build an incredible life’ was particularly relevant to me. I don’t really know what I want from retirement, I think I have been assimilated by the Borg! Time to put some effort into thinking about my own life outside of the office and what I might want from the future! Keep shining Donegans!
Hi Katie and Alan,
Thank you for this!! Really helpful to me! Hopefully I’ll meet you in Aotearoa / NZ this year, or if you’re around UK in May or summer..
My biggest wins this year – I got my husband on board with our finances…and he got me realising we would be ok. That I’d actually done well with our money despite not much knowledge and no useful family money discussions growing up.
Learning about shares, the ease of low fee ETF etc and importance of monthly balances ( still need to improve on that!!) has been life changing.
We can now do finance speak and I’m planning on retiring this year from active service as a midwife ( in various roles),after 31 years! I love my current research role so that will be my last then I can dabble at my leisure 🎉🎉🎉
This has also helped my eldest daughter get her head into future savings and shares – on a low income and it doesn’t matter thanks to your teaching. She’s always been mindful and now she’s future planning.
Thank you!
Nothing to do with finance, but interested in the health aspect you mentioned in your blog. Just out of interest, what supplements are you taking?
Profound & Prolific, you both are truly a priceless treasure 💎 Ty for sharing your wealth of knowledge, experience & love wt us all. It must feel good to be loved by so many ♡ All Our Love from Lpool! Danielle xx & Carl xx
Just had to leave a quick message to thank you both for all your efforts and for sharing so much information in an easily accessible and entertaining way. I retired early and the RFS has been a game changer in helping me better understand pensions and investments. I’m currently nagging our daughters to get their personal finances in order for the long term, but am sure they’ll thank me in the long run. Thanks again and keep up the good work !
The work that you do is just brilliant and so inspirational! Thank you for sharing your knowledge. I have very little in the way of financial funds, and it’s been that way all my life, despite working since I was 16! So for me 2025 was the year I had a really good look at my spending habits and began focusing on net worth, and the need for an emergency fund. My €4k debt is almost clear, so this year will be the year I create an emergency fund, and start investing! I have also started a little side hustle to help make things happen! Thank you so much to you and your team. You are amazing!
This really is an inspirational read. Thank you for being so open about everything. I love your energy, optimistic and positive outlook on life and love that you emphasise the importance of working on health and happiness as well as finances.
Hi Both, How did you go from a portfolio of 290k in 2015 to 525k in 2015? That is a phenomenal year on year increase!
You mention a 2025 spend of 100k, would be interesting to see an expenses by year chart in similar vein as net worth by year.
I note that 100k spend on a 2.5mm portfolio is bang on a 4% withdrawl rate.
The portfolio looks a little odd, with a lot of overlap, but the ‘historical’ explanation is understandable, simplifying it may incur CGT, but the majority is in ISA and SIPP so wouldn’t be an issue for those accounts. Are you not tempted to consolidate to whichever has the lowest TER? Oh, and 100% equities is gutsy for sure, but I half remember you have invested your way through substantial down-turns before, so very possibly fine. I imagine your spending is highly discretionary also, so you could make large adjustments if you had a bad run of it.
Very interesting ideas around spending 1% of net worth at specific milestones, I haven’t seen that suggested before, original novel thinking.
I think spending 27k of your own money providing a charitable financial education service is deeply commendable.
Thank you, Alan and Katie, for this article and everything you do and teach! We’re coast-retiring in 7 weeks’ time and until RFS had no idea how close we were. Value-based living ❤️
So apologies in advance for the language but
This article is FUCKING brilliant !
Thanks for your hard work putting it together.
Our 2025 win was successfully executing our first partial year of FIRE. My husband quit the end of April (I’ve been done for four years this month) and here we are in 2026 and we’re not bankrupt yet! ;-) I also got to help with RFS and see the sausage being made and it was delightful to be able to help others. 2026 will see us do our first Roth conversion and take the kids to Europe for a month this summer without breaking the bank!Thanks for this fantastic article, for all you do, and I can’t wait to see what the future holds!
You guys have changed my future enormously! Thank you both for your endless enthusiasm and dedication to the betterment of peoples finances and life choices.
It was fantastic to get a chance to meet you both in Glasgow last year, I bore anyone close to me with my new found financial passion, I LOVE IT!! 😁🌟
Hi & thanks Katie and Alan. It’s fantastic that you share this so openly – it really is inspiring. Can you help me understand where you take your living expenses from? Assuming you take the 4% per year from one of your 3 funds, but you can’t access your pension fund for many years yet, it leaves the ISA and GIA funds. Do you take equally from each of those, or do you prioritise one of the funds first? GIA withdrawals will trigger capital gains tax, so I’m curious about how you decide?
Hope you hear back from you. Keep up the amazing work and the awesome lifestyle – you deserve to be millionaires!
WOW GUYS. Katie – cmon – you must be feeling pretty stoked with these charts! I think Alan hit the jack pot marrying you, chief chart developer (and many more hats too!). Am going to run off and try to create my own IMMEDIATELY.
It is so hugely valuable to see and explore the concepts of RFS with some real data and in so many different slices. This is nothing short of inspiring. Has to be the most well-reported FI journey out there. For a cautious and analytical brain like mine to be able to see all the steps you faced and imagine those downturns etc. makes it all so real and all the more inspiring. And as always, its the real life ‘money is a tool’ context on building a good life instead of bean counting! Move to NZ – i think you fit in!
This was so AWESOME that I had to send you a voice message to say thanks for sharing. You guys are our inspiration !!!
Hey team, awesome review! One thing I noticed, the S&P500 return in your table seems to exclude dividends – was that intentional?
Also I wondered whether you’d looked into why your funds underperformed the S&P500. That seemed strange to me since they include international which outperformed the SP500.
I set a 2026 goal to start a Rebel meetup group in my little home town (in New Zealand). We had our first meeting just yesterday (just two of us), posted about it on Facebook… and our group doubled to four overnight! My other goals are to encourage at least two friends to do RFS this year, and to attend KiwiFI in Christchurch in November.
Thank you story and such transparency. I look forward to joining a course this year if there is one. Can I ask – how didi your freedom fund grow so massively in 2016 and what was that invested in at the time isa? pension? or something else. Just thinking through the 20k isa limit1
Thank you so much for this email and the detailed information and honesty, it’s very much appreciated and helps me remember to apply the teachings from the RFS throughout the year between courses. It makes a difference and keeps me on track, as well as offering a boost on cold winter English days! Take care and enjoy life! All good things for 2026 to you both!
Sharon, what a lovely message and thank YOU. Stay warm in the English winter. it can get cold out there and please stay in touch and let us know how you are getting on! Sending happiness. Alan
Thank you Alan and Katie for all your guidance this year. I started my to journey to FI exactly one year ago and you have been inspiring me every step of the way. Thank you!
Malgorzata I LOVE IT. Nice work getting on with your investing and being on the path! Stay in touch and let us know how you get on! Alan
I’m a Polish guy living in the UK. I signed up for one of your events in London, but fear got to me and I cancelled. Now I regret it. Thank you for what you do. I read and watch all your content from start to finish. I often recommend you to my friends, even though it’s hard to break through and show people that they can step off the treadmill and regain their freedom. I’ve been on the path to financial independence for the past two years. I’m 46, with a wife and two children, and if everything goes well, I should be fully financially free at 57. Better late than never.
Robert, better late than never exactly and you can do it. I am so excited for you that you are eon the path and investing and working on it all. I love it. And maybe we will meet another day when we are back. Sending you much love and happiness. Alan
loved the articles. especially thought the waffle graph was awesome.
All the best for 26 ,Phil from nz
Hey Philip, the waffle chart is so different isn’t it! Thanks for writing back and maybe see you in NZ later this year…. Alan
I just love this post so much detailed information and down to earth inspiration! With so much easy to follow methods, such as the net worth sheet. Great stuff! Looking forward to joining the rebel finance school incarnation again this year(like everyone else I loved that investment interactive episode with the sharemarket roller coaster both fun entertaining and so interesting!!) Have a fabulous 2026 Alan and Katie :)
Ellen, that is so cool you joined us for the course this year! Thanks for reading the article. We wanted to show what we did so everyone can see and try and explain it all! Happy New Year! Alan
Fantastic and detailed article that is really valuable. Love your recent You Tube Shorts about IFA’s and how they make their money. So many people I met and know seem oblivious to the cost of their advice and effect on their finances. Your course feels to me like the life education we are all missing. Go Rebels!
Mike, the impact of fees is HUGE and I don’t think anyone understands which is why the industry gets away with it. We are starting to reach more people and help them!. Thanks for writing back and if you ever need it send Katie’s impact of fees tool to the people you know.. https://rebeldonegans.com/finance/resources/fees/ Alan and Katie
Absolutely lovely, informative and very very very helpful article. Thanks once again Donegans – this has completely altered my outlook on finances, and slowly but surely I feel I am gaining control of them rather than them controlling me.
You have turned me from clueless to committed.. I can honestly say this is the BEST thing I have ever done for myself.
At the beginning of 2025 I was of the thought that in retirement you could live off your state pension. I didn’t know what my outgoings were, was in debt, and as a 59 self employed solo parent lived month to month, feast or (more often) famine.
Now I know where every penny goes, have paid of all debts, sold a large percentage of my belongings and as of Friday sold up and downsized my home, freeing up a (to me) large sum. I have opened a SIPP, paid my first £20k into S & S ISA and invested rest in GIA ready to do same in April.
I am on a mission! And it’s all thanks to you..
What a fantastic article. Thank you both for the amazing work you continue to do in this space. We held our first whānau (family) annual finance review with our boys who are 9 and 11 years old. It was a brief annual finance review but at least we did one as a whānau. My eldest goals for the year include buying a house (love the aspiration) and travelling to a place where there is snow during our kiwi summer. My youngest’s goals include travelling to Indonesia and Japan and reading all the volumes of an anime series. I have also started tracking their net worth, one has a net worth of $18k and the other a net worth of $15k in ETFs, Kiwisaver and Whai Rawa. Wins for 2025 include completing the Rebel Finance course and working on our individual and whānau vision. The key lesson is about my mindset and ensuring that I listen or read content about designing an extraordinary life for myself and my whānau and taking action. I’ve been sharing that with my boys, especially the concept that we can learn anything. My 2026 support request is whether there will be an updated Extraordindary Life course. Actually, it doesn’t need updating as the content is stellar! Wishing you both a fantastic 2026 and hope to see you at the KiwiFI event.
Charmaine what an amazing message. I LOVE IT. Congrats no doing that with your boys and tell them I LOVE their goals. A whole anime series? Whilst in Japan! That is epic. I love that they have trackers too. This is so impressive. ANd yes to hanging out at the KiwiFi event later in the year. That would be awesome. Happy new year and please keep us up to dat on how things are going! Alan and Katie
Hello to you both,
I was introduced to the course last March and within a couple of weeks had binge watched all the 2025 episodes – and I am so glad I did! We’re due to retire in about 7 years and thanks to you I now know where our money goes, how much we spend monthly and how much we need to retire. I am also now wisely invested, have invested for my son and my husband has promised to watch at least the investing and retirement episodes. Oh, I also loved your Extraordinary life course! We have also changed many spending habits and continue to do so. This article acted as a bit of a life coaching session and positivity input from you both, which I really need right now, thank you! As well as being very useful – I’m now planning my yearly finance update in March. Nearly forgot, I was also excited to successfully introduce your course to someone I know, who was literally about to contact a dodgy financial advisor! She has built a freedom fund and wants to meet to chat about all things finance. I met you both in Brighton in 2025 and hope to do so again in the future – love, peace and pineapples to you! (Ps I love my Pineapple bank note!)
Love this blog and the RFS, so many lessons learnt, so many more to come!
Thanks Mark, we have so much fun creating it. Thanks for replying. Alan
Hey Guys – Fascinating read, very inspiring. We are going back through the 25 course now and making lots of positive changes.
Can I just ask, the animated graphic showing the 3 pots over the 10yrs is fab. But it shows massive growth in 2 yrs, £425k in Dec 15 to £969k in dec17, surely that wasn’t all market growth etc?! I would love to find out more about how your net worth more then doubled like that in 2yrs! Appreicate that might not be an answer you can share though!
hey Ben, there were many reasons for that growth, Katie went contracting and tripled her income, I was growing a business and one of those years saw 30% growth in the market at the same time. it was a crazy period and all those things came together as we focused on growing our pot aggressively. We also were super focused on expenses and we had a HUGE freedom rate for that period with nearly all our money heading directly to investments… Does that help? Thanks Ben! alan
Amazing, thanks for the reply! Appreciate you guys!
YAY! Our pleasure
Amazing article! I have binge watched the 2025 course on You Tube and my mind has been blown by what I have learnt! Your approach is truly life changing. I only wish that I had found RF sooner. I am 57 and recently retired with a defined benefits pension. My wins so far from following your course are debts sorted, emergency fund set up for 6 months worth of expenses, sitting in cash ISA, maxed out for 25/26, with acceptable rate of interest and very shortly, will be opening a S&S Isa for 26/27 with a lump sum and automating monthly payments! Other wins include my husband opening his first ISA, along with both my adult sons opening a LISA, cash ISAs for emergency funds and a S&S ISA for the new year. I am also currently working on SIPP options, starting in new tax year and husband will be looking at increasing his pension contributions to his work place pension. One final win, both my adult sons are now more educated about wealth building , starting early, maximising tax wrappers and keeping it simple with Index Funds. For the new course for 2026, I would recommend some more input on GIAs and pensions. Having taken my tax free lump sum amount, with a decent residual monthly pension, I am still not clear on how much if any, I can put into a SIPP per year for the next 10 years to bring me to my State Pension Age of 67. Also, some input of building generational wealth in the most tax efficient way!
Thank you so much for sharing your ‘toolkit’, it really has been and will be, life changing for me and my family. I will definitely be signing up for the 2026 course as well!
Great blog. I’m one of the newbie investors. Saved all my life and newly retired. I knew nothing about the stock market until I finished the RF course in January. I invested in February and my investments have been a sea of red ever since. Currently down 5%. I don’t think You can predict the emotional impact of volatility until you experience it with your own money. I admit for the first couple of weeks I sat on my hands to stop me panic selling. The fear of losing it all is very real. However, I am still here. Still invested. I have a cash buffer, emergency fund and a ten year plan. This morning I put more into my new SIPP. Keeping the long term faith 👍🏻
Abi, Congratulations on investing into your sipp. You got a 7% discount which is AMAZING. And thank you so much for writing. We worked so hard to prepare people for volatility but you are right, there is nothing like living through it, especially when you now know what is happening and track the numbers and can see them! Volatility was there before but most people were blissfully unaware of it until our course! LOL. Thanks for writing! Alan
“Don’t hold cash or premium bonds beyond your emergency fund”. How are you calculating your emergency fund requirement?
Hey Bob, we calculate it as 3-6 months of lean expenses in the accumulation phase! Does that help? Alan
Can I ask, in terms of paying the minimum on a mortgage, is that because the growth on investments might be around 10% and the interest rate on your mortgage is hopefully less than this? We are juggling maxing out our payments but maybe we had the wrong strategy???? Gahhhhhhh
Jodi, yes, that is the basic maths.
If your mortgage is 3%, 4% or maybe 5%, and global equities might return 10%+ over the long term, then investing can come out ahead mathematically.
But two HUGE caveats:
1. The mortgage return is guaranteed.
2. The investing return is not guaranteed and will be volatile.
That is why we use the rough guide:
– under 4%: probably minimum payments and invest the gap
– 4% to 6%: personal preference
– over 6%: strongly consider paying it down faster
So if you’ve been maxing out mortgage payments, it’s not “wrong”. It might just not be the mathematically fastest route if the rate is low and you are comfortable investing.
Have you done the course before? the investing weeks are really going to bring it to life for you…
Question for you: what interest rate are you paying on the mortgage?
Thanks for commenting.
Peace and pineapples.
Katie and Alan
I’ve scoured the website to find an answer to this question. I’ve found others who have asked but can’t find the answer! So:
How did you get from Net Worth of c£430k in 2015 to c£690k in 2016 and c£970k in 2017 (not by investment returns alone!)?
Second question (not so important, just interested and might have misunderstood):
In your “Donegan Net-worth 2015 to 2025 -Each circle represents £10,000” you Valuable Liability in 2015 is £135,762, whereas in you “All time net worth” chart the implied value of “512” is £230k.
Thanks for the insights!
David
Hey David, thanks for the question! love the detailed looking at the numbers.
The 2016 was the start of a huge impact on our net-worth as you spotted and three things happened at once that year than changed everything for us:
1. Katie left her job as an actuary at Deloitte and went contracting. that tripled her salary and reduced our expenses as she didn’t have to commute to London. This was huge as our costs stayed the same
2. The market went crazy that year and then fund we were invested in The Vanguard FTSE Developed World Ex UK went up by 29.33% . 30% extra in our freedom fund in one year blew our minds!
3. My business started to do well that year and we earnt more my side as well..
Those three things were the start of the big increases you saw and it was a combination of keeping costs low, massively increasing income and stellar market returns. We were SHOCKED at what happened that year and it just sped up from there with compounding taking us further and further every year…..
One 512 was our flat that we lived in, in Basingstoke. So that was a valuable liability and we had a net-worth with and without home we lived in at that point!
Sending happiness and did that clear it up a bit?
Alan
Hi Alan
Thanks for taking the time to reply, that’s helped my understanding of your numbers, although also raised a few more questions!
Knowing that Katie trained as an actuary explains the spreadsheets, etc 😊
I now understand the 2016/2017 part of your journey. Thanks 😊
I’m still a little confused about 512 but I think the clue might be in your mention of your flat being “One 512”, possibly implying that the flat was one of a number of things included in your 512.
I’ve concluded that your 512 includes your Valuable Liabilities (varying between £135,762 in 2015 to £178,914 in 2019) plus nearly £100k in cash or “other”.
Enough of my analysis, although I have a separate question on investments later!
Thanks again
David
Hey David, we owned three flats in total. 2 were investment properties. 428 and 528 Skyline Plaza, Basingstoke and the one we lived in which was 512 Skyline Plaza. Talk about concentration risk! lol. And yes 512 was our valuable liability or primary residence! Sending happiness. Good morning. Alan
Hi Alan
It’s too hot to walk the dog so I’ve spent the morning replicating your year-end numbers since 2015!
I wonder if you recall why, back in 2016, you increased your allocation to your US Equity fund, rather than just add to your Developed World ex UK, which is dominated by US stocks? Maybe you were just very keen on the US but it doesn’t seem to fit with your diversification philosophy?
The data suggests that in 2021 you had a brief foray into an Emerging Markets fund. You sold in 2022, so I guess you didn’t enjoy the experience?
Thanks again for a great year-end report.
David
David wow! you spotted some good bits there. Good morning. Yes I remember. When we first started invest in 2015 we had read the book Money Master the Game by Tony Robbins. Don’t bother! lol. WAY too long. At that point we didn’t really know what we were doing because the only source we had was an American book and we were investing through Hargreaves Landsdown (we didn’t know any better!) and so I picked a fund I could understand and invested in America, it was interesting as Katie invested less in America. We had no idea what we were doing and that was what I picked as I could understand it. Nothing more than that. And you are right, it is completely against our current way of thinking which we had not developed by then. Which then begs the question why haven’t I sold it? Laziness, inertia, and something I will do and eventually more into a global index fund…
On the emerging market we did indeed by a bit to balance out the Dev world fund we hold. It performed horrendously compared and we sold it eventually. This has led us to our way of thinking of just by the global fund as if you don’t you have to make buying and selling decisions, rebalancing decisions and more…
Everyone of the mistakes and anomolies you have spotted has been a learning point on our way to our current strategy…
Did that help at all?
Sending happiness
Alan
Thanks Alan, that ‘s a great explanation.
I also have a few funds that are the remnants of long-forgotten reasoning! I keep some of them just to remind me of earlier mistakes so that I might avoid repeats 😀
I like tinkering with asset allocation, so a single global fund doesn’t bring me joy (although it might sometimes bring better returns 😂)