

Join the mailing list!
Minimum Monthly Account Fees
Vanguard UK announced this week that from 31 January 2025 they are introducing a minimum monthly account fee.
Vanguard’s fees used to be a simple 0.15% of what you have invested and this is (and still will be) capped at £375 a year. This made them super cheap for new investors and very reasonable for investors with big pots too particularly as they also have zero dealing fees.
The change they’ve made is to introduce a minimum monthly account fee of £4. Doesn’t sound too bad? Well as we all know fees are critical when investing so Katie has been hard at work updating her Impact of Fees Tool for the Vanguard changes and we are working out what difference it will make for you!
For the full Vanguard Announcement straight from the horse’s mouth read this.
TLDR Summary
Not got time to read the whole article? Here is the short version:
- If you have over £32,000 invested with Vanguard across all your accounts (ISA and SIPP and general account) it doesn’t affect you at all
- The change doesn’t apply to Junior ISAs for your kids
- If you have a small pot and are a LONG way off getting to £32,000 then it might be worth switching to a different platform until you get to £32,000 total invested
Fee Floor
This is the first time Katie and I have seen a fee floor or minimum fee from a company with a percentage charge! This meant that Katie had to go in and add that to the fees tool.
The reason Vanguard have done this is to make the smaller portfolios they manage for people more profitable for them.
They were losing money if you set up a SIPP with them with only £100 in it. The fee you would pay them on an account of this size would be a whopping 15 pence a year!
It costs them WAY more than 15 pence a year to run your account and organise everything. So they have introduced the new minimum and it means that everyone pays at least £4 a month. But remember this fee is is across all account types that you have with Vanguard so look at your combined total across your SIPP, ISA and general account.
From January 2025, the lowest possible fee for having a SIPP, ISA and general account is £48 a year.
I can understand why they have done it but that doesn’t make me any less annoyed as Vanguard used to be the most incredible place to start investing because of its low fees.
The questions is now, should you change to another provider? Does this affect you? Is Vanguard still a good place to invest?
Panic and change?
Should you panic at the fee increases and change providers? No, absolutely not. The changes don’t come in until the end of January 2025 and we should be led by maths and logic in investment decisions. Let’s look at whether this affects you or not.
You will see a LOT of adverts coming out from other providers in the next few days and weeks trying to get you to change platform like this one from a new provider in the SIPP world, Monzo.
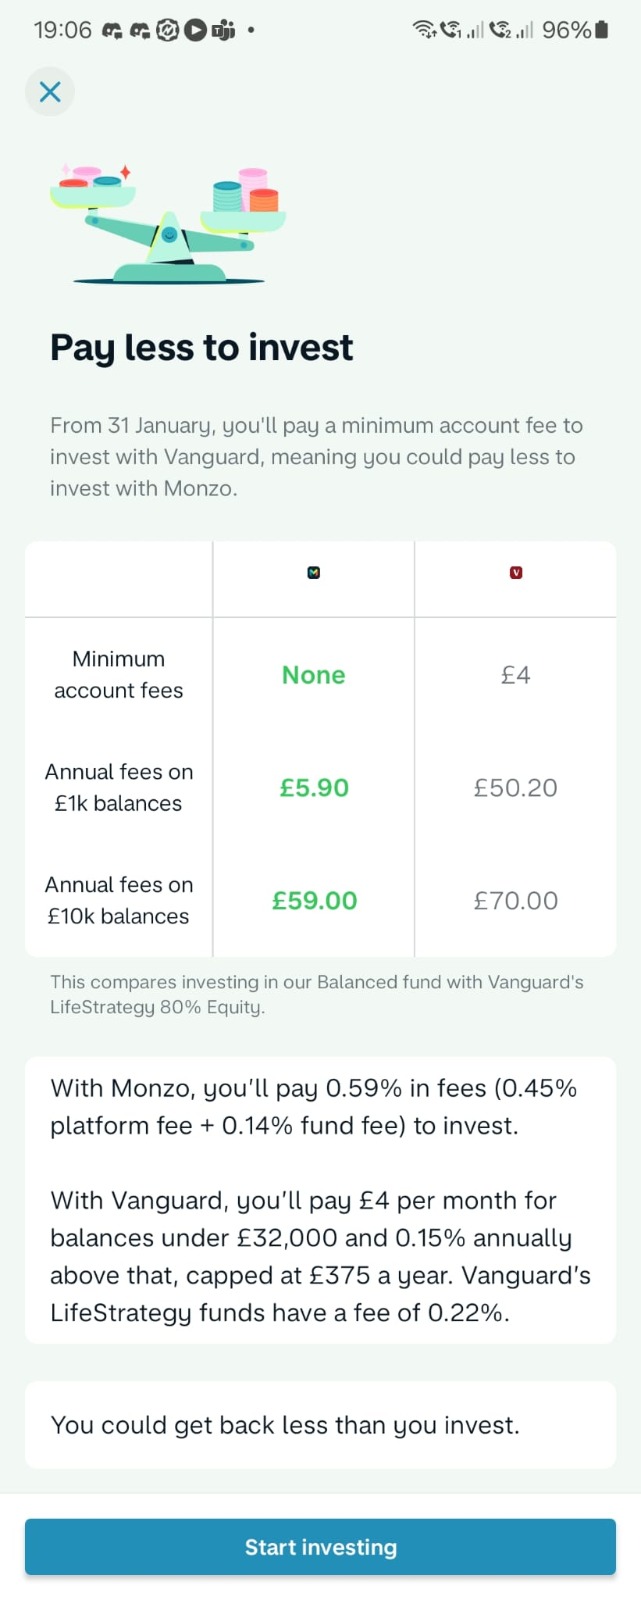
You should be very cautious moving your money around. Yes, Monzo has lower fees for the example they’ve cherry-picked but it only covers the first year of investing and assumes you don’t invest any more. Over the long run Monzo will cost you a FORTUNE more than Vanguard.
For their comparison, Monzo has also picked the LifeStrategy Vanguard fund which we would avoid at all costs.
The advertisers will use confusing maths and bad examples to persuade you to change to them so please be very aware and do the actual maths before making any big decisions. Watch out for our platform review coming soon.
It is not only fees that matter it is the funds you have access to. Monzo ONLY has target retirement funds and the one with the farthest out retirement date of 40 years away has 30% bonds. This would kill your long term financial future! Watch week 9 of the Rebel Finance School course to understand why this is BAD!
Having reviewed Monzo’s new SIPP I can see no reason why you would EVER use this service, it is costly and has poor fund choice and yet they will try and persuade you they are better than everyone else!
Don’t buy into the marketing hype, do the maths and the research everytime.
Above £32,000 total invested
If your accounts (ISA, SIPP and general account) all together total more than £32,000 then this change does not affect you at all. Not one little bit! YAY. You can stop reading this update now and go back to chilling, watching a movie or doing press-ups.
Junior ISA Fees
Vanguard has also announced that the changes do not affect fees on Junior ISAs so if you have these accounts for your kids then nothing has changed at all! YAY. Go Vanguard for looking after the little ones!
Below £32,000
You are just starting out, you don’t have that much to invest and you are way off £32,000 in total. Should you change?
The answer is “it depends!”.
To make it super easy Katie updated the Fees tool today so you can do your own numbers. You know the Donegans believe maths should guide us in investing decisions not emotion! So let’s do the maths.

The challenge with doing the maths is that everyone’s situation is different. If you have £20,000 invested and are putting in a few hundred a month then this change is going to be short lived for you and barely affect your future at all.
If you are starting out and you have nothing invested yet and are adding small amounts like £50 a month then this change will make a difference to you and you should use one of the other platforms until you get to £32,000 invested and then consider coming back to Vanguard.
All the numbers below were worked out on Katie’s Impact of fees tool
Example 1: Just starting
Let’s imagine you are starting today. You have nothing invested so far and you are going to invest £50 every month.
This is the type of situation that this new fee is going to impact the most. Using Katie’s Fee tool we can see the impact in the chart to the right.
In this situation you are now £3,834 or 5.8% WORSE off over 30 years from the changes. This is a big change and is mostly made up from lost compounding (the more of your money is taken in fees, the less it’s invested and compounding for you) not the fees themselves.

If this is you and you are just starting out and putting small amounts in then if I were you I would change to another platform. Katie and I are not ready to tell you which platform that would be in our opinion as we haven’t done our full research yet, but we are planning a full platform review to help you make a decision. The changes don’t come in until the end of January 2025 so just breathe and we can figure all this stuff out together.
Example 2: Making progress
Let’s say between your ISA and SIPP you have £15,000 invested and you are ploughing your money in regularly and investing £250 a month. What difference do the changes make if you are in this situation?
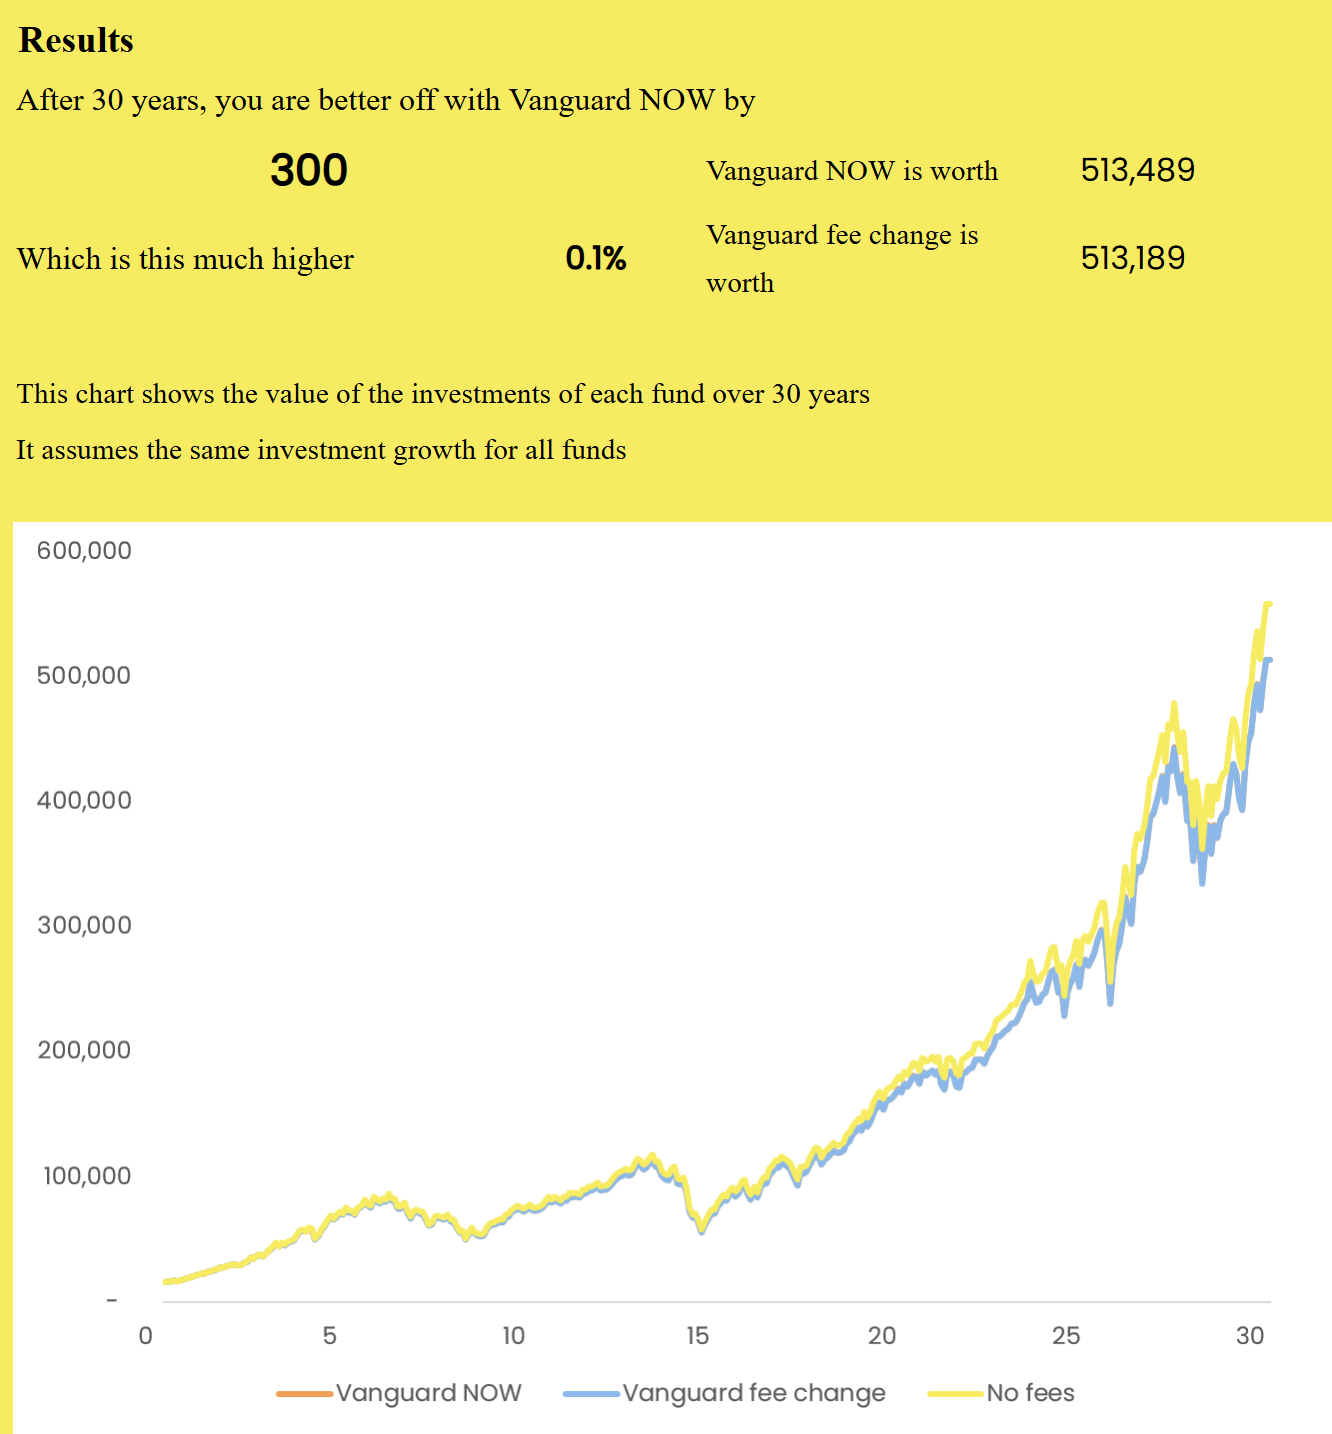
After 30 years you would be £300 worse off in fees and lost compounding. You’d have £513,489 instead of £513,189. At this point you will be crying into your pot of gold. Katie, and I would say the impact is so small we would not bother changing and consider it as our contribution to Vanguard building the platform for all of us.
Your personal situation
Katie and I can’t do the sums on every situation out there and we don’t know your numbers! But you do and you can plug them into Katie’s fee tool to see how much difference it will make in your situation. Click here for Katie’s Fees Tool and put your numbers in now.
All you need to do is put in 2 numbers in the orange box at the top:
- Initial investment: how much you currently have, combined across your ISA, SIPP and general account.
- Monthly investment: how much you plan on investing per month
Katie has pre-populated the tool with the fees for investing in the FTSE Global All Cap using the Vanguard UK platform both before (left hand side or “Vanguard NOW”) and after (right hand side or “Vanguard fee change”). If you have chosen the FTSE Developed World ex UK you can change the OCF to 0.14% on BOTH SIDES (the blue and green boxes) so that you’re comparing apples with apples.
If it makes less that £800 difference over £30 years it is really just noise on your portfolio and it probably isn’t worth changing. You are, after all, paying for the service and Vanguard will hopefully use the money to build out the app and keep developing the platform and paying some fees is a good thing! We want Vanguard to be around and working for us well into our retirement!
Summary
Whilst this Vanguard fee change will only affect early stage investors, it’s still super annoying to us. Why are the Donegans annoyed when it won’t affect them one bit?
Because we run a course that helps people get started in investing and it is those people that are going to be affected the most by this.
And because a bunch of other providers are swooping in to scoop up smaller investors. Always do the maths, think from a position of knowledge and don’t buy into the marketing hype out there from providers trying to get you to switch from Vanguard.
What should you do about the fee change?
Just starting out and investing small amounts. Change platforms. Look out for a platform update in the coming months that will guide you on which one to choose. Just take a deep breath, take your time and don’t make any quick decisions. A few months of £4 fees isn’t going to affect you a lot but it will probably be worth making a change. Stay tuned and we will help you through it.
Between £10,000 – £25,000 and regularly investing at least £100 a month. This change in fees will probably have a negligible impact on your investing life time. We would suggest ignoring it and keep on investing as quickly as you can to get over the £32,000 mark at which point the fee change doesn’t make a difference! Have a play with the Fees tool to see what the impact on fees over 30 years is likely to be.
One member of the Facebook group saw this as a challenge to go past £32,000 invested as quickly as possible! I loved how he used this update to motivate himself!
Over £32,000 – nothing has changed so carry on investing Captain!
Donegan Investing Update
The interesting thing for us is that this change has made us look at the fees on all our accounts and Katie woke up this morning with a realisation that we would be better off amalgamating her ex-Deloitte pension into Vanguard with our other investments as in our case having fewer platforms will save us money! We have been discussing moving all our investments into Vanguard today even though they have annoyed us with this update.
I have emailed Vanguard today to get a comment from them about the fee changes and to tell them that they are being short-sighted as the small investors they are charging more will become big investors over the long run as they keep investing. Who knows what they will reply with but I will keep you up to date over the coming weeks!
Look out for the platform review coming out over the next month or two that will guide you as to which platform to consider using.
What did you discover about your situation from running your numbers through the Fees tool? Leave us a comment below and tell us your thoughts. We are working to make it easy for anyone to do the maths and compare providers and funds.
Sending you huge peace and pineapples (although we never compare the size of these!)
The Donegans
PS As always, this post is intended for educational and information purposes, it is certainly NOT investment advice. You can read our full disclaimer here.
46 Comments
Leave A Comment
Related Articles

Blog, Financial Independence, Save and Invest
Where do I put my money? Hello there! We wrote this article in 2025. Platform fees in the UK have changed a lot since then! Look out for an updated article coming soon.....With such a confusing array of platforms, funds and fee structures how do you ever decide where to put your money? In [...]

Blog, Donegan Update, Keeping Track
5th Jan 2026 At the end of the year, Katie and I always get excited because this means a chance to do our annual finance review! How often do you review your finances? Do you check daily, as some people do when they first find out about investing, or are you a set it [...]

Blog, RFS2025, RFS2026
After every single Rebel Finance School session in 2025, Katie and I sat down and wrote notes about what we could improve for next time. We had a lot of ideas. But here’s the thing we’ve learned the hard way over the years: our ideas are not as important as what actually works for real [...]

I’ve just started investing 20k atm isa s&s with vanguard and will have 350k to invest next year when I sell a property so I’m happy to stay with vg. Thanks for all the advice I’ve recently retired at 53 so hopefully I’ll have enough money to see me through. I’ve watched all your episodes on fs so I’m a lot more confident now.
Thanks 👍
Glenn, what an awesome message to get. That is fab news about the money coming to invest and get you through and great decision on what to do next! Sending you much happiness. Alan
Thanks so much for this… the rate rise doesn’t affect me personally (Yay!) but will have implications for my partner, friends and colleagues who are looking at taking my lead and beginning their investment journeys…
Thanks for replying. it is super annoying. Platform review coming soon and let’s help them find the best platform for people starting out! Thank you
Thank you for this. Is there a reason that you are staying with VG with a larger investment portfolio? I’ moved my pension from Aviva to Vanguard but now I’m a bit more educated, I’ve done the sums and it says Interactive Investor will save me £56000 over Vanguard over 30 years. I like the Vanguard website and customer service. Is that’s your reason for staying?
Hey Jo, Did you use Katie’s Fees calculator to work that out? Tell us more. That seems huge. Vanguard is capped and it is more. At the large sized pensions it is a difference but it seemed small to us in terms of the portfolios you have at that point. For us the no fees for buying and selling, customer service and some other bits made us think we will go with that after doing the review! Thanks for commenting. You are awesome. Alan
Thank you Head Pineapples 🙏🏼🍍🙏🏼
Our pleasure. You are awesome!
Thank you both for your blog post on this, the financial emails I’ve received from others have been unsettling and worrying. Your sensible advice “do the maths” and your calm but realistic approach reinforced my faith and confidence in Rebel finance! Looking forward to next year’s course with you and the Ninjas, thank you Donegans!
Sharon, That is so good to hear. Thank you for replying. You are amazing. We have to say this to ourselves too as it is so easy to get caught up in the hype and the doom stuff online so we want to slow down and do the maths too! Thanks for replying. it means a lot. Sending happiness… Alan
Thanks for this – I’m just about to start investing, so I’m one of the ones affected. I will look out for updates and I guess just keep it in a bank account for now.
Hey Penny, that is annoying. We are doing a full platform review and will get back to you on good options asap! Look out for an update and we can help you get investing. Sending you happiness. Alan
oh this is so frustrating! I’ve literally just finished watching your week 8 lesson and headed over to the Vanguard site to get my SIPP started (new year, good intentions…) and saw this, I checked back here to see what you have to say and this has stopped me in my tracks! Hopefully a couple of weeks of time out of the market won’t slow me down too much so I’ll hold tight for now. Thank you for doing what you do!
Emma, the platform review is coming soon. We have got you. Are you transferring any pensions to a SIPP? Or is it starting afresh? Do you have a stocks and shares ISA? The minimum is over all the accounts you would have on Vanguard. Sending you happiness Alan
Thanks for the reply Alan :) I’d planned to start afresh as I hadn’t intended to move any of my pensions but now reconsidering…. I have around £70k in an existing pension from a former employer so maybe I should just move it over, it’s a substantial amount and I think I’m still a wee bit nervous! Food for thought and I’m pretty sure I know what you’d recommend!
Hey Emma, the questions are, what is the 70k invested in & what are the fees? If it isn’t great I would switch it over straight away if it was me! The other thought is to examine what you are nervous about? What is the fear or the thing that you think might happen? Sending you much positivity and the first time we moved a big amount we were super nervous too!
Update a couple of weeks later – I’ve gone ahead and transferred the pension, well I’ve requested it and now waiting for all the cogs behind the scenes to start whirring and making it happen! And regular payments into the Vanguard SIPP also set up – turning 50 this year and taking my retirement very seriously :)
That is so exciting Emma. I LOVE IT. You have made such huge progress. Thank you or replying and letting us know how you are getting on! you rock! ALan
Thank you for this! There’s been so much noise about the changes so it was helpful to use Katie’s tool and do the maths! I played around with the numbers and my current £50 monthly investment would cost me around £3700 overall. Adjusted it to pay in more and was able to bring it down to £1200. It’s just inspired me to widen my gap and get more serious about how much I’m investing ☺️
Natale, glad you found the article. AWESOME. Love how you are using it as motivation and that seems to be what a lot of the positive response have been. A desire to wide the gap and get the money working for you. LOVE your response. Alan
Thanks for this – it was just what I was looking for, as I was starting to worry! I’ll be leaving mine in and aiming to reach that target. I invested in Vanguard about four years ago as best I could, using what advice I could find, and went for the life strategy 80% equity accumulation and the SIPP target retirement 2035. Having seen a few of your videos I’m sensing that there were better options! Is it easy to change to different funds within Vanguard or am I now locked into these?
Thanks for all your efforts!
Steve, what a lovely comment. Yay and a great way to look at it. Target retirement and lifestrategy funds in the UK are both VERY home country bias which we believe is a bad thing and depending on what you have got you probably already have bonds which you don’t need till nearer retirement. SUPER easy to switch. Click the three dots near the fund and then press switch and it will ask you what you want to switch too. Does that help? Alan
Yep, that’s great. A straightforward answer that I can work with for something that didn’t seem obvious to me. I’ll keep watching your videos and then make an informed move when I’m confident with what I’m doing. Not planning on making millions – I have a teacher pension on the horizon so I’m trying to find ways to enhance this and fund an earlier retirement.
Thanks for the speedy response, much appreciated.
Our pleasure Steve. We like straight forward and simple where we can find it too! ANd that is fabulous you are topping up above the teachers stuff. Awesome work.
Hi there
A great post. Thanks for doing this :)
I’m retired and opened a SIPP (my first one) in Vanguard in August 2024 with £2880 & it was made up to the full amount, £3660, courtesy of HMRC. I don’t have anything else in Vanguard atm but I do have a number of ISAs in ii. With this in mind, I’m looking forward to the platform reviews soon then I can decide whether to consolidate all under ii or to add another full ISA plus a GIA to Vanguard which will then take me over the magic £32000. I have also played around with the excellent tool & bc of my age I don’t necessarily want it invested for 30 years! Love, peace & pineapples
Judith you are amazing. got it about II and Vanguard. We will come back to you about this!. LOVE seeing your name pop up! sending you happiness and watch out for more!
Thanks for your amazingly rapid response Alan. I’ve been a bit ‘awol’ over the last few months due to number of issues so I am on a grand catch up! Returning the love, happiness & 🍍🍍🍍
Sending you much love and happiness. It is just great to see your name popup! Hope to see you when we get back to the UK in April!
Oops I only just saw this after opening an ISA. But thinking can I transfer some of my Fundsmith ISA (150K) to get myself over the threshold?
Just to let you know I am a solo working mum with an adopted daughter with severe trauma. I blitzed your course in 5 days over christmas and I now feel so much better that if I have to reduce my working hours over the next few years to support my daughter I now have a strategy to ensure I can protect my retirement!
I just wish I found you 10 years ago.
One question I can;t work out. My work Pension is with Scottish Widows – There are only 2 Vanguard options I can transfer my fund to. Both say they have an element of sustainable managment so not sure they are the best options does anyone know what other Fund options there are that meet the RFC suggestions – Passive / Worldwide etc etc. I can’t move the Platform so I have to stick with Scottish Widows Platforms. Gutted I just missed your update meet up this year
Sally this is AMAZING. I love it. I just googled fund smith and they are an actively managed fund and they have high fees:
Fundsmith Equity T Acc ISA: The annual total charge is 1.83%, with 0.79% for platform charges and 1.04% for fund managers’ charges
Fundsmith Equity I Acc: The ongoing charge is 0.94%
Fundsmith Equity Class I – Accumulation (GBP): The ongoing charge is 0.94%
I would never want to have an actively managed fund and the fees are killing you so if it was me I would move this ASAP. They haven’t done very well compared to the market over the last few years.
You can then have a SIPP, ISA and all other accounts under one fee there which is useful. It will save you a LOT of money
On the other funds for Scottish widows depends what they are. Have you managed to find the fund fact sheets and analyse them?
Does this help at all? We aren’t financial advisors and don’t pretend to be them.
Sending you happiness
THANK YOU for replying and your message makes me so happy about spending more time with your daughter. This is AMAZING. Please stay in touch! Alan and Katie
Also I was wondering if you could explain the difference between Global Growth and Global Equity Funds? Thanks
Morning Sally, which platform is this on? Is this on Vanguard? It is confusing sometimes the language used but growth generally means that more of your portfolio is in equities, which global equity funds means you have all your money in equities and they are from around the world. The challenge is every institution uses different language to describe the funds and so the only real way to know is to look at the Benchmark and see how closely they follow it. Which funds are you looking at?
Hi Alan, Thanks so much for your quick response. The Fundsmith ISA was something I did about 20 years ago, it did very well for a while but as you say it has just stayed flat for years but had no idea about other options were out there. Now that I have opened the Vanguard ISA ‘FTSE Developed World UCITS ETF – Accumulating (VHVG)’ I am going to move it into this ISA.
I had an old Aviva Pension that was being killed by fees. I have opened a Vanguard Pension and am transfering this pension into it same fund’ ‘FTSE Developed World UCITS ETF – Accumulating (VHVG)’ (I depressing worked out it would have been worth 3 x value if I had moved it 10 years ago!) Oh well onwards and upwards
However I can’t move my current Scottish Widows Pension ‘Platform’ – So I have looked at the fund options available under Scottish Widows.
The only Vanguard options are:
Option 1: SW Vanguard ESG Developed World All Cap Equity Index 2 CS8
Option 2: SW Vanguard ESG Developed World All Cap Equity Index CS9
Both say . The Fund promotes environmental and social characteristics by excluding companies based on the impact of their conduct or products on society and/or the environment.
This doesn’t seem like a good option and they don;t seem to have performed as well.
Instead I am thinking to go with either
Scottish Widows Global Equity CS9
OR
Scottish Widows Global Growth 2 CS8
But I wasn’t clear about the difference
Hey Sally,
Nice work moving everything around and making choices. I LOVE IT.
I googled the Scottish Widows fund. Is this the one? https://www.trustnet.com/factsheets/N/ov33/scottish-widows-global-equity/ Seems to be an actively managed fund which I would not go for. If it was my money and I only had the choice of a vanguard ESG fund or actively managed fund I would always chose the passive fund.
Why can’t you move it? Are you still paying into it?
You are making great strides!
And I am singing your praises to everyone, you guys need to be on the national curriculum!
You are so kind! Sending you happiness Sally!
I’ve got a very small (less than 1k since going self employed) personal pension with pension bee @ 0.7% fees. I was going to transfer into vanguard but will now sit tight for your full review.
I’d love something on NEST too. My partner has a 6% employer contribution pension. I was thinking we contribute the minimum via NEST and the rest of the money we can invest can go into a SIPP – he’s a higher rate tax payer.
Claire, we have been working on the NEST stuff for a while. Just need to finish the book and then write those articles! We have too many projects but I know I need to do NEST. And the platform review is coming. We started this week putting it together.
Thanks for commenting. Alan
I really appreciate all that you both do, which has immensely improved my financial knowledge. I was about to invest but now feel stopped in my tracks due to the annoying new Vanguard charges. I am tentatively looking to compare other sites but at my level, it’s very hard to decipher. I am eagerly awaiting to hear what your ideas will be once you’ve done the research. Do you have an announcement date in mind? No pressure…ha ha!
Joanna, it was so so so annoying when that came in from Vanguard. They were clear winners before and I am a bit annoyed but we are where we are and just need to build from here. Platform review coming soon and that will help. We are hoping end of January will have it done and ready. Thanks for replying
Thank you so much for all the useful info. After reading the Simple Path to Wealth I am inspired to start investing. I found your blog when searching for UK equivalent info with relation to saving. I am a total novice when it comes to finances… English/arts have always been my subjects rather than maths but I am learning so much with your help! Looking forward to reading about which platforms you recommend for people like us just starting out. Sarah
Sarah, thank you for your awesome message. Simple path to wealth is a game changing book. We read it and spend a LONG time working out how it all worked in the UK and what was the VTSAX of the UK! lol. That is why we did the Rebel Finance School course and wrote this blog. You are amazing and thank you for commenting. Katie and Alan
Hi. I have £16k in my vanguard SIPP. Having watch your brilliant course I was about to transfer £40k from another provider. The main reason being the fees which eat away at my pot. I am now thinking why pay fees at all when I can move to T212 etc. that charge no fees. I shop around for the best utility/ phone providers etc so why stay with vanguard ? I do like vanguard site but isn’t that a emotional response rather than a financial response? I am looking at a 5-10 year before drawdown. Thanks
Hey Sally, Vanguard is still a great platform to use. We have a SIPP, ISA and more with them. We are thinking of transferring all our funds from Halifax to them as there is no draw down fees or buy and sell fees which is huge. T212 is a free platform which always concerns us as they have to make money from somewhere and if it is not on the fees where will it be coming from and how long will it be around? That is why we haven’t gone with them. We are working on the platform update coming soon!
Hi guys, I know this is very late in the day (thread) however I noticed in this post you mentioned not touching the Vanguard Life strategy – I currently have two kids ISAS with this as the main investment. With the article saying that KIDS ISAs aren’t affected by the fee changes, are there s reasons (in your opinion) that I shouldnt be investing in this? Would be keen to understand. 👍 thank you! 🙏
Hey Hazel, thanks for commenting. This was a video we did about those funds a while back:https://share.google/ddIVlT5eSjBXNKByp Do you have the ones that are global or the ones with the heavy home country bias? They released a new set this year and have two different sets of these funds now…. We generally think that a global index fund will give you a better outcome over time.. Sending happiness. Alan